From a licensed wallet in São Tomé and Príncipe to a five-market African payments network, Sao Payment Global is positioning Ghana as its Anglophone West African hub—armed with a DEMI licence, ISO certifications, and a proposition that is more infrastructure than wallet.
Executive Introduction
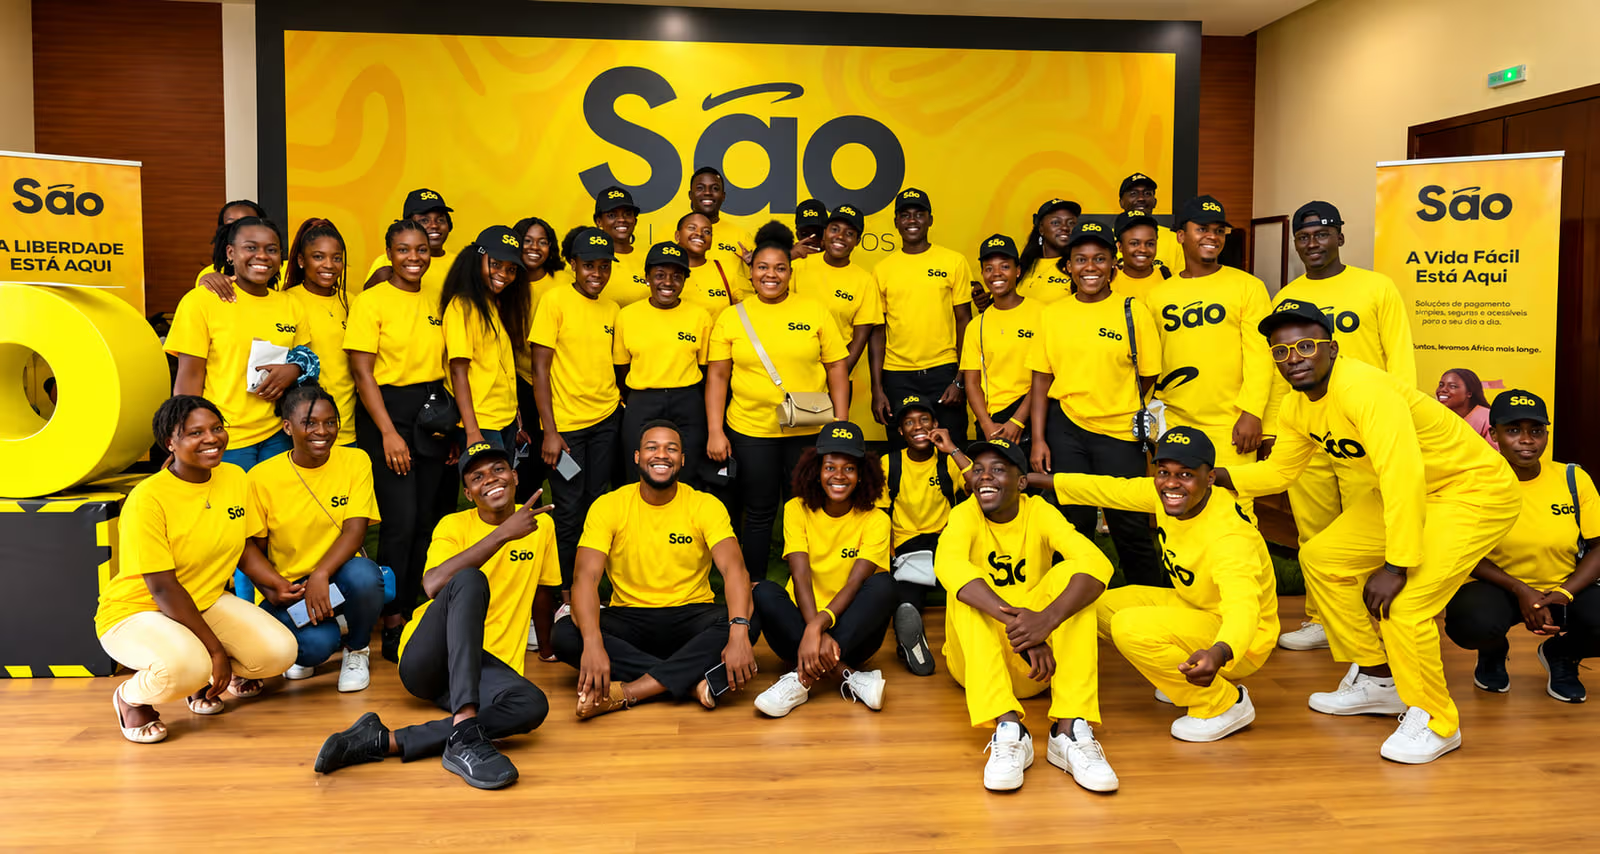
On October 7, 2026, at the Labadi Beach Hotel in Accra, a fintech company few Ghanaians had heard of officially launched operations. But Sao Payment Global Limited is not a typical new entrant. Founded in São Tomé and Príncipe, the company has quietly built a licensed payments footprint across five African markets—São Tomé, Liberia, Sierra Leone, The Gambia, and now Ghana—with ambitions to reach ten markets by the end of 2026 .

The company’s proposition is distinct from the wallet wars that have dominated Ghana’s mobile money landscape. As its Group CEO stated at the launch: “Sao is not building a wallet. Sao is building a connected rail: a single infrastructure on which money moves between countries, between institutions and between people, under licence, at low cost” .
📢 GET A DETAILED ARTICLES + JOBS
Join ASJ's WhatsApp Channel and never miss a post or opportunity.

That infrastructure-first framing matters. Ghana’s fintech sector has no shortage of wallets. According to Bank of Ghana Governor Dr. Johnson Asiama, the country had approximately 85.8 million registered mobile money accounts holding nearly GH¢40 billion in customer balances as of August 2026. But only about 26.4 million of those accounts had been used in the preceding 90 days . The central bank’s message to the sector was blunt: the next phase must focus on usage, not access.
Sao’s entry is calibrated to that reality. With a Dedicated Electronic Money Issuer (DEMI) licence from the Bank of Ghana, ISO certifications (9001, 22301, 27001, 20000-1), and a partnership roster that includes Visa, Mastercard, Western Union, RIA, Ecobank, UBA, and GTCO, the company is not competing for wallet downloads. It is competing for the plumbing that makes those wallets useful .

This ASJ profile examines Sao’s origins in São Tomé, its Ghana launch strategy, its product architecture (Sao Wallet, Group Savings Wallets, Sao Pay), its regulatory positioning, and the question that will determine its trajectory: Can a company that positions itself as infrastructure rather than consumer brand build the trust and network density required to matter in Ghana’s crowded payments market?
Company Overview: From São Tomé to Anglophone West Africa
The Genesis: Solving a Financial Access Gap
Sao Payment Global Limited was founded in São Tomé and Príncipe, a small island nation off the coast of Central Africa. The founding insight was straightforward: ordinary citizens lacked access to licensed digital wallet, agent network, and payments infrastructure . The company set out to build what the market was missing—not another consumer app, but the licensed rails on which digital finance could operate.
The Expansion Timeline
| Market | Status | Significance |
|---|---|---|
| São Tomé and Príncipe | Live (home market) | Founding market |
| Liberia | Live | First expansion |
| Sierra Leone | Live | Second expansion |
| The Gambia | Live | Third expansion |
| Ghana | Live (October 2026) | Fifth market; Anglophone West Africa hub |
| Rwanda | In progress | Target by end 2026 |
| Tanzania | In progress | Target by end 2026 |
| Three additional markets | In progress | Target by end 2026 |
Source: The High Street Business
Ghana is not just another market in Sao’s expansion. The company has designated it as its hub for Anglophone West Africa, its centre for regional regulatory coordination, and a connection point for payment corridors linking Africa with Europe, the Gulf, and North America .
“Sao is a global payments company with African roots. Ghana is strategically important to that story,” the company’s Country General Manager said at the launch. “Ghanaians do not need just another wallet. They need a better one” .
The GTI Holding Connection
Sao’s technology and expansion are supported by GTI Switch, a subsidiary of Ghana-based investment conglomerate GTI Holding. In its H1 2025 results, GTI Holding described GTI Switch as the “parent company behind Sao Wallet and Saopay,” powering “transformative fintech experiences across multiple African markets” .
This relationship matters for understanding Sao’s Ghana strategy. GTI Holding is a Ghanaian entity with existing market knowledge, regulatory relationships, and distribution networks. Sao’s Ghana launch is, in effect, a homecoming for the technology—even if the licensed entity is São Toméan in origin.
The Product Architecture: Rails, Not Wallets
Sao’s product suite at launch reflects its infrastructure-first philosophy. The company is not trying to win a consumer beauty contest. It is trying to become the layer that other financial services sit on.
Sao Wallet: The Consumer Interface
The Sao Wallet is the company’s consumer-facing product—but it is designed with infrastructure principles. Key features include :

-
Ghana Card onboarding in approximately two minutes, without visiting a branch
-
Peer-to-peer money transfers
-
Bill payments and airtime purchases
-
QR payments to merchants
-
Cash-in and cash-out through the Sao agent network
The Ghana Card integration is notable. Ghana’s national biometric ID has become the backbone of financial KYC, and Sao’s ability to onboard in two minutes using it positions the wallet for mass adoption.
Group Savings Wallets: Digitising Susu
One of Sao’s more distinctive offerings is Group Savings Wallets, designed for the savings structures that are deeply embedded in Ghanaian and West African financial culture :
-
Susu groups (rotating savings and credit associations)
-
Family savings pools
-
Church welfare groups
-
Community associations
The product allows members to make visible contributions and operate under agreed withdrawal rules. This is not a cosmetic feature. Susu is a foundational financial institution across West Africa, and most digital financial products have failed to serve it authentically. By building a product that respects the governance and transparency norms of these groups, Sao is targeting a segment that traditional banks have largely ignored.
Sao Pay: Merchant Acceptance
For businesses, Sao Pay enables QR code payment acceptance at no upfront cost, along with collections, payouts, and settlement capabilities . The company is also developing solutions for institutions including churches, schools, SMEs, government agencies, NGOs, and FMCG distribution networks.
Sao Agent: The Physical Layer
Digital wallets still require physical cash-in and cash-out points. Sao’s Sao Agent network allows customers to locate nearby registered agents through a live map in the app, with information on operating hours and availability .
Agent networks are capital-intensive and slow to build. Sao’s ability to scale its agent footprint will be a critical test in Ghana, where competitors like Fidelity Bank and mobile money operators have years of head start.
Regulatory Positioning: The DEMI Licence and Its Boundaries
The Licence
Sao operates in Ghana under a Dedicated Electronic Money Issuer (DEMI) licence from the Bank of Ghana . This licence authorises the company to issue electronic money, hold customer balances, and operate an agent network.
The Bank of Ghana’s Conditions
Governor Dr. Johnson Asiama used the Sao launch as an opportunity to articulate the central bank’s expectations for all e-money issuers. His remarks were pointed :
On customer funds: “Every new entry is a reminder of what an electronic money balance represents. It is cedis held in a new form, and a promise that the value is real, safe and available when needed” .
The Governor stressed that Sao must ensure customer balances are properly backed and reconciled across its e-money platform, bank position, and corresponding customer funds. He described reconciliation, accurate regulatory returns, and safeguarding customer funds as core elements of trust, not routine back-office functions .
On cybersecurity: Sao is expected to onboard onto the Financial Industry Command Security Operations Centre (FICSOC) and maintain investment in cyber resilience as its customer base and transaction volumes expand .
On customer protection: The Governor cited risks including fraud, weak KYC, inadequate customer due diligence, internal control failures, and agent training gaps. Pricing transparency is also required, with fees and commissions across agent and merchant networks to be clearly disclosed .
On licence boundaries: “A licence is not a reward for a good application. It is an authorisation to hold the public’s trust, under supervision,” the Governor said. Services such as investment, savings, credit, insurance, and pension products must be provided through appropriately regulated partners or with required approvals .
On AI and data: The central bank encouraged Sao to use artificial intelligence and data analytics responsibly in areas such as customer due diligence, fraud monitoring, and credit scoring, with governance developing alongside adoption .
Sao’s Commitments
In response to these expectations, Sao has made several public commitments :
| Commitment | Detail |
|---|---|
| Transparency | Publish Ghana tariff in full; display fees before transaction confirmation |
| Complaint handling | Acknowledge within 2 hours; resolve first-tier issues within 24 hours; disputes within 48 hours |
| Data protection | Process data in accordance with Ghana’s Data Protection Act, 2012 (Act 843) |
| Certifications | ISO 9001, ISO 22301, ISO 27001, ISO 20000-1 |
| Inclusion targets | 40% of registrations from first-time formal financial users; 40%+ active users women; 30%+ under 30; half of merchant activations women-owned by 2030 |
The Strategic Question: Infrastructure vs. Consumer Brand
Sao’s positioning raises a fundamental strategic question. In Ghana’s payments market, the winners have largely been consumer brands: MTN MoMo, Telecel Cash, and the wallets that achieved mass adoption through telco distribution. Sao is explicitly not competing on that axis.
Its bet is that the next phase of African payments will be won by whoever builds the most connected, licensed, and interoperable rails—the infrastructure that allows wallets, banks, merchants, and cross-border corridors to speak to each other. This is a more patient, more capital-intensive, and less visible strategy.
The partnership roster supports this thesis. Visa, Mastercard, Western Union, RIA, Ecobank, UBA, and GTCO are not consumer brands in the wallet sense. They are institutions that move money . Sao’s value to them is as a licensed local rail that connects their global networks to African markets.
But infrastructure businesses face a chicken-and-egg problem. They need volume to be valuable, and volume requires consumer adoption. Sao’s Group Savings Wallets and agent network are attempts to solve that—by embedding into existing financial behaviours (susu, cash-in/cash-out) rather than trying to create new ones.
Challenges and Risks
Risk 1: Agent Network Scale
Sao’s agent network is nascent. Competitors have years of head start, and agent density is a critical determinant of wallet utility. Building a nationwide agent network requires significant capital and operational discipline.
Risk 2: Wallet Adoption Fatigue
Ghana has 85.8 million registered mobile money accounts but only 26.4 million active ones. Adding another wallet to the market does not automatically create usage. Sao’s differentiation—group savings, transparency commitments—must be compelling enough to change behaviour.
Risk 3: Regulatory Scrutiny
The Bank of Ghana’s launch-day remarks were a clear signal that Sao will be watched closely. Failure on reconciliation, cybersecurity, or customer protection could result in sanctions or licence conditions.
Risk 4: Cross-Border Execution
Sao’s regional expansion (five markets live, ten targeted by end 2026) is ambitious. Each market has distinct regulatory frameworks, currency regimes, and competitive dynamics. Executing across ten markets simultaneously is a significant operational challenge.
Risk 5: Brand Recognition
Sao is an unknown brand in Ghana. Building trust with consumers who have never heard of the company—especially in a sector where trust is everything—will require sustained marketing and demonstrated reliability.
Future Outlook
Sao’s Ghana launch is a bet on a specific vision of African payments: one where licensed, interoperable infrastructure matters more than consumer-facing brand. Whether that bet pays off depends on execution across several dimensions:
-
Agent network growth: Can Sao build enough cash-in/cash-out points to make the wallet useful?
-
Group savings adoption: Will susu groups, churches, and associations trust a new platform with their savings?
-
Regulatory compliance: Can Sao meet the Bank of Ghana’s expectations on reconciliation, cybersecurity, and transparency?
-
Regional coordination: Can Ghana function as a genuine hub for Anglophone West Africa, connecting to São Tomé, Liberia, Sierra Leone, and The Gambia?
-
Partner integration: Will Visa, Mastercard, Western Union, and others route meaningful volume through Sao’s rails?
The company has the licences, the certifications, and the partnerships. What it does not yet have is scale, brand recognition, or a proven track record in Ghana. Those are earned, not licensed.
FAQ SECTION
1. Is Sao Payment Global a Ghanaian company?
No. Sao Payment Global Limited was founded in São Tomé and Príncipe. However, its technology is supported by GTI Switch, a subsidiary of Ghana-based GTI Holding, and it has designated Ghana as its hub for Anglophone West Africa .
2. When did Sao Payment Global launch in Ghana?
Sao launched its Ghana operations on October 7, 2026, at the Labadi Beach Hotel in Accra .
3. What licence does Sao hold in Ghana?
Sao operates under a Dedicated Electronic Money Issuer (DEMI) licence from the Bank of Ghana .
4. What is the Sao Wallet?
The Sao Wallet is a digital wallet that can be opened using a Ghana Card in approximately two minutes without visiting a branch. It supports money transfers, bill payments, airtime purchases, QR merchant payments, and cash-in/cash-out through the agent network .
5. What are Group Savings Wallets?
Group Savings Wallets are designed for susu groups, families, church welfare groups, and associations. Members can make visible contributions and operate under agreed withdrawal rules .
6. Who are Sao‘s partners?
Sao‘s partners include Visa, Mastercard, Western Union, RIA, Ecobank, UBA, and GTCO .
7. What did the Bank of Ghana say about Sao‘s launch?
Governor Dr. Johnson Asiama emphasised that e-money issuers must safeguard customer funds, ensure reconciliation, maintain cybersecurity, and operate within licence boundaries. He stressed that the next phase of digital finance must focus on usage, not just access .
8. What certifications does Sao hold?
Sao holds ISO 9001, ISO 22301, ISO 27001, and ISO 20000-1 certifications .
9. How many markets does Sao operate in?
Sao currently operates in five markets: São Tomé and Príncipe, Liberia, Sierra Leone, The Gambia, and Ghana. It targets ten markets by the end of 2026, with Rwanda and Tanzania in progress .
10. What inclusion targets has Sao set for Ghana?
Sao targets 40% of registrations from first-time formal financial users, 40%+ active users being women, 30%+ under age 30, and half of merchant activations being women-owned by 2030 .
QUICK FACTS BOX
| Item | Details |
|---|---|
| Legal Name | Sao Payment Global Limited |
| Founded | São Tomé and Príncipe |
| Ghana Launch | October 7, 2026 |
| Licence Type | Dedicated Electronic Money Issuer (DEMI) |
| Ghana Hub Role | Anglophone West Africa |
| Country General Manager | Kenneth Selase Ometha |
| Group CEO | James Bruce |
| Live Markets | 5 (São Tomé, Liberia, Sierra Leone, The Gambia, Ghana) |
| Target Markets | 10 by end 2026 |
| Key Products | Sao Wallet, Group Savings Wallets, Sao Pay, Sao Agent |
| Key Partners | Visa, Mastercard, Western Union, RIA, Ecobank, UBA, GTCO |
| Certifications | ISO 9001, ISO 22301, ISO 27001, ISO 20000-1 |
| Complaint Response | 2 hours acknowledge; 24 hours first-tier; 48 hours disputes |
| Parent Technology | GTI Switch (GTI Holding) |
| Website | saopayment.com |
Source: Accra Street Journal
Last Updated on October 16, 2026 by Samuel Kwame Boadu
Disclaimer: Some content on Accra Street Journal may be aggregated, summarized, or edited from third-party sources for informational purposes. Images and media are used under fair use or royalty-free licenses. Accra Street Journal is a subsidiary of SamBoad Publishing Hub under SamBoad Business Group Ltd, registered in Ghana since 2014.
For concerns or inquiries, please visit our Privacy Policy or Contact Page.

Samuel Kwame Boadu is a Ghanaian media entrepreneur and storyteller with a passion for amplifying urban voices and uncovering everyday truths. He is the Editor-in-Chief and Founder of Accra Street Journal, a dynamic digital platform dedicated to capturing the pulse of Ghana’s capital—its people, culture, challenges, business, sports and innovations.