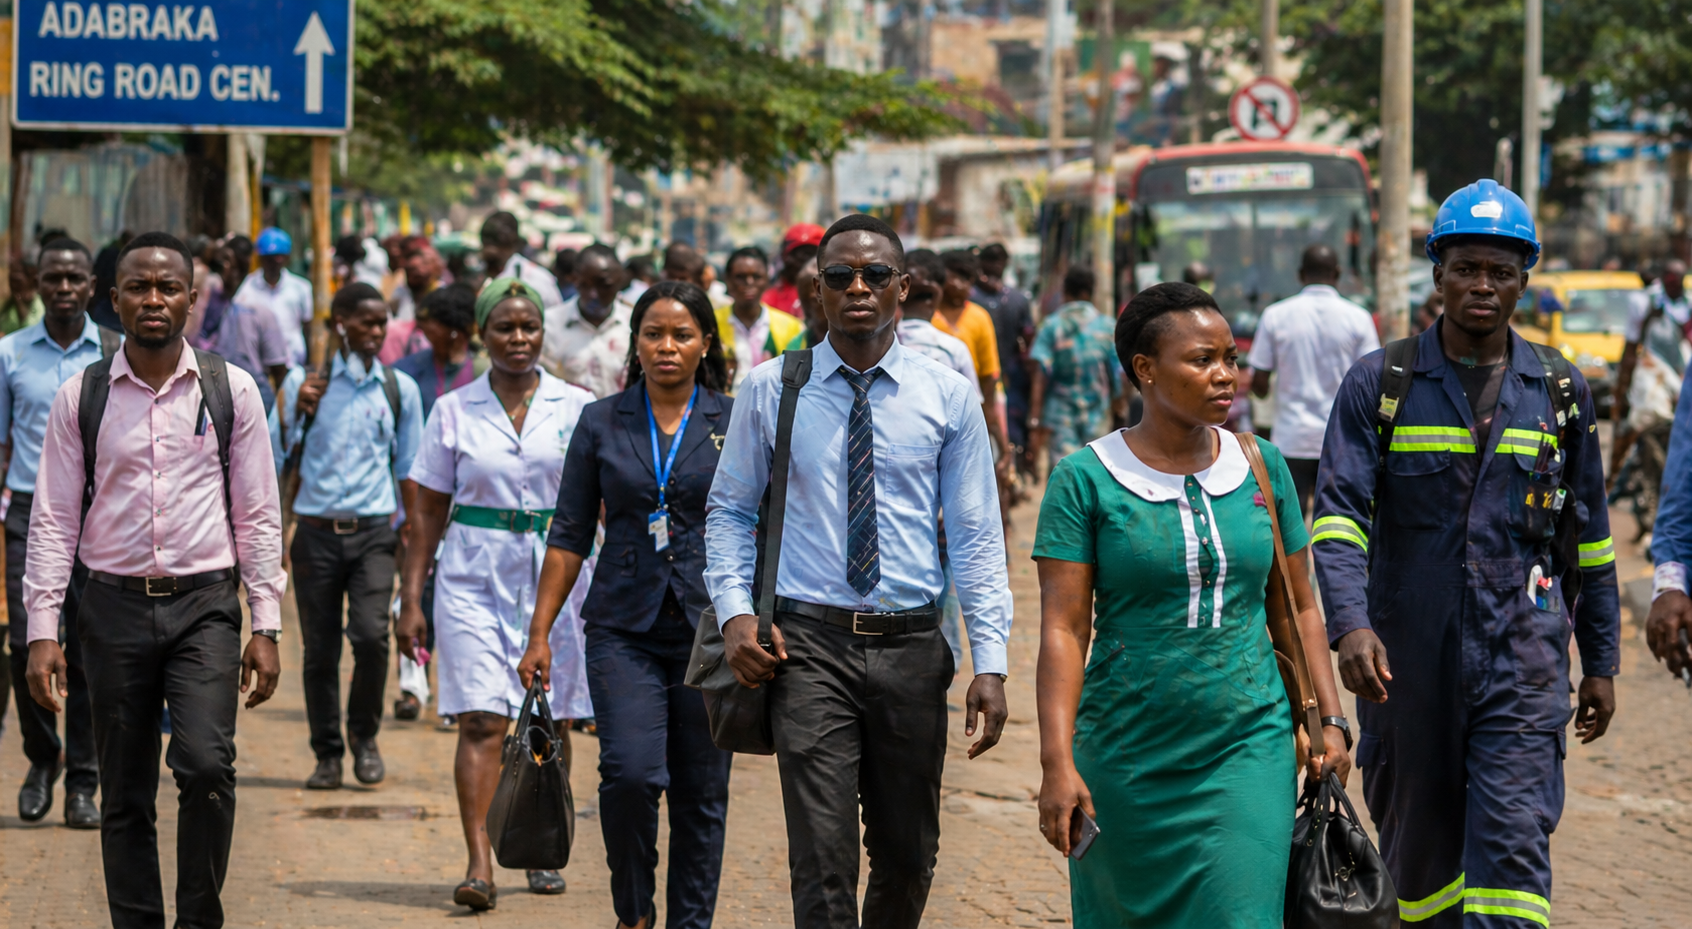
From stagnant wages to a 90% informal economy — the structural forces keeping financial security out of reach
Executive Introduction
When the monthly salary hits the bank account, the relief is immediate—but so is the pressure. Within days, sometimes hours, the money is gone. Rent. School fees. Transport. Food. Utility bills. By the second week, the balance is near zero. By the third week, the borrowing begins: a loan from a friend, an advance from a susu group, or a high-interest mobile money loan that will eat into next month’s pay before it arrives.
This is not a story of poor financial management. It is a story of structural inequality.

The numbers are stark. In Ghana, approximately 90 percent of the workforce is in the informal sector, where income is irregular, savings are minimal, and financial buffers are a luxury . With inflation currently at around 3.5 percent, the real value of wages has been eroded . The minimum daily wage, adjusted to GH¢23.28, translates to a monthly salary of about GH¢700 — an amount that is insufficient to meet basic needs in urban areas . Many households with multiple income earners still struggle to make ends meet, as expenses consistently outpace income .
📢 GET A DETAILED ARTICLES + JOBS
Join ASJ's WhatsApp Channel and never miss a post or opportunity.

This ASJ report examines why many Ghanaians continue to live paycheck to paycheck: the wage stagnation that has failed to keep pace with inflation, the dominance of informal employment, the debt trap that makes recovery impossible, the urban-rural cost-of-living divide, and the structural barriers to financial inclusion.
Part 1: The Wage-Inflation Disconnect
The Arithmetic of Survival
A casual worker in Accra earns between GHS 100 and GHS 150 per day, often in cash, with no formal contract, no paid leave, and no job security . For market women and informal sector workers, income is even less predictable, with daily earnings fluctuating between GHS 50 and GHS 150 depending on market conditions .

The mismatch is devastating. A household with an informal worker and a small-scale trader can earn approximately GHS 1,500–1,800 per month. Yet a recent breakdown of monthly expenses for a typical Accra household earning GHS 4,000 shows that rent alone can consume 30–50% of income in high-demand areas.
| Expense Category | Typical Monthly Cost (GHS) | Notes |
|---|---|---|
| Rent | 1,500–2,000 | 30–50% of income in high-demand areas |
| Groceries & Food | 800–1,200 | Fluctuating food prices |
| Utilities (Electricity, Water, Gas) | 300–500 | High electricity costs |
| Transportation | 200–400 | Tro-tro and occasional Uber |
| School Fees/Child Expenses | 300–600 | Public schools still require fees |
| Mobile Data and Airtime | 100–200 | Essential for work and communication |
| Health and Emergency | 200–500 | Unpredictable |
| Debt Repayment | 200–500 | Payday loans, susu, or informal lending |
Source: Adapted from Ghana salary and cost of living ASJ reports
The Stagnant Wage Problem
For salaried workers, the situation is not much better. Wages have not kept pace with inflation. In 2026, the minimum wage is GH¢23.28 per day, but many private sector workers earn above the minimum and are still struggling . Public sector salaries often do not match the cost of living, particularly for teachers, nurses, and civil servants in urban centers like Accra . Many workers have resorted to taking on additional income-generating activities to supplement their primary salaries .
The Minimum Wage Reality
Even the minimum wage is inadequate. In 2026, the minimum wage is GH¢23.28 per day, which translates to a monthly salary of about GH¢700—an amount insufficient to meet basic needs in urban areas . With inflation at around 3.5% and the cost of living continuing to rise in cities, the real value of the minimum wage has eroded . The national minimum wage is unenforceable in the informal sector, where most workers do not benefit from formal wage protection .
Part 2: The Informal Employment Trap
90% of the Workforce, 0% Protection
Approximately 90 percent of the workforce is in the informal sector—a reality that fundamentally shapes household financial vulnerability . Informal workers lack:
-
Job security: No contracts, no notice periods, no severance
-
Benefits: No paid leave, no health insurance, no pension contributions
-
Income stability: Daily earnings fluctuate with market conditions
-
Access to credit: Banks require formal documentation that informal workers cannot provide
The Precarious Daily Reality
For the casual worker earning GHS 100–150 per day, a single day of illness, a market downturn, or a transport strike can wipe out a week’s income. There is no buffer. There is no safety net. There is only the relentless pressure to show up and earn, every single day.
The Skill-Education Gap
Many workers lack formal qualifications or employable skills, making them susceptible to low-paying, unstable jobs . The Ghana Living Standards Survey confirms that low-skill, low-wage employment dominates the labour market, and workers are often trapped in low-paying jobs with no clear path to progression .
Part 3: The Debt Trap
When income is insufficient to cover expenses, borrowing is not a choice—it is a survival mechanism. But the cost of borrowing often makes survival harder.
The Payday Loan Cycle
For many Ghanaians, digital lending platforms have become the default emergency fund. A worker earning GHS 2,000 per month who faces a GHS 500 emergency—a child’s school fee, a medical bill—may take a payday loan.

The arithmetic: A short-term loan of GHS 500 at 10–20% interest over 30 days means repaying GHS 550–600. For a worker living paycheck to paycheck, that extra GHS 50–100 comes directly out of the next month’s already inadequate income. The result: the same worker will need another loan next month, starting a cycle that can last for years.
Informal Lending
A majority of Ghanaian workers and small business owners still rely on family and friends for loans—a traditional and trusted system—while a growing number are turning to digital microloans. Susu groups offer interest-free or low-interest loans, but the capital is limited and the repayment terms are strict.
The Mobile Money Debt Burden
Research from the 2026 International Journal of Research Publication found that mobile money “tends to impose debt burdens” due to high transaction costs, interest rates, and service fees, sometimes exceeding 10% per transaction . The same study concluded that “high costs and fees often push users into debt cycles or deplete savings, particularly among low-income households” .
Part 4: The Urban-Rural Cost Divide
Living in Accra is expensive—far more expensive than rural areas—but that is precisely where the jobs are.
Rent: 30–50% of Income
Rent in Accra consumes 30–50% of income . A moderate 2-bedroom apartment in a middle-income neighbourhood like Tema, Spintex, or East Legon costs between GHS 1,500 and GHS 2,500 per month. A similar property in Kumasi costs 20–30% less. A single room in a compound house is more affordable but still consumes a large share of income.
The Rural-Urban Migration Paradox
Accra’s population growth is driven by rural-urban migration as people move to the city in search of economic opportunities . However, the city’s infrastructure, housing supply, and job creation have failed to keep pace, pushing up costs for everyone .
Transportation Costs
Urban commuters spend a significant portion of their income on transport. Workers earning GHS 2,000–3,000 monthly spend approximately GHS 440 per month on transport—22% of income . These costs are far higher than for rural workers, who often walk or have shorter commutes.
Part 5: Systemic Barriers to Financial Stability
The problem is not individual financial behaviour. It is a system that makes stability structurally impossible.
1. Limited Access to Formal Banking
Despite the growth of mobile money, formal banking remains out of reach for many. A lack of formal documentation and unstable incomes means informal sector workers cannot open bank accounts or access credit. Even when accounts are opened, hidden charges, high minimum balances, and monthly fees keep low-income users from building meaningful savings .
2. Tax Burden on Wages
Tax expert Ismail Ibn Ibrahim warned in August 2025 that Ghana’s tax structure is “unsustainable” for households . Under PAYE, workers face income tax rates starting at 20%, with reliefs that have not kept pace with inflation . Beyond income tax, families are squeezed by multiple consumption taxes: 15% VAT, 2.5% National Health Insurance Levy, 2.5% GETFund Levy, a 1% COVID-19 Levy, and a 3% VAT Flat Rate . These levies “are unavoidable and steadily erode disposable income” .
3. Financial Illiteracy
Data indicates that only about 32% of Ghanaians are financially literate . This means the majority lack the basic competence required to manage money effectively—to distinguish between legitimate and fraudulent investment opportunities, to calculate compound returns, or to assess risk .

4. The Sunk Cost of Sickness
A family emergency—an accident, an illness, or a death—can wipe out months of savings. With only about 32% of Ghanaians financially literate and the majority in the informal sector, households lack the knowledge and resources to plan for such emergencies . Health emergencies are one of the most common causes of household debt.
Part 6: The Policy Gaps
The Unenforceable Minimum Wage
The national minimum wage is unenforceable in the informal sector, where most workers do not benefit from formal wage protection . This means that for the majority of workers, the minimum wage is irrelevant—they are paid what the market dictates.
Limited Social Safety Nets
Social welfare programs in Ghana—including the Livelihood Empowerment Against Poverty (LEAP) programme and the National Health Insurance Scheme—are underfunded and have limited coverage . Without a robust social protection system, households are one emergency away from financial collapse.
The Absence of Affordable Housing
Rent consumes 30–50% of income in high-demand areas . The housing deficit—estimated at more than 1.8 million units—drives up rents and makes homeownership impossible for most.
Conclusion: The Paycheck-to-Paycheck Trap Is Structural
Living paycheck to paycheck in Ghana is not a personal failing. It is a structural condition. When 90% of the workforce is in the informal sector, when minimum wage is GHS 700 a month, when rent consumes 30–50% of income, when taxes erode disposable income, when a GHS 500 emergency requires a GHS 500 loan with 10–20% interest, financial stability is not a matter of discipline—it is a matter of privilege.
The solutions are structural: enforceable minimum wage, affordable housing, social safety nets, financial literacy, and access to affordable credit. Until these are addressed, the paycheck-to-paycheck cycle will continue—not because Ghanaians are bad with money, but because the system is not designed to let them keep it.
Quick Reference: Living Paycheck to Paycheck in Ghana
| Indicator | Value |
|---|---|
| Formal sector workforce | ~10% |
| Informal sector workforce | ~90% |
| Daily minimum wage (2026) | GH¢23.28 |
| Monthly minimum wage | ~GH¢700 |
| Monthly rent (Accra, 2-bedroom) | GH¢1,500–2,500 |
| Rent as % of income | 30–50% |
| Monthly transport cost (GH¢2k–3k workers) | ~GH¢440 (22% of income) |
| Financial literacy rate | ~32% |
| Mobile money debt burden | High (transaction costs 10%+) |
| Informal sector wage protection | None |
| Social safety net coverage | Limited |
Source: Accra Street Journal
Last Updated on July 22, 2026 by Samuel Kwame Boadu
Disclaimer: Some content on Accra Street Journal may be aggregated, summarized, or edited from third-party sources for informational purposes. Images and media are used under fair use or royalty-free licenses. Accra Street Journal is a subsidiary of SamBoad Publishing Hub under SamBoad Business Group Ltd, registered in Ghana since 2014.
For concerns or inquiries, please visit our Privacy Policy or Contact Page.

Samuel Kwame Boadu is a Ghanaian media entrepreneur and storyteller with a passion for amplifying urban voices and uncovering everyday truths. He is the Editor-in-Chief and Founder of Accra Street Journal, a dynamic digital platform dedicated to capturing the pulse of Ghana’s capital—its people, culture, challenges, business, sports and innovations.