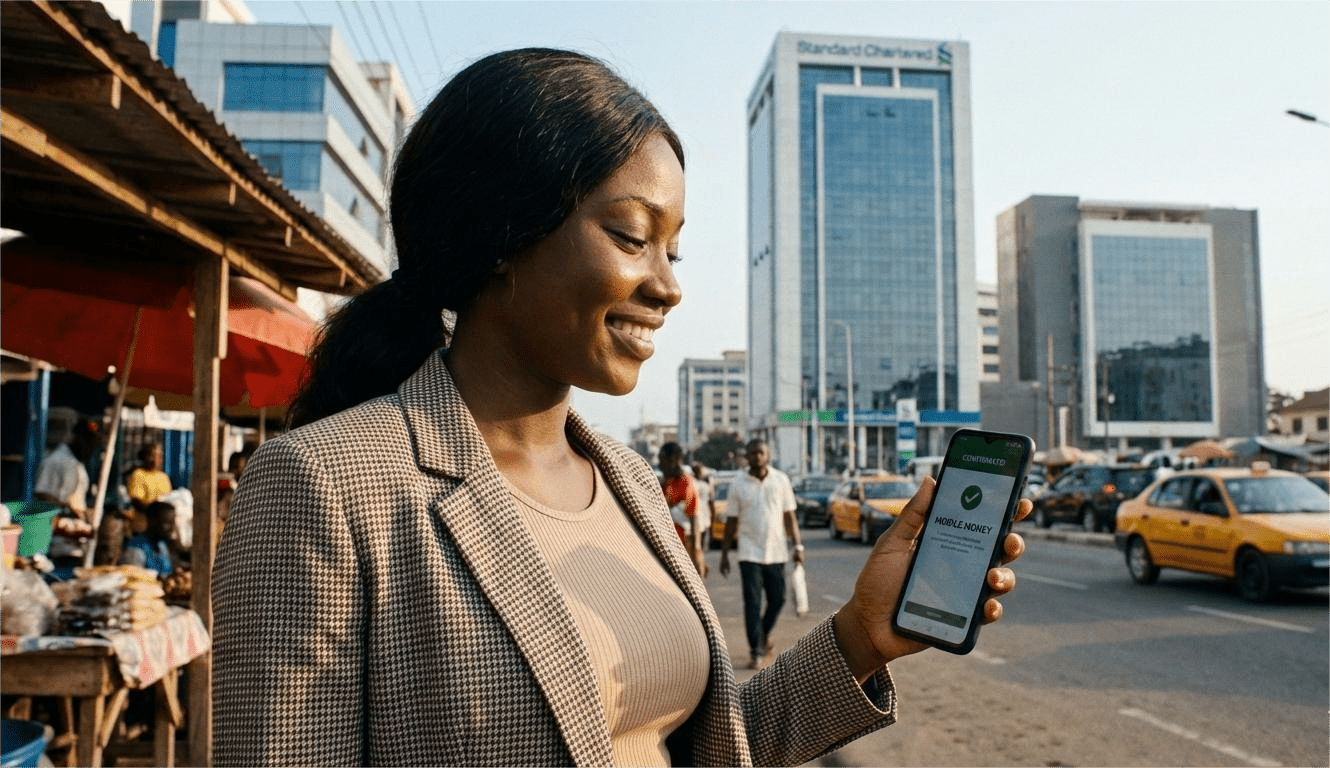
How Digital Payments Have Changed Everyday Life
A decade ago, everyday transactions in Ghana were overwhelmingly cash-based. From paying taxi fares to settling school fees, physical currency dominated commercial life. Today, that reality has fundamentally shifted.
Digital payments—powered by mobile money, fintech platforms, and electronic banking—have reshaped how individuals earn, spend, save, and transfer money. The change has been gradual but profound. What began as a convenience has evolved into core economic infrastructure.

In cities like Accra, the cashless shift is visible daily: QR codes at retail counters, mobile money numbers displayed on signboards, and instant transfers replacing long bank queues.
📢 GET A DETAILED ARTICLES + JOBS
Join ASJ's WhatsApp Channel and never miss a post or opportunity.

This transformation is not merely technological. It is social, economic, and cultural.
The Rise of Mobile Money
The most significant catalyst for digital payments in Ghana has been mobile money. Telecom-led financial services enabled millions of people—many previously unbanked—to participate in formal financial transactions.

Today, individuals can:
-
Send and receive money instantly
-
Pay utility bills remotely
-
Purchase airtime and data
-
Make merchant payments
-
Receive salaries or business proceeds
Mobile money agents have become as common as traditional bank branches. In many communities, they are the first point of financial access.
This accessibility dramatically reduced dependency on physical cash.
Convenience and Time Efficiency
One of the most immediate impacts of digital payments is time savings.
Before digital systems, paying bills required physical travel and queuing. Sending money to relatives in another region meant visiting a bank or transport station. Businesses handled bulk cash deposits manually.
Digital payments have compressed transaction time from hours to seconds.
The economic implications are substantial. Time saved translates into productivity gains—particularly for small business owners who can now manage payments remotely.
Financial Inclusion and Empowerment
Digital payments have extended financial services to underserved populations. Individuals without traditional bank accounts can now:
-
Store money securely
-
Access transaction histories
-
Build informal credit profiles
-
Participate in e-commerce
For women and informal sector workers, this access has enhanced financial independence. Market traders, artisans, and small-scale entrepreneurs can receive payments digitally without relying on physical cash handling.

The inclusion effect strengthens economic participation across income levels.
Business Transformation
Small and medium-sized enterprises (SMEs) have experienced notable operational shifts due to digital payments.
Businesses now benefit from:
-
Reduced cash handling risks
-
Automated transaction records
-
Faster settlement cycles
-
Improved inventory management through digital tracking
Online merchants, in particular, rely heavily on integrated payment gateways. Without digital transactions, the e-commerce sector would struggle to function efficiently.
Digital payments have become foundational to Ghana’s growing digital economy.
Government Revenue and Transparency
The expansion of electronic transactions has also improved traceability. Digital records create audit trails, reducing leakage and improving tax collection efficiency.
Government agencies and public institutions increasingly accept digital payments for:
-
Licenses and permits
-
Utility services
-
Public fees
This transition supports transparency and reduces corruption risks associated with cash-based systems.
Social Behavior and Cultural Shifts
Beyond economics, digital payments have altered social interactions.
Splitting bills among friends, contributing to events, or supporting family members can now be done instantly. The immediacy has changed expectations—delays that were once normal are now perceived as inefficiencies.
Younger generations, particularly urban residents, increasingly view cash as optional rather than essential.
The normalization of digital transactions is reshaping consumer habits.
The Growth of Fintech Innovation
The digital payment boom has stimulated broader fintech development. Startups have built platforms offering:
-
Micro-lending services
-
Investment apps
-
Cross-border remittance solutions
-
Merchant analytics tools
These innovations build on payment infrastructure, expanding financial services into new areas.
Digital payments serve as the entry point into a larger financial ecosystem.
Security and Risk Considerations
While digital payments offer convenience, they also introduce new risks:
-
Phishing scams
-
SIM swap attacks
-
Data privacy concerns
Financial literacy has become increasingly important. Users must understand digital security practices to protect their funds.
As adoption grows, regulatory oversight and consumer education must evolve alongside technology.
Urban-Rural Dynamics
Digital payment adoption is strongest in urban centers like Accra, where smartphone penetration and internet connectivity are highest. However, mobile money has bridged many rural gaps.
In remote communities, digital transactions reduce the need for long-distance travel to access banking services.
The result is greater economic integration across regions.
The Pandemic Acceleration Effect
Global disruptions accelerated digital payment adoption. Health concerns increased demand for contactless transactions. Businesses that previously resisted digital platforms adopted them out of necessity.
What began as temporary adaptation became permanent behavior change.
The acceleration effect compressed years of digital migration into a shorter timeframe.
Long-Term Economic Implications
Digital payments are laying the groundwork for:
-
A more formalized economy
-
Improved credit access through transaction data
-
Enhanced SME scalability
-
Increased foreign investment confidence
Investors and multinational firms prefer markets with efficient digital payment systems. Payment infrastructure signals economic modernization.
Ghana’s digital payment ecosystem strengthens its competitiveness within West Africa.
A Structural Shift Toward a Cash-Light Economy
It is important to note that Ghana is not entirely cashless. Physical currency remains relevant, particularly in informal markets. However, the trajectory is clear: cash dependency is declining.
The shift is structural, not temporary. Digital payments are now embedded in daily life.
From transport fares to tuition fees, the cashless option is no longer an exception—it is standard.
The Road Ahead
Future developments may include:
-
Expanded QR-based merchant payments
-
Integration with regional payment systems
-
Enhanced digital identity verification
-
Broader access to digital credit
The foundation has already been established. Digital payments are no longer a convenience layer; they are economic infrastructure.
The transformation of everyday life in Ghana reflects a deeper modernization process—one transaction at a time.
FAQs
1. What are digital payments?
Digital payments are electronic transactions made through mobile money, online banking, payment apps, or card systems instead of physical cash.
2. How have digital payments improved financial inclusion?
They provide access to financial services for individuals without traditional bank accounts, enabling secure money storage and transfers.
3. Are digital payments safe?
They are generally secure when users follow proper security practices, though cyber risks require vigilance.
4. Why are businesses adopting digital payments?
Digital systems reduce cash handling risks, improve efficiency, and support e-commerce growth.
5. Is Ghana moving toward a cashless economy?
While not fully cashless, Ghana is increasingly becoming cash-light as digital transactions continue to expand.
Source: Accra Street Journal
Last Updated on March 9, 2026 by Samuel Kwame Boadu
Disclaimer: Some content on Accra Street Journal may be aggregated, summarized, or edited from third-party sources for informational purposes. Images and media are used under fair use or royalty-free licenses. Accra Street Journal is a subsidiary of SamBoad Publishing Hub under SamBoad Business Group Ltd, registered in Ghana since 2014.
For concerns or inquiries, please visit our Privacy Policy or Contact Page.

Samuel Kwame Boadu is a Ghanaian media entrepreneur and storyteller with a passion for amplifying urban voices and uncovering everyday truths. He is the Editor-in-Chief and Founder of Accra Street Journal, a dynamic digital platform dedicated to capturing the pulse of Ghana’s capital—its people, culture, challenges, business, sports and innovations.