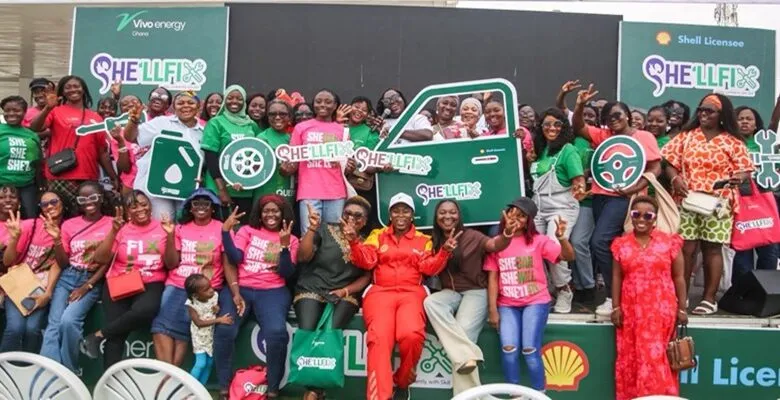
Ranked third among Ghana‘s 200+ oil marketing companies, with a 6.98% market share, a $240 million annual import bill, and a 244-strong retail network, the exclusive distributor of Shell-branded products is executing a quiet but powerful strategy: premium differentiation, non-fuel retail expansion, and aggressive network growth. Under the leadership of new Managing Director Christian Li—a 30-year industry veteran—the company is investing in modern service stations (Shell Michel Camp), multi-brand food courts (KFC, Burger King), and green energy solutions (lithium battery swaps).
Yet, as local giants GOIL and Star Oil wage a fierce price war for the top spot, Vivo Energy’s premium positioning strategy faces a critical test: can the Shell brand‘s superior quality and service justify its price premium in a cost-conscious market?
Executive Introduction
In Ghana‘s fiercely contested downstream petroleum sector—where nearly 200 oil marketing companies (OMCs) compete for the wallet of every driver—Vivo Energy Ghana PLC occupies a distinctive and enviable position. It is the exclusive marketer and distributor of Shell-branded fuels and lubricants, a brand that has been present in Ghana since 1928 and carries a global reputation for quality and innovation.
📢 GET A DETAILED ARTICLES + JOBS
Join ASJ's WhatsApp Channel and never miss a post or opportunity.
The company‘s metrics are substantial. It operates a network of 244 service stations nationwide (including a new station at Michel Camp commissioned in February 2026), has a fuel storage capacity of 11,000 cubic metres, and recorded an impressive $239.74 million in import turnover between January and December 2025.
Yet, 2026 has brought significant change and sobering market realities. The company welcomed a new Managing Director, Christian Li, in April 2025—a Mauritian national with nearly 30 years of experience across 20 African countries. Meanwhile, the competitive landscape has shifted dramatically. According to recent National Petroleum Authority (NPA) data, Vivo Energy Ghana currently ranks as the third-largest OMC in the country, holding a 6.98% market share, behind GOIL (11.93%) and Star Oil.

This ASJ report examines the Vivo Energy Ghana model: the power of the Shell brand, the 2023 financial performance (11.4% market share, 244 stations), the 2025 leadership transition, the aggressive network expansion (including non-fuel retail growth of 9%), the competitive positioning in a price-sensitive market, and the critical question: Can the premium strategy of the Shell brand survive—and thrive—against the aggressive pricing of state-backed GOIL and the rapid expansion of indigenous challengers?
Company Overview: The Shell Custodian
The 2013 Founding and the Shell Heritage
Vivo Energy Ghana was established in 2013 following the acquisition and rebranding of Shell’s downstream businesses in several African markets. However, the Shell brand’s history in Ghana dates back much further—to 1928, when Shell first established a presence in the country. For nearly a century, the yellow Shell scallop shell has been a symbol of quality fuel, trusted by Ghanaian motorists, industrial enterprises, and aviation operators.
The company operates as a subsidiary of the Vivo Energy Group, which itself was formed in 2011. In a significant development, in 2024, Vivo Energy completed a transaction to combine its business with Engen, creating a pan-African energy giant operating in 28 markets with a network of over 3,900 service stations. This merger has strengthened Vivo Energy Ghana‘s access to supply chains, lubricants technology, and best practices.
Ownership and Group Structure
| Entity | Role |
|---|---|
| Vivo Energy Group | Ultimate parent (Pan-African) |
| Vivo Energy Ghana PLC | Ghana operating subsidiary |
| Royal Dutch Shell (Licensor) | Brand licensing agreement |
Vivo Energy Ghana holds an exclusive licence to distribute and market Shell-branded fuels and lubricants in Ghana. The company is listed on the Ghana Stock Exchange (ticker: VEOG), offering public investors access to the Shell brand‘s downstream operations.
Leadership: Christian Li — The 30-Year Veteran
Mr. Christian Li was appointed Managing Director of Vivo Energy Ghana in April 2025, following the passing of his predecessor, Jean-Michel Arlandis. Li is a Mauritian national who brings nearly three decades of experience in general management, business development, and sales and marketing across more than 20 African countries.
Career Trajectory:
| Period | Role | Organisation |
|---|---|---|
| 2022–2025 | Head of International Business | Engen |
| 2018–2022 | Managing Director | Engen Namibia |
| Pre-2011 | Various leadership roles | Chevron |
| 2011–2018 | Various leadership roles | Engen Mauritius, South Africa, Republic of Congo |
During his tenure as Managing Director of Engen Namibia, Li was recognised among the top 10 executives for three consecutive years.
Leadership Philosophy:
Announcing his appointment, Franck Konan-Yahaut, Vivo Energy Executive Vice President for West and Central Africa, stated:
“Christian brings on board a wealth of knowledge, commitment to excellence and continuous improvement and will be an invaluable addition to our team.”
Li responded:
“Having worked in various capacities across multiple sectors, I am optimistic that we will elevate an already robust business to enviable heights.”
His appointment signals a continued focus on operational excellence, network expansion, and innovation.
Key Operational Metrics (2023–2026)
| Metric | Value |
|---|---|
| Founded (in current form) | 2013 |
| Brand Heritage | Shell in Ghana since 1928 |
| Managing Director | Christian Li (appointed April 2025) |
| 2023 Station Count | 244 (12 added that year) |
| 2026 Station Count | 244+ (25 Shell-branded stations confirmed) |
| 2023 Market Share | 11.4% (2nd place) |
| 2026 Market Share | 6.98% (3rd place) |
| Storage Capacity | 11,000m³ |
| 2025 Import Turnover | $239.74 million |
| 2025 Export Turnover | $22.85 million |
| Total Employees (Group) | Approx. 6,000 |
| Stock Ticker | GHSE: VEOG |
The 2023 Annual Report: Profitability and Expansion
The 2023 Annual Report provides a detailed baseline for Vivo Energy Ghana‘s performance before the recent leadership change and market share shifts.
Retail Network: 244 Stations and the #2 Rank
In 2023, the retail business was at the forefront of driving recovery and growth.
-
Station Expansion: The company added 12 new stations during the year, closing with a network of 244 stations across the country.
-
Market Share: Vivo Energy Ghana maintained its position as the second-largest OMC, with a market share of 11.4% .
-
Throughput: Average throughput remained strong at 14,000 litres per station, one of the highest in the industry.
-
Brand Licence Audit: The company successfully passed the Shell Brand Licence Audit with the highest score within the Vivo Energy Group—94% . This score granted Vivo Energy Ghana the rights to continue distributing and marketing Shell fuels and lubricants.
Non-Fuel Retail (NFR): The 9% Growth Engine
A key differentiator for Vivo Energy Ghana is its investment in non-fuel retail—convenience shops, quick-service restaurants, and other services that transform a petrol station into a destination.
-
Growth: Non-fuel retail delivered a steady growth of 9% over the previous period.
-
New Restaurants: The company opened three new restaurants, including a stand-alone partnership with KFC at East Legon.
-
New Shops: Ten new convenience retail shops were added across the country.
-
Green Energy & Innovation: Through strategic partnerships, the company introduced green energy solutions, including lithium battery swaps for motorbikes —an innovative offering targeting the commercial transport sector.
The Shell Michel Camp station, commissioned in February 2026, exemplifies this strategy. It features:
-
Shell Select convenience shop
-
KFC quick-service restaurant
-
Pharmacy for community access to medical supplies
-
Shell Lube Bay for lubrication services
Business-to-Business (B2B) and Lubricants
The B2B segment serves a wide range of sectors, including aviation, mining, construction, transport, agriculture, manufacturing, and power generation.
However, the lubricants segment faced headwinds in 2023, with a 3% decline in volume sales and a 13% decrease in gross profit, attributed to reduced consumer spending and challenging economic conditions. Despite this, the company maintained a significant market share through strong partnerships with key retailers, distributors, and commercial clients.
The 2023 Financial Context
The 2023 results reflect a company in a strong competitive position—second place in the market, growing its station network aggressively, and diversifying revenue through non-fuel retail. However, the 2023 market share of 11.4% would prove to be a high-water mark, as the competitive landscape shifted dramatically in 2025 and 2026.
The 2025 Trade Engine: $240 Million in Imports
According to MarketInside data covering January to December 2025, Vivo Energy Ghana recorded substantial international trade activity.
| Metric | Value |
|---|---|
| Import Turnover | $239.74 million |
| Export Turnover | $22.85 million |
| Import Shipments | 1,191 |
| Export Shipments | 68 |
| Primary Industry | Petroleum products |
-
Scale: $239.74 million in imports represents a massive volume of refined petroleum products—petrol, diesel, jet fuel, and marine fuels.
-
Global Sourcing: The volume of shipments (1,191) indicates a complex, high-frequency supply chain operation.
-
Export Activity: While exports ($22.85 million) are significantly smaller than imports, they represent the company‘s role in regional trade, supplying neighbouring markets.
The CEO‘s reference to the ability to offer jet fuel “at competitive terms at airports across the globe via strategic partners” is supported by this sophisticated trading operation.
The 2026 Market Reality: Third Place and the Fight Ahead
The NPA Market Share Data (January–February 2026)
Data from the National Petroleum Authority (NPA) provides a clear snapshot of the current competitive hierarchy.
| Rank | OMC | Total Sales (Litres) | Market Share |
|---|---|---|---|
| 1 | GOIL PLC | 158,173,164 | 11.93% |
| 2 | Star Oil | Not fully detailed | Not fully detailed |
| 3 | Vivo Energy Ghana | 92,546,100 | 6.98% |
| 4 | Zen Petroleum | N/A | N/A |
| 5 | TotalEnergies | N/A | N/A |
Key Observations:
-
The Market is Concentrated: The top five players (GOIL, Star Oil, Vivo Energy, Zen Petroleum, TotalEnergies) control a significant share of the market, but nearly 200 registered OMCs compete for the remainder.
-
Vivo Energy‘s Position: At 6.98% market share, Vivo Energy Ghana is a solid third-place player—ahead of TotalEnergies but significantly behind the market leader, GOIL (11.93%). The gap between Vivo Energy and the top two is substantial.
-
Network Size Comparison:
-
GOIL operates over 400 stations
-
Vivo Energy, Star Oil, and TotalEnergies each operate over 250 stations
-
Zen Petroleum operates more than 60 stations
-
-
The Regional Leaders:
-
GOIL dominates the Upper East, Upper West, North East, Savannah, Northern, Oti, and Volta regions
-
Vivo Energy leads in Bono, Bono East, and Ahafo regions
-
The Star Oil Rise and the Price War Context
In October 2025, Star Oil overtook GOIL to become the market leader for a period, recording a 41.02% increase in product volumes and reaching a 15.21% market share. While Vivo Energy does not compete directly on price with these aggressive indigenous players, the intense price war between GOIL and Star Oil has likely compressed margins across the sector.
As one analysis noted: “For decades, the industry has been dominated by state-owned GOIL, France-based TotalEnergies, and Shell, whose majority shareholder is Vivo Energy” . The rise of Star Oil and GOIL’s aggressive counter-offensive has fundamentally altered this long-standing hierarchy.
The Premium Positioning Dilemma
Vivo Energy Ghana‘s core strategic challenge is that it competes on premium quality (Shell V-Power, Shell FuelSave) rather than on price.
| Brand | Positioning | Price Level |
|---|---|---|
| Shell (Vivo Energy) | Premium (quality, engine cleaning, fuel efficiency) | Higher |
| GOIL | National champion, aggressive pricing | Competitive |
| Star Oil | Challenger, price-focused | Lower |
In a market where the cost of fuel is a primary concern for consumers and businesses, the premium positioning is both a strength and a vulnerability. It is a strength because it builds brand loyalty among quality-conscious motorists. It is a vulnerability because when disposable income is squeezed, consumers may switch to cheaper alternatives regardless of brand loyalty.
The 2026 Network Expansion: Shell Michel Camp
On February 11, 2026, Vivo Energy Ghana commissioned a new Shell service station at Michel Camp, Tema. The station is part of the company‘s growing retail network, which includes 25 Shell-branded service stations nationwide (a subset of the total 244 stations, which include other formats).
Key Features of the Michel Camp Station:
| Feature | Description |
|---|---|
| Branding | Shell‘s New Mobility Visual Identity |
| Fuels | Shell V-Power (engine cleaning, performance), Shell FuelSave (fuel efficiency) |
| Convenience Retail | Shell Select shop |
| Food Service | KFC (Quick Service Restaurant) |
| Healthcare | Pharmacy |
| Vehicle Services | Shell Lube Bay |
Speaking at the commissioning, Christian Li stated:
“Shell Michel Camp features Shell’s New Mobility Visual Identity, which reflects the company‘s modern retail concept and enhanced customer service experience. This represents our commitment to delivering more than just premium fuel. We aim to provide convenience, efficiency and high-quality service to our customers while contributing to community development.”
This station format is the blueprint for Vivo Energy Ghana‘s future expansion: a multi-service destination, not merely a fuel stop. The inclusion of a pharmacy is particularly innovative, reflecting a strategy to embed the station as a community hub.
The station is expected to create employment opportunities for young people within the Michel Camp community, supporting local economic growth.
The 2025 Corporate Rebrand: The ‘Dynamic V‘
In February 2025, Vivo Energy unveiled a new corporate brand, following the successful combination of the Engen and Vivo Energy businesses in 2024.
Key Elements of the Rebrand:
| Element | Description |
|---|---|
| New Logo | ‘Dynamic V‘—symbolising momentum, leadership, and unity |
| Brand Personality | Confident, straightforward, and passionate |
| Colour Palette | Energy, innovation, and growth |
Important Distinction: The rebrand applies to the corporate entity (Vivo Energy), not to the consumer-facing Shell brand. As the press release clarified:
“Shell and Engen remained Vivo Energy‘s primary consumer brands, continuing to engage customers with their unique identities and attributes.”
Stan Mittelman, CEO of Vivo Energy, explained the rationale:
“As our company expands, we need a modern, dynamic corporate brand that embodies our growth and unifies us under a single, powerful identity… With our new corporate brand, we are better positioned to lead, innovate, and drive progress across the continent.”
For the Ghanaian consumer, the yellow Shell scallop shell remains unchanged—preserving the brand equity built over nearly a century.
Competitive Landscape: Vivo Energy vs. GOIL vs. Star Oil
The “Big Three” Hierarchy
| Rank | OMC | Strengths | Vivo Energy‘s Position |
|---|---|---|---|
| 1 | GOIL | State backing, largest network (400+ stations), national champion status | Vivo Energy does not compete on network size |
| 2 | Star Oil | Aggressive pricing, rapid volume growth (41% increase) | Vivo Energy competes on quality, not price |
| 3 | Vivo Energy | Shell brand equity, premium quality, non-fuel retail | Differentiation through service and destination retail |
| 4 | Zen Petroleum | Growing indigenous competitor | Smaller network |
| 5 | TotalEnergies | Global major, similar premium positioning | Direct premium competitor |
The Regional Strongholds
While GOIL dominates the northern regions, Vivo Energy has established leadership in:
-
Bono Region
-
Ahafo Region
This regional concentration suggests a strategy of focusing investment on areas where the company can achieve critical mass and brand dominance, rather than spreading resources thinly across the entire country.
The ‘Shell Premium‘ Strategy
Vivo Energy Ghana‘s product differentiation is built on the technical superiority of Shell fuels:
-
Shell V-Power: Formulated to clean critical engine parts and improve engine performance
-
Shell FuelSave: Designed to improve fuel efficiency and help motorists travel longer distances per tank
This is a rational strategy: compete on the value delivered to the customer (engine protection, fuel efficiency), not merely on the price at the pump. For commercial fleet operators—where fuel is a major operating expense—the fuel efficiency benefits of Shell FuelSave can justify a higher price point.
The Non-Fuel Retail Moat
A second layer of differentiation is the service station as a destination:
-
Food: KFC, Burger King, Chicken Inn, Pizza Hut, and other brands are available at Shell stations.
-
Convenience: Shell Select shops offer a wide range of everyday consumer products.
-
Additional Services: Car washes, lube bays, and now pharmacies.
This non-fuel retail revenue stream—which grew 9% in 2023—is a buffer against thin fuel margins and a mechanism for customer loyalty.
Challenges and Risks
No analysis of Vivo Energy Ghana is complete without acknowledging the headwinds it faces.
Risk 1: The Price War Compression
The aggressive price competition between GOIL and Star Oil inevitably compresses margins across the entire sector. Vivo Energy‘s premium positioning protects it somewhat, but sustained margin pressure could affect profitability and limit investment in network expansion.
Risk 2: Currency Volatility
Vivo Energy imports the vast majority of its products ($239.74 million in 2025). The company sells its products in Cedis but purchases in US dollars. The cedi‘s volatility directly affects landed costs. When the cedi depreciates, Vivo Energy faces a choice: raise pump prices (risking customer defection) or absorb costs (compressing margins).
Risk 3: The GOIL Resurgence
GOIL‘s aggressive recovery—slashing its debt from $110 million to $30 million, doubling pre-tax profit, and reclaiming market leadership—makes it a more formidable competitor. A financially healthy GOIL is a threat to every other OMC.
Risk 4: Station Network Age and Maintenance
While Vivo Energy has added 12 stations in 2023 and continues to open new sites, some stations in the 244-strong network may require capital investment to maintain the Shell brand standards.
Risk 5: Supply Chain Complexity
Operating 1,191 import shipments annually requires sophisticated logistics, storage (11,000m³ capacity), and distribution management. Any disruption—shipping delays, port congestion, storage issues—immediately affects station supply.
Risk 6: Brand Licence Renewal
The Shell brand licence is the company‘s most valuable asset. The 94% audit score in 2023 is strong, but maintaining that standard across a large, geographically dispersed network requires constant vigilance.
Risk 7: Electric Vehicle Transition
The global automotive industry is transitioning to electric vehicles. While Ghana‘s EV adoption is nascent, the long-term trend is clear. Vivo Energy must position itself for this transition—potentially by installing EV charging infrastructure at its stations.
Risk 8: Regulatory Changes
The National Petroleum Authority (NPA) sets pricing benchmarks, enforces quality standards, and issues operating licences. Changes in regulatory policy could affect margins or impose new compliance costs.
Future Outlook
As of June 2026, Vivo Energy Ghana is executing a strategy of premium differentiation, non-fuel retail expansion, and selective network growth. The company has strong fundamentals: a globally respected brand, a diversified revenue base (fuel + non-fuel), and a new Managing Director with deep African experience.
The Immediate Agenda (2026-2027)
-
Defend Third Place: Maintain market share against aggressive challengers (Zen Petroleum) and stabilise position behind GOIL and Star Oil.
-
Scale Non-Fuel Retail: Continue the 9% growth trajectory; introduce additional food brands; expand the pharmacy concept to more stations.
-
Optimise Station Network: Upgrade existing stations to the New Mobility Visual Identity standard; close underperforming sites; open selective new stations in growth corridors.
-
Deepen B2B Relationships: Secure long-term supply contracts with mining companies, construction firms, and industrial clients.
-
Develop Green Energy Solutions: Scale the lithium battery swap programme for motorbikes; explore EV charging infrastructure.
-
Manage Currency Risk: Hedge foreign exchange exposure where possible; maintain adequate dollar liquidity.
The Bull Case (Optimistic)
-
Premium Positioning Pays Off: As the Ghanaian economy stabilises, consumers prioritise quality and fuel efficiency over the lowest price. Shell’s market share grows.
-
Non-Fuel Retail Becomes a Profit Centre: The food, convenience, and pharmacy offerings generate 20%+ of total profits, insulating the company from fuel margin volatility.
-
B2B Contracts Secure Volume: Long-term agreements with mining companies and industrial clients provide predictable revenue.
-
Green Energy First-Mover Advantage: Shell becomes the go-to brand for EV charging and battery-swapping infrastructure, capturing the transition market.
-
Market Share Stabilises: Vivo Energy holds third place with 7-8% share, ahead of TotalEnergies and Zen Petroleum, while GOIL and Star Oil fight for the top spot.
The Bear Case (Pessimistic)
-
Price War Intensifies: GOIL and Star Oil continue aggressive discounting. Vivo Energy loses price-sensitive customers. Market share falls below 6%.
-
Currency Crisis Deepens: The cedi depreciates sharply. Import costs spike. Vivo Energy must raise prices, losing customers to cheaper competitors.
-
Non-Fuel Retail Growth Stalls: The 9% growth rate was a post-COVID recovery. Growth slows to 2-3%. The retail strategy fails to differentiate.
-
Lubricants Decline Continues: The 3% volume decline and 13% gross profit drop in lubricants worsen as cheaper alternatives gain market share.
-
Brand Licence Audit Scores Drop: Maintaining the 94% standard across 244 stations becomes difficult. The Shell brand licence is reviewed.
The Verdict
Vivo Energy Ghana PLC is not a company in crisis. It is a solid, third-place player in a highly competitive market—a position that many of the nearly 200 registered OMCs would envy. The company has a globally respected brand, a diversified revenue base (fuel + non-fuel retail), a modernising station network, and a new Managing Director with decades of African experience.
The 2023 results demonstrate the model‘s strength: 244 stations, 11.4% market share, 9% non-fuel retail growth, and a 94% brand audit score. The 2025–2026 period has brought challenges: market share erosion to 6.98% , intense price competition between GOIL and Star Oil , and the arrival of a new CEO during a period of flux .
The company‘s strategic response is appropriate. Instead of joining a price war it cannot win, Vivo Energy is doubling down on differentiation: modern stations, multi-brand food courts, convenience retail, and innovative services like pharmacies and battery swaps. The Shell Michel Camp station is the template.
For the Ghanaian consumer who values quality, fuel efficiency, and a modern service experience, Shell remains the preferred brand. For the commercial fleet operator, the fuel economy benefits of Shell FuelSave justify a premium price. For the investor, Vivo Energy Ghana offers exposure to a resilient, brand-protected business.
Vivo Energy Ghana is not trying to be the largest OMC in Ghana—GOIL holds that crown with 400+ stations. It is trying to be the most trusted, the most modern, and the most profitable. With a 244-station network, a 6.98% market share, and a century-old brand legacy, it remains a formidable competitor.
The next three years will determine whether the premium strategy can hold its ground against aggressive local pricing—or whether the Shell brand will need to adapt to a new, more price-sensitive Ghanaian market.
Last Updated on June 3, 2026 by Samuel Kwame Boadu
Disclaimer: Some content on Accra Street Journal may be aggregated, summarized, or edited from third-party sources for informational purposes. Images and media are used under fair use or royalty-free licenses. Accra Street Journal is a subsidiary of SamBoad Publishing Hub under SamBoad Business Group Ltd, registered in Ghana since 2014.
For concerns or inquiries, please visit our Privacy Policy or Contact Page.

Samuel Kwame Boadu is a Ghanaian media entrepreneur and storyteller with a passion for amplifying urban voices and uncovering everyday truths. He is the Editor-in-Chief and Founder of Accra Street Journal, a dynamic digital platform dedicated to capturing the pulse of Ghana’s capital—its people, culture, challenges, business, sports and innovations.