







A 2026 Intelligence Brief from Accra Street Journal
Executive Introduction
Ghana’s energy sector is undergoing a fundamental transformation. The old model — centralised generation, state-dominated distribution, and fossil-fuel primacy — is being replaced by a more complex, competitive, and capital-intensive ecosystem. From the upstream oil and gas fields of the Tano Basin to the solar installations powering off-grid communities, from the IPO-bound downstream marketers to the independent power producers racing to expand capacity, the value chain has never been more dynamic — or more demanding of investor attention.

This report presents a comprehensive mapping of the most influential companies across Ghana’s energy value chain. We analyse the upstream oil and gas players (ENI, Kosmos, GNPC), the power generation giants (AKSA, Sunon Asogli, Karpowership), the transmission and distribution backbones (GRIDCo, ECG, NEDCo), the downstream marketing leaders (GOIL, Star Oil, ZEN Petroleum, Vivo Energy), and the emerging renewables sector (PEG Africa, Bui Power Authority, Sunon Asogli’s wind expansion).
📢 GET A DETAILED ARTICLES + JOBS
Join ASJ's WhatsApp Channel and never miss a post or opportunity.

The sector faces significant headwinds: a projected reserve margin decline through 2029 , tariff pressures, distribution losses at ECG, and the perennial challenge of attracting capital for infrastructure expansion . But the tailwinds are equally powerful: the government’s 24-Hour Economy Programme is driving round-the-clock fuel distribution , independent power producers are adding wind and solar capacity , and downstream companies are accessing public capital markets via the Ghana Stock Exchange .
For investors, policymakers, and industry participants, understanding who holds which position in the value chain is not merely informative — it is essential for navigating Ghana’s energy future.

Part 1: Upstream Oil & Gas — The Extraction Engine
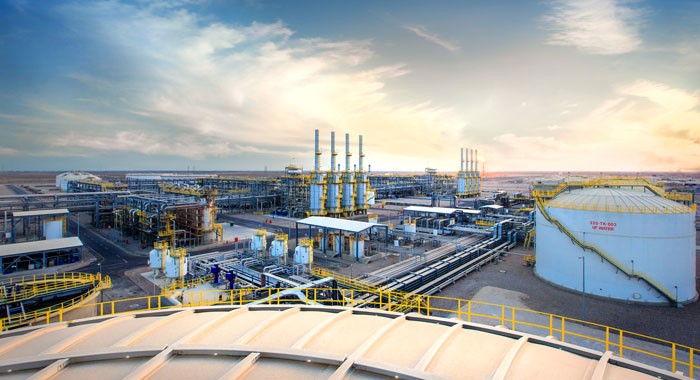
The upstream segment remains the most capital-intensive and geopolitically significant component of Ghana’s energy value chain. Foreign majors and their local partners dominate this space, extracting crude oil and natural gas from offshore fields that underpin both export revenues and domestic power generation.
The Dominant Players
| Company | Key Asset | Role | |
|---|---|---|---|
| ENI Ghana | Sankofa Gye Nyame field (OCTP) | Non-operating partner (Vitol) | Operator |
| Kosmos Energy | Jubilee Field, TEN fields | Key stakeholder | |
| Tullow Oil | Jubilee Field (operator) | Production leadership | |
| GNPC | Equity stakes in all major fields | State participation; policy direction |
ENI Ghana remains the operator of the Offshore Cape Three Points (OCTP) integrated oil and gas project, which supplies natural gas to Ghana’s power sector. Vitol Upstream Ghana Limited and Vitol Upstream Tano Limited are listed as key clients of leading energy law firms, indicating continued foreign interest in Ghana’s upstream regulatory environment .
Kosmos Energy and Tullow Oil are the primary private-sector drivers of the Jubilee Field — Ghana’s most prolific oil asset. The TEN fields (Tweneboa, Enyenra, Ntomme) add further production capacity.
The Ghana National Petroleum Corporation (GNPC) holds carried and participating interests in all major fields, managing the state’s stake while also pursuing exploration and development activities. GNPC also sits at the table for policy discussions, as demonstrated by its representation at international investor forums .
The Gas Supply Chain
Natural gas from the ENI-operated Sankofa field is processed at the Atuabo Gas Processing Plant (operated by Ghana National Gas Company), then transported via pipeline to thermal power plants — primarily Aboadze and Kpone . This gas-to-power linkage is the single most important interface between upstream extraction and downstream electricity generation.
| Plant | Gas Source | Installed Capacity |
|---|---|---|
| Aboadze Thermal Complex | West African Gas Pipeline (WAGP) | ~550 MW |
| Kpone Power Plant | WAGP | 220 MW |
Ghana National Gas Company reported $39 million in revenue, making it the second-largest energy company by revenue in Zoominfo’s 2026 ranking .
Investor Climate
The Ghana Investment Promotion Centre (GIPC) actively courts foreign investment in upstream oil and gas, citing political stability, economic reforms, and a new Investor Grievance Mechanism designed to resolve disputes before they escalate . The message to global energy companies is unambiguous: Ghana is open for business.
Part 2: Power Generation — The Thermal and Renewable Mix
Ghana’s power generation fleet comprises a mix of hydro (Akosombo, Kpong, Bui), thermal (Aboadze, Kpone, Tema, Asogli, AKSA), and emerging renewables (solar, wind). Independent Power Producers (IPPs) dominate the thermal segment, while the Volta River Authority (VRA) manages hydro assets.
Thermal Power Dominance
| Power Plant | Operator/Investor | Projected Capacity Trend (2025-2030) | Key Detail |
|---|---|---|---|
| Karpowership Ghana | Karpowership | 2,843 GWh (2025) → 0 (2030) | Floating storage and regasification unit |
| Sunon Asogli I | Sunon Asogli | 1,077 GWh (2025-2028) → 720 GWh (2029) → 0 (2030) | 200 MW wind farm expansion planned |
| AKSA Enerji (Kumasi) | AKSA Energy | 0 (2025) → 2,449 GWh (2030) | Dramatic ramp-up; becoming a major player |
| Cenit Energy (Kumasi) | Cenit Power | 0 (2025-2028) → 2,584 GWh (2030) | New entrant with significant future capacity |
*Source: PURC Projected Reserve Margin Data (2025-2029)*

Karpowership Ghana Company Limited has been a controversial but reliable contributor to Ghana’s grid, supplying 2,843 GWh in 2025. However, PURC projections show its contribution declining to zero by 2030 — a planned phase-out as domestic gas-fired plants come online .
Sunon Asogli has been a consistent thermal generator, producing 1,077 GWh annually through 2028. Beyond 2028, its contribution declines to 720 GWh in 2029 before reaching zero in 2030. However, this may reflect contract restructuring rather than reduced capacity, as the company is simultaneously expanding into renewables. On February 17, 2026, Sunon Asogli announced plans to add a 200 MW wind farm in the Ada West district, alongside an 850 MW third phase of its thermal project and a proposed plant in Burkina Faso .
AKSA Energy’s Kumasi plant is the most dramatic growth story in the PURC projections. From zero generation in 2025, the plant ramps up to 1,562 GWh in 2027, reaching 2,449 GWh by 2030. Cenit Energy follows a similar trajectory, with its Kumasi plant beginning operations in 2029 and reaching 2,584 GWh in 2030 .
The Reserve Margin Challenge
PURC’s projections point to a tightening reserve margin over the next five years. As Karpowership phases out, new capacity from AKSA and Cenit must come online on schedule to avoid supply gaps. Delays in any of these projects would strain the grid and risk load-shedding — a spectre that Ghana’s power sector has worked hard to banish.
Renewable Energy Expansion
The government’s dual focus on traditional fossil fuels and green technologies is evident . Sunon Asogli’s 200 MW Ada West wind farm is the largest single renewable announcement of 2026 . The Bui Power Authority operates a floating solar installation on the Bui Dam reservoir, representing innovative hybrid hydro-solar technology.
Solar energy companies are increasingly active in Ghana’s market. According to Mordor Intelligence’s 2024 analysis, key players include:
| Company | Focus Area |
|---|---|
| PEG Africa | Off-grid solar solutions |
| Trina Solar Ltd | Solar module supply, large-scale projects |
| JinkoSolar Holding Co Ltd | Solar module supply chain |
| Redavia Solar Power | Rental solar systems for off-grid communities |
| Daystar Power Ghana | Commercial and industrial solar |
Source: Mordor Intelligence Ghana Solar Energy Market Report
PEG Africa is ranked among the top energy companies by revenue, with $33.7 million and 501-1,000 employees .
Hydro Power
The Volta River Authority (VRA) manages the Akosombo and Kpong hydroelectric dams — the backbone of Ghana’s grid for decades. While hydro provides baseload stability, its output fluctuates with rainfall patterns, making thermal and renewables essential for grid reliability.
Part 3: Transmission & Distribution — The Grid Backbone
The transmission and distribution segment connects generation to consumption. It is also the most financially distressed part of the value chain, with distribution losses, collection inefficiencies, and tariff shortfalls creating persistent liquidity challenges.
Transmission: GRIDCo
Ghana Grid Company Limited (GRIDCo) operates the national transmission network, ensuring that power generated at scattered plants reaches distribution hubs across the country. With $57.5 million in revenue, GRIDCo is the highest-ranked energy company in Zoominfo’s 2026 list, employing 501-1,000 people .

GRIDCo’s role is technically essential but politically sensitive. Transmission constraints have historically led to load-shedding in specific regions, and the company is under constant pressure to expand and maintain infrastructure in the face of funding limitations.
Distribution: ECG and NEDCo
| Distributor | Service Territory | Key Challenge |
|---|---|---|
| Electricity Company of Ghana (ECG) | Southern Ghana (including Accra, Tema, Cape Coast, Takoradi, Kumasi) | Distribution losses; collection inefficiencies; tariff shortfalls |
| Northern Electricity Distribution Company (NEDCo) | Northern Ghana | Lower consumption density; collection challenges |
ECG is the primary focus of reform efforts, including the proposed Private Sector Participation (PSP) arrangement that has been the subject of extensive policy debate. The IMF has explicitly called for progress on ECG privatisation as a condition for continued programme support, though Ghana has now exited the ECF and transitioned to a Policy Coordination Instrument (PCI).
Key Legal Clients
Energy sector law firms serve a range of distribution-adjacent clients. WTS Nobisfields, for example, counts Vana Energy Ltd, Cenpower Operations and Services Ltd, and Vitol Ghana Services Ltd among its key clients — indicating ongoing legal and regulatory activity in the sector .
Part 4: Downstream — Oil Marketing Companies (OMCs)
The downstream segment is the most competitive and commercially dynamic part of Ghana’s energy value chain. Over 180 Oil Marketing Companies operate more than 5,000 filling stations nationwide . The market share battle at the top has intensified dramatically.
Market Share Rankings (January-February 2026)
| Rank | Company | Total Sales Volume (Litres) | Market Share | Retail Stations |
|---|---|---|---|---|
| 1 | GOIL PLC | 158,173,164 | 11.93% | 400+ |
| 2 | Star Oil Ghana | 155,737,710 | 11.74% | 250+ |
| 3 | Vivo Energy Ghana (Shell) | 92,546,100 | 6.98% | 250+ |
| 4 | Zen Petroleum | 70,259,000 | 5.30% | 60+ |
| 5 | TotalEnergies | 53,749,130 | 4.13% | 250+ |
*Source: National Petroleum Authority (NPA) data, January-February 2026*
GOIL PLC: The Market Leader Returns
GOIL reclaimed its position as Ghana’s leading OMC in early 2026 after losing the top spot to Star Oil in previous years. GOIL sold 158.2 million litres across petrol, diesel, LPG, and other products, capturing an 11.93 per cent market share. The company operates over 400 retail stations — the largest network in the country .
GOIL’s resurgence reflects strategic investments in supply chain efficiency, retail network expansion, and brand positioning. As a listed company on the Ghana Stock Exchange, GOIL also benefits from access to public capital markets.
Star Oil Ghana: The Challenger
Star Oil recorded the highest sales volumes for both petrol (94 million litres) and diesel (59.9 million litres) during the two-month period. Its total sales volume of 155.7 million litres gave it an 11.74 per cent market share — a razor-thin margin behind GOIL .
Star Oil has over 250 retail stations and has been the primary challenger to GOIL’s historical dominance. The company’s strong position in petrol and diesel suggests a focused strategy on high-volume products.
Vivo Energy Ghana (Shell)
Vivo Energy, the distributor of Shell-branded products, ranked third with 92.5 million litres sold and a 6.98 per cent market share. The Shell brand retains significant consumer loyalty, though Vivo has lost ground to indigenous OMCs in recent years .
ZEN Petroleum: The Rising Star
Zen Petroleum sold 70.3 million litres, capturing a 5.30 per cent market share with just over 60 retail stations. The company’s relatively small retail footprint but strong sales volume suggests significant commercial and industrial sales — notably its dominant position in the mining sector, where it supplies approximately 49 per cent of fuel consumed by major mining companies .
Zen’s IPO on the Ghana Stock Exchange (March 2026) raised GH¢640 million and marked one of the largest listings by an indigenous downstream company in recent years .
TotalEnergies
TotalEnergies sold 53.7 million litres, capturing a 4.13 per cent market share. The global brand has a significant retail presence (over 250 stations) but has lost market share to more aggressive indigenous competitors .
Retail Network Landscape
| Company | Number of Retail Stations | Market Position |
|---|---|---|
| GOIL | 400+ | Largest network |
| Star Oil | 250+ | Broad coverage |
| Vivo Energy (Shell) | 250+ | Strong brand loyalty |
| TotalEnergies | 250+ | Competitive |
| Zen Petroleum | 60+ | Smaller network but high commercial sales |
GOIL’s 400+ station network gives it a distribution advantage that competitors cannot easily replicate .
BOSTenergies: The 24-Hour Distribution Pilot
BOST Energies Limited — responsible for the safe and efficient movement of petroleum products from coastal supply points to inland markets — has been selected to pilot the government’s 24-Hour Economy Programme in the petroleum downstream sector .
The pilot focuses on the Accra Plains Depot (APD)-Kumasi corridor, connecting the company’s Tema depot to its terminal in Kumasi and serving the Ashanti, Bono, Bono East, Ahafo, and Western North regions.
The Managing Director stated: “I believe that no nation can successfully operate a 24-hour economy without a 24-hour energy backbone” .
Key developments at BOSTenergies include:
-
Workforce increased by more than 20 per cent over the past year
-
The pilot is intended to demonstrate that continuous fuel distribution is both operationally achievable and commercially sustainable
-
Indirect employment opportunities expected in haulage, logistics, maintenance, catering, engineering support, and security services
Part 5: Logistics and Infrastructure — The Fuel Supply Chain
Beyond the OMCs, a network of logistics companies, storage facilities, and transport providers ensures that fuel reaches retail stations and industrial customers.
Bulk Oil Storage and Transportation (BOST)
BOST operates the national fuel storage and distribution infrastructure, including the Accra Plains Depot (APD) and the Kumasi terminal. The company’s 24-hour distribution pilot along the APD-Kumasi corridor is the most significant operational development of 2026 .
International Trading Partners
ZEN Petroleum’s supply arrangements with BP, Repsol, and Trafigura indicate that Ghana’s downstream companies are integrated into global petroleum trading networks . These relationships provide access to competitive pricing and supply security.
Marine Fuel (Bunkering)
Zen Petroleum maintains a significant bunkering business, supplying marine gasoil to vessels at the ports of Tema and Takoradi . This segment serves international shipping and contributes to Ghana’s position as a regional maritime hub.
Storage Infrastructure
| Facility | Operator | Capacity |
|---|---|---|
| New Takoradi Gasoil Depot | ZEN Petroleum | 30,000 metric tonnes |
| Accra Plains Depot (APD) | BOST | Strategic national storage |
| Kumasi Terminal | BOST | Regional distribution hub |
ZEN’s 30,000-metric-tonne depot in New Takoradi represents significant private-sector investment in storage infrastructure .
The 24-Hour Economy Opportunity
The government’s 24-Hour Economy Programme presents a significant opportunity for energy logistics companies. Continuous fuel distribution would eliminate the gap between daytime-only loading schedules and round-the-clock fuel demand, enabling the entire value chain — from import receiving facilities to filling stations — to operate continuously .
Part 6: Renewable Energy — The New Frontier
Ghana’s renewable energy sector is attracting investment across solar, wind, and hybrid systems. The dual policy focus on traditional and green technologies creates opportunities across the value chain.
Solar Energy Leaders
Mordor Intelligence’s analysis identifies the following key players in Ghana’s solar market :
| Company | Primary Activity | Target Market |
|---|---|---|
| PEG Africa | Off-grid solar solutions | Residential, commercial |
| Trina Solar Ltd | Solar module supply; large-scale projects | Utility, commercial |
| JinkoSolar Holding Co Ltd | Solar module supply chain | Wholesale, distribution |
| Redavia Solar Power | Rental solar systems; off-grid communities | Rural, commercial |
| Daystar Power Ghana | Commercial and industrial solar installations | Business, industrial |
| Bui Power Authority | Floating solar (Bui Dam); hydro-solar hybrid | Utility |
| SunPower Innovations | Residential and commercial solar installations | Residential, commercial |
PEG Africa is among Ghana’s top energy companies by revenue ($33.7 million), with 501-1,000 employees .
Wind Power Expansion
Sunon Asogli’s 200 MW Ada West wind farm is the most significant renewable energy announcement of 2026. The project is at an advanced stage, and the company has acquired four sites for solar power development with an initial target of 200 MW .
The Regional Export Ambition
Sunon Asogli’s expansion plans extend beyond Ghana’s borders. The company intends to begin establishing a power plant in Burkina Faso in March 2026 and will start supplying power to that market . This aligns with the broader strategy of positioning Ghana as a major electricity exporter within sub-Saharan Africa.
Part 7: Capital Markets and IPOs — Financing the Energy Transition
The Ghana Stock Exchange (GSE) is playing an increasingly important role in financing the energy sector’s expansion.
ZEN Petroleum IPO (March 2026)
ZEN Petroleum Holdings PLC raised GH¢640 million through an initial public offering, issuing 128 million shares at GH¢5.00 each, representing 20 per cent of the company’s enlarged share capital .
Investor commitments:
-
Bora Capital Advisors Pension Funds: 75.33 per cent
-
Temple Impact VC Fund
-
Stanbic Investment Management Services
The offer was fully subscribed before the public closing date — an indication of strong institutional appetite for downstream energy assets .
Financial projections (from prospectus):
| Year | Projected Revenue (GH¢) | Projected PAT (GH¢) |
|---|---|---|
| 2026 | 8.41 billion | 375 million |
| 2027 | — | — |
| 2030 | 10.98 billion | 469 million |
Source: PricewaterhouseCoopers (reporting accountant)
ZEN’s integrated supply chain includes a 30,000-metric-tonne gasoil depot in New Takoradi, a fleet of 93 bulk road vehicles, and exclusive supply arrangements with international traders including BP, Repsol, and Trafigura. Over more than 15 years of operations, the company has recorded no fatalities — a notable safety achievement .
Market Implications
ZEN’s successful listing suggests that the GSE’s IPO market is recovering after the slowdown linked to the Domestic Debt Exchange Programme (DDEP). If other energy companies follow, the GSE could become a meaningful source of expansion capital for the sector.
GOIL (Already Listed)
GOIL has been listed on the GSE for years and serves as a benchmark for downstream valuation.
Future IPO Candidates
The following energy companies could potentially list on the GSE:
-
Star Oil Ghana — significant market share, extensive retail network
-
Vivo Energy Ghana — brand strength, international backing
-
BOSTenergies — state-owned but potentially a candidate for privatisation/listing
-
PEG Africa — fast-growing renewable energy company
Part 8: The Regulatory and Policy Landscape
Energy companies operate within a complex regulatory environment shaped by multiple institutions.
Key Regulators
| Institution | Mandate |
|---|---|
| Petroleum Commission | Upstream oil and gas regulation, licensing, monitoring |
| National Petroleum Authority (NPA) | Downstream petroleum regulation, pricing, quality control |
| Energy Commission | Electricity sector regulation, licensing, standards |
| Public Utilities Regulatory Commission (PURC) | Tariff setting for electricity and water |
| Ghana Investment Promotion Centre (GIPC) | Investment promotion, investor protection |
The GIPC’s CEO, Mr. Simon Madjie, recently extended an invitation to the global energy community to invest in Ghana, highlighting economic reforms, political stability, and a new Investor Grievance Mechanism designed to resolve business issues quickly before they escalate .
The IMF and Energy Reforms
Ghana has exited the Extended Credit Facility (ECF) programme and transitioned to a Policy Coordination Instrument (PCI). While the immediate crisis has passed, the IMF maintains pressure on energy sector reforms — particularly ECG’s operational and financial performance.
The 24-Hour Economy Programme
The government’s flagship economic initiative includes a downstream petroleum pilot led by BOSTenergies. The programme aims to extend productive hours across manufacturing, services, and logistics — with the petroleum sector serving as a backbone for 24-hour operations .
Conclusion: Ghana’s Energy Future
Ghana’s energy value chain is more dynamic, competitive, and investment-ready than at any point in its history. Upstream producers are extracting oil and gas under stable regulatory frameworks. Independent power producers are expanding capacity, with AKSA and Cenit ramping up dramatically while Sunon Asogli invests in wind. The downstream sector is fiercely competitive, with GOIL and Star Oil battling for market leadership and ZEN Petroleum accessing public capital markets.
Renewable energy is no longer peripheral. PEG Africa, Bui Power Authority, and Sunon Asogli’s wind expansion are proof that green technologies are moving from pilot to scale. The government’s dual focus on fossil fuels and renewables is not a contradiction — it is a pragmatic recognition that Ghana needs both base-load thermal power and distributed renewable generation to meet rising demand.
The sector’s challenges are equally real. PURC’s projections point to a tightening reserve margin ; ECG’s distribution losses remain a structural drag; and attracting capital for infrastructure expansion requires sustained investor confidence .
For companies positioned across the value chain — from upstream extraction to downstream distribution, from thermal generation to renewable expansion — Ghana offers a stable, growing, and increasingly sophisticated market. The energy transition is not a distant prospect. It is happening now. And Ghana’s most influential energy companies are building it.
Quick Reference: Ghana Energy 500 — The Most Influential Companies
| Segment | Company | Key Metric |
|---|---|---|
| Upstream | ENI Ghana | Operator, Sankofa field |
| Upstream | Kosmos Energy | Jubilee & TEN fields |
| Upstream | GNPC | State participation |
| Gas | Ghana National Gas Company | $39M revenue |
| Transmission | GRIDCo | $57.5M revenue |
| Generation (Thermal) | AKSA Enerji | 2,449 GWh by 2030 |
| Generation (Thermal) | Sunon Asogli | 200 MW wind expansion |
| Generation (Solar) | PEG Africa | $33.7M revenue |
| Generation (Hydro) | VRA | Akosombo, Kpong dams |
| Downstream (OMC) | GOIL PLC | 11.93% market share |
| Downstream (OMC) | Star Oil Ghana | 11.74% market share |
| Downstream (OMC) | ZEN Petroleum | GH¢640M IPO |
| Downstream (OMC) | Vivo Energy (Shell) | 6.98% market share |
| Logistics | BOSTenergies | 24-hour distribution pilot |
| Distribution | ECG | Southern Ghana |
| Distribution | NEDCo | Northern Ghana |
Source: Accra Street Journal
Last Updated on June 5, 2026 by Samuel Kwame Boadu
Disclaimer: Some content on Accra Street Journal may be aggregated, summarized, or edited from third-party sources for informational purposes. Images and media are used under fair use or royalty-free licenses. Accra Street Journal is a subsidiary of SamBoad Publishing Hub under SamBoad Business Group Ltd, registered in Ghana since 2014.
For concerns or inquiries, please visit our Privacy Policy or Contact Page.

Samuel Kwame Boadu is a Ghanaian media entrepreneur and storyteller with a passion for amplifying urban voices and uncovering everyday truths. He is the Editor-in-Chief and Founder of Accra Street Journal, a dynamic digital platform dedicated to capturing the pulse of Ghana’s capital—its people, culture, challenges, business, sports and innovations.