The New Reality for Ghana’s Young Workforce
For Ghana’s growing class of young professionals, turning 30 is more than a birthday milestone. It’s a financial wake-up call. The choices made in the first decade of one’s career often determine long-term financial security.

But here’s the hard truth: while Ghana’s youth unemployment rate hovers around 14% (World Bank, 2024), those who are employed—whether in corporate roles, tech startups, or creative industries—rarely prioritize insurance. Most only think about it when crisis strikes: a medical emergency, a car accident, or the sudden death of a family breadwinner.
Yet insurance is not just a safety net. For young professionals, it’s a tool for wealth preservation, stability, and peace of mind. Here are Accra Street Journal’s five policies every Ghanaian professional should consider before 30.
📢 GET A DETAILED ARTICLES + JOBS
Join ASJ's WhatsApp Channel and never miss a post or opportunity.
1. Health Insurance – Beyond NHIS
The National Health Insurance Scheme (NHIS) is a valuable start, but it doesn’t cover everything. Dialysis, cancer treatments, and advanced diagnostics are excluded.
Private health insurance—offered by firms such as Enterprise Life, Hollard Ghana, and StarLife Assurance—fills these gaps. Premiums can start as low as GHS 70 per month, depending on coverage.
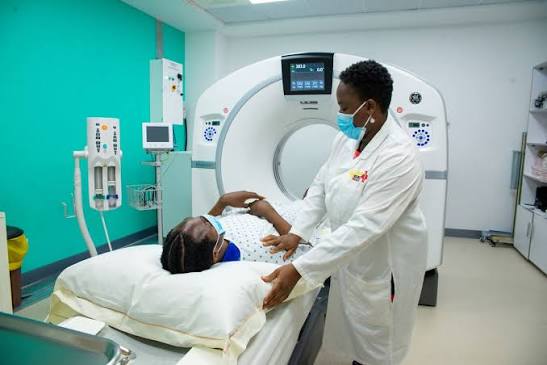
👉 Why it matters: A single MRI scan can cost over GHS 1,500 out-of-pocket. Private coverage ensures you don’t burn through savings during a health crisis.
2. Life Insurance – Protecting Family and Legacy
Life insurance is often misunderstood as a product only for older people. In fact, the earlier you start, the cheaper the premiums.
Policies such as term life or whole life insurance ensure that if tragedy strikes, your dependents (spouse, children, or even parents) are not financially stranded.
👉 Why it matters: With Ghana’s cost of living steadily rising—especially in housing and education—life insurance protects your family’s stability if you’re no longer around.
3. Income Protection (Disability Insurance)
Few professionals consider the possibility of losing income due to illness or disability. Yet, with Ghana’s rising rates of lifestyle diseases such as hypertension and diabetes, this is no longer far-fetched.
Income protection insurance replaces part of your salary if you are unable to work for medical reasons.
👉 Why it matters: For a 28-year-old corporate worker earning GHS 5,000/month, losing that income due to illness could wipe out savings in less than six months.
4. Motor Insurance – More Than a Legal Requirement
By law, every vehicle on Ghanaian roads must have insurance. But not all policies are equal. Third-party insurance covers damages to others, while comprehensive insurance protects both you and the other party.
Given the rising rate of road accidents—over 15,000 crashes recorded annually (NRSA, 2024)—comprehensive cover by Priority Insurance Company, SIC Insurance etc is the smart choice for professionals who rely on cars for work and lifestyle.
👉 Why it matters: An accident involving a Toyota Corolla could cost GHS 30,000+ in repairs. Comprehensive insurance cushions such shocks.
5. Investment-Linked Insurance (Wealth-Building Policies)
Insurance doesn’t have to be just about risk. Some products combine protection with investment. Unit-linked insurance plans allow you to grow wealth while staying insured.
Companies like Databank and Prudential Life offer hybrid products that channel part of your premium into mutual funds.
👉 Why it matters: By age 30, even modest contributions of GHS 300/month could grow into a sizeable investment base for housing or entrepreneurship by age 40.
The Bigger Picture: Why Insurance Before 30 Matters
Financial experts argue that buying insurance young has three key advantages:
-
Lower premiums – The younger and healthier you are, the cheaper your policies.
-
Longer coverage – Early enrollment means a longer safety net.
-
Financial discipline – Committing to insurance instills savings habits.
As Samuel Kwame Boadu, Editor-In-Chief at Accra Street Journal, puts it:
“Insurance is not a luxury. For young professionals, it’s the foundation of financial independence.”
FAQs
1. Is NHIS enough for young professionals in Ghana?
No. NHIS has coverage gaps, especially in cancer treatments, dialysis, and advanced diagnostics. Private health insurance is recommended to fill those gaps.
2. What’s the cheapest insurance to start with before 30?
Health insurance and term life insurance typically come with the lowest premiums, making them the most affordable entry point.
3. Can I combine insurance with investment in Ghana?
Yes. Some providers offer investment-linked insurance products that allow you to build wealth while maintaining coverage.
4. Do freelancers or self-employed professionals need insurance?
Absolutely. Since freelancers and entrepreneurs don’t get employer-provided benefits, insurance acts as their main financial safety net.
5. What happens if I wait until after 30 to buy insurance?
Premiums are higher, and you may face exclusions if you develop health conditions before applying. Starting early locks in affordability and broader coverage.
Source: Accra Street Journal
Last Updated on September 9, 2025 by Samuel Kwame Boadu
Disclaimer: Some content on Accra Street Journal may be aggregated, summarized, or edited from third-party sources for informational purposes. Images and media are used under fair use or royalty-free licenses. Accra Street Journal is a subsidiary of SamBoad Publishing Hub under SamBoad Business Group Ltd, registered in Ghana since 2014.
For concerns or inquiries, please visit our Privacy Policy or Contact Page.

Samuel Kwame Boadu is a Ghanaian media entrepreneur and storyteller with a passion for amplifying urban voices and uncovering everyday truths. He is the Editor-in-Chief and Founder of Accra Street Journal, a dynamic digital platform dedicated to capturing the pulse of Ghana’s capital—its people, culture, challenges, business, sports and innovations.