








With GHS 223 million in claims paid—more than any other non-life insurer in the country—this mid-tier pan-African player has turned the insurance logic on its head: compete on reliability, not price; prioritise policyholders, not market share. Now, with a new Managing Director at the helm, it is betting that trust is the only sustainable competitive advantage.

Executive Introduction
In Ghana‘s insurance industry, there is a metric more important than premium income, more revealing than market share, and more honest than any marketing campaign: claims paid. When a policyholder‘s car is wrecked, their shop burns down, or their cargo is lost at sea, the only question that matters is: does the insurer pay?
By that definitive measure, Activa International Insurance Ghana is the undisputed leader. According to the 2024 National Insurance Commission (NIC) report, Activa paid GHS 223 million in non-life claims—more than Star Assurance (GHS 217 million), more than Enterprise Insurance (GHS 201 million), and more than any other insurer in the country .
📢 GET A DETAILED ARTICLES + JOBS
Join ASJ's WhatsApp Channel and never miss a post or opportunity.
This is not a one-off anomaly. It reflects a deliberate strategic choice: Activa has prioritised policyholder protection over profit retention, building a reputation for reliability that transcends its size. Remarkably, Activa is only the 7th largest non-life insurer by premium income . It punches significantly above its weight, demonstrating that claims-paying capacity is not solely a function of premium volume but of capital management, underwriting discipline, and reinsurance strategy.
For corporate risk managers, insurance brokers, and policyholders across Ghana, Activa represents a compelling proposition: a pan-African backed insurer (part of Mauritius-based Activa Finance) that has cracked the code on reaching the mass market through digital channels, targeted SME products, and a genuine commitment to women‘s economic empowerment .
Now, Activa enters a new era. Effective February 2026, Salifu Abubakari—a KNUST alumnus with over 18 years of experience, professional qualifications including the prestigious CPCU designation, and a parallel role as President of the CPCU Society West Africa—has assumed the position of Acting Managing Director . His mandate: sustain the claims leadership, deepen digital transformation, and expand Activa‘s reach into the underserved corners of Ghana‘s economy.
This profile examines Activa‘s origin story, its remarkable claims performance, its strategic emphasis on inclusion (including the Activ‘Lady programme for women entrepreneurs), its A+ rating from GCR, the leadership transition to Abubakari, and the critical question: can a mid-tier insurer with a lean staff of 55 maintain its claims supremacy against giants with far deeper pockets?
Company Overview
The Genesis: From Global Alliance to a Pan-African Powerhouse
Activa International Insurance Ghana was originally incorporated as Global Alliance Insurance in 2005 . For the first four years of its existence, it operated as a local Ghanaian insurer, building a foundation in the non-life market.
The pivotal moment arrived in 2009 when the company was acquired by Activa Assurances, a pan-African insurance group . This acquisition transformed Activa Ghana from a local player into a subsidiary of a multinational insurance network, providing access to international underwriting expertise, reinsurance capacity, and capital.
Today, Activa Ghana is part of Activa Finance, a Mauritius-based holding company that oversees the group‘s insurance and financial services operations across Africa . This ownership structure provides Activa Ghana with:
-
International capital access: The ability to draw on group resources for liquidity and reinsurance
-
Cross-border expertise: Access to underwriting and risk management practices from multiple African markets
-
Governance standards: Alignment with internationally recognised corporate governance frameworks
-
Reinsurance relationships: Leverage of the group‘s relationships with global reinsurers
Unlike some competitors that are tied to a single local family or the Ghanaian state, Activa has the backing of a diversified international group. Unlike others that are subsidiaries of South African or Nigerian giants, Activa‘s parentage is specifically pan-African and Mauritius-based, offering a different strategic orientation.
Ownership and Group Structure
| Level | Entity | Role |
|---|---|---|
| 1 | Activa Finance (Mauritius) | Ultimate holding company |
| 2 | Activa Assurances | Pan-African insurance group |
| 3 | Activa International Insurance Ghana | Ghana operating subsidiary |
This structure is not merely administrative; it is strategic. Activa Ghana benefits from the group‘s presence across multiple African markets, enabling it to underwrite risks that span borders and to offer multinational clients consistent coverage across jurisdictions.
Leadership: Salifu Abubakari Takes the Helm
Salifu Abubakari – Acting Managing Director (effective February 2, 2026)
The most consequential development for Activa in 2026 is the appointment of Salifu Abubakari as Acting Managing Director .
Academic Credentials:
-
Master of Science (MSc) in Business Continuity and Insurance from Kwame Nkrumah University of Science and Technology (KNUST)
-
Bachelor of Commerce in Marketing from the University of Cape Coast
Professional Qualifications:
-
Chartered Property Casualty Underwriter (CPCU) – a prestigious US designation that is the gold standard in property and casualty insurance
-
Chartered Insurer (Ghana) – local professional certification
-
Associate in Risk Management (ARM) from The Institutes (USA)
-
Advanced Diploma in Sales and Marketing Management (UK)
Industry Experience:
Abubakari brings over 18 years of progressive experience in insurance, risk management, underwriting, and business development. He has held leadership and strategic roles with:
-
KEK Group
-
Regency Alliance Insurance
Leadership in Professional Bodies:
-
President of the CPCU Society West Africa – a respected professional body dedicated to advancing excellence and ethical standards in property and casualty insurance
-
Vice Chair, CPCU Global Virtual Committee
-
Committee Member, Ghana Insurers Association (GIA) External Liaison and Public Relations Committee
-
Member, Insurance Awareness Coordinating Group Working Committee
Academic Contributions:
Abubakari serves as a lecturer at the Ghana Insurance College and at KNUST, where he teaches at the Master‘s degree level . He previously chaired the Priority Insurance Ltd‘s Education Committee. His academic engagement has helped shape emerging insurance professionals and strengthen technical standards within the industry.
The Strategic Importance of the Appointment
The appointment of Abubakari is significant for several reasons:
-
Technical depth: Unlike some CEOs who rise through sales or finance, Abubakari brings deep underwriting and risk management expertise, including the CPCU designation—one of the most rigorous professional certifications in global insurance .
-
Industry leadership: His role as President of CPCU West Africa positions him at the centre of professional development for the insurance sector, providing Activa with influence and visibility .
-
Academic engagement: His role as a lecturer at insurance institutions keeps him connected to emerging talent and industry research .
-
Continuity with transformation: As an internal appointment with extensive industry experience, Abubakari represents both stability and the potential for strategic evolution.
Operations and Footprint
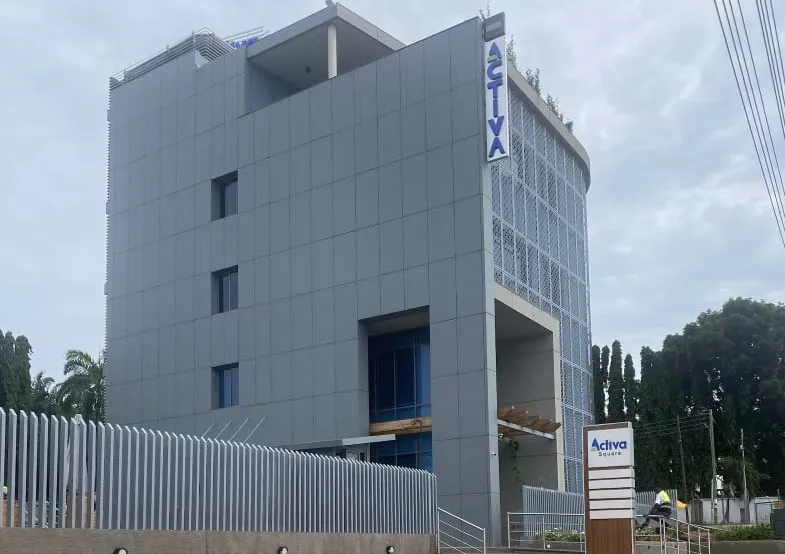
Activa International Insurance Ghana is headquartered in Accra and operates with a remarkably lean team of approximately 55 employees . This lean structure is deliberate: Activa prioritises digital distribution and strategic partnerships over a large, expensive physical footprint.
Headcount Growth:
-
Month-over-month headcount growth: 1.85%
-
Year-over-year headcount growth: 12.22%
These figures indicate measured, sustainable expansion rather than aggressive hiring.
Key Operational Metrics:
| Metric | Value |
|---|---|
| Founded | 2005 (as Global Alliance Insurance) |
| Acquired by Activa Assurances | 2009 |
| Headquarters | Accra, Ghana |
| Employees | ~55 |
| Parent | Activa Finance (Mauritius) |
| Market Position (Premium) | 7th largest non-life insurer in Ghana |
| Market Position (Claims) | #1 non-life claims payer |
| GCR Rating | A+(GH) with Stable Outlook |
Digital Channels
Activa has embraced digital transformation as a core strategic pillar. The company offers multiple digital access channels :
-
Online platform for policy purchase and management
-
Mobile access for on-the-go insurance needs
-
USSD services for feature phone users
-
MyActiva App for comprehensive digital account management
The company has also achieved ISO 27001:2022 certification in information security, enhancing trust in its digital insurance services .
The Claims Performance: GHS 223 Million and Steel
The 2024 National Insurance Commission (NIC) report is the definitive source on Ghana‘s insurance industry performance. According to the Accra Street Journal‘s analysis of this report, Activa International Insurance Ghana emerged as the highest claims-paying non-life insurer in the country .
The Top 10 Non-Life Claims Payers (2024)
| Rank | Insurer | Net Claims Paid (GHS) |
|---|---|---|
| 🥇 | Activa International Insurance | 223 million |
| 🥈 | Star Assurance | 217 million |
| 🥉 | Enterprise Insurance | 201 million |
| 4th | Hollard Insurance Ghana | 172 million |
| 5th | Vanguard Assurance | 157 million |
| 6th | Glico General Insurance | 119 million |
| 7th | SIC Insurance Company | 88 million |
| 8th | Salam Alliance Insurance | 64 million |
| 9th | Ghana Union Assurance | 50 million |
| 10th | Phoenix Insurance Company | 47 million |
Industry Context:
-
Total non-life claims paid in 2024: GHS 1.45 billion
-
Top five insurers’ share of total claims: Over 67%
What the GHS 223 Million Figure Signifies
1. Leadership by a Meaningful Margin
Activa‘s GHS 223 million in claims paid is not a narrow victory; it is a decisive lead. Activa paid:
-
GHS 6 million more than Star Assurance (GHS 217 million)
-
GHS 22 million more than Enterprise Insurance (GHS 201 million)
-
GHS 51 million more than Hollard (GHS 172 million)
-
GHS 135 million more than the state-owned SIC Insurance (GHS 88 million)
2. Punching Above Weight
Crucially, Activa is only the 7th largest non-life insurer by premium income . This means Activa is paying claims at a rate that significantly exceeds what would be expected based on its premium volume.
This discrepancy can be explained by several factors:
-
Efficient claims processing: Activa settles claims faster and more completely than competitors
-
Different risk mix: Activa may underwrite a higher proportion of high-frequency claims (e.g., motor) relative to low-frequency, high-severity claims (e.g., catastrophe property)
-
Strategic prioritisation: Activa has deliberately chosen to prioritise claims payment over profit retention
3. The “Big Three” Consolidation
Activa, Star Assurance, and Enterprise together form the top tier of claims payers, with each exceeding GHS 200 million. The close competition among these three underscores the concentrated but competitive landscape of Ghana‘s non-life insurance sector .
4. The SIC Comparison
The gap between Activa (GHS 223 million) and SIC Insurance (GHS 88 million) is stark. SIC, the state-owned insurer that once dominated the market, now pays less than half of what Activa pays—despite benefiting from a controversial SIGA directive compelling state-owned enterprises to insure with SIC. This comparison underscores how dramatically the market has shifted toward private, customer-focused insurers.
Activa‘s Response: A Strategic Commitment
Salifu Abubakari, Acting Managing Director, described the recognition as a positive signal for the insurance industry . He emphasised that claims payment is the core promise of insurance, and that prompt claims payment changes public perception and encourages uptake.
“This is not a surprise but a confirmation of a long-held strategy—to compete on reliability, not price; to prioritise policyholders, not profits; to be the insurer that Ghanaians can trust when they need protection most.”
The company has committed to:
-
Maintaining its claims leadership position
-
Expanding digital claims processing to improve speed and transparency
-
Reaching more Ghanaians with reliable coverage
Business Model: The Mass-Market General Insurer
Activa is a non-life (general) insurance company. It does not underwrite life assurance or long-term savings products; its focus is on protecting policyholders against specific, time-bound risks.
Core Product Lines
Activa‘s product portfolio spans both individual and commercial risks :
Personal Lines (Retail):
-
Motor Insurance: Comprehensive and third-party policies; includes enhanced third-party cover
-
Travel Insurance: Cover for domestic and international travel
-
Home Insurance: Protection for buildings and contents
-
Personal Accident Insurance: Cover for injury or death resulting from accidents
-
Lady Drive: A specialised motor product for women drivers
-
Activ‘Lady Programme: A gender-focused initiative supporting women entrepreneurs with tailored coverage
Commercial Lines (SME & Corporate):
-
Fire & Allied Perils: Protection for commercial properties against fire, lightning, explosion, and other specified perils
-
Marine Insurance: Cover for cargo, hull, and associated risks
-
Assets All Risks: Comprehensive coverage for business assets
-
SME Risk Solutions: Bundled products for small and medium enterprises covering fire, theft, and business interruption
-
Group Personal Accident: Cover for employee groups
The Activ‘Lady Programme: Women as a Strategic Market
One of Activa‘s most distinctive initiatives is the Activ‘Lady programme, a gender-focused insurance initiative designed to support women entrepreneurs and professionals .
Programme Features:
-
Tailored insurance products for women-owned businesses
-
Coverage addressing risks specific to women entrepreneurs (e.g., market traders, salon owners, caterers)
-
Educational and capacity-building components
Strategic Rationale:
Women constitute a significant portion of Ghana‘s informal economy—market traders, hairdressers, seamstresses, caterers, and small-scale manufacturers. These women often lack access to formal insurance because traditional products are not designed for their needs or distribution channels do not reach them.
By launching a dedicated women‘s insurance programme, Activa is:
-
Capturing an underserved market segment
-
Building brand loyalty among women who may then insure their families and businesses with Activa
-
Aligning with broader financial inclusion and gender equity goals
Credit Insurance and the Globus Network
Activa has also pushed into credit insurance—protecting lenders against borrower default. This positions the company to partner with banks, microfinance institutions, and fintech lenders, offering protection that enables these institutions to lend more confidently.
The company‘s membership in the Globus Network aims at corporate and multinational clients, providing cross-border insurance coverage across multiple African markets .
Revenue Model
As a non-life insurer, Activa generates revenue from:
-
Gross Written Premiums (GWP): The total premiums collected from policyholders before reinsurance costs. Activa is the 7th largest non-life insurer by premium income .
-
Investment Income: Insurers invest their premium float (the cash held between premium collection and claims payment) in government securities, fixed deposits, and other low-risk instruments. Activa‘s A+ rating indicates strong investment management.
-
Reinsurance Commissions: Activa cedes a portion of its risk to reinsurers (global and regional) in exchange for reinsurance premiums. When claims are lower than expected, Activa may receive commission income from reinsurers.
-
Service Fees: Fees for specialised risk management services, policy administration, and claims handling.
The Digital Distribution Model
Activa has invested heavily in digital channels to reach customers without an expensive physical branch network :
| Channel | Purpose |
|---|---|
| Online platform | Policy purchase, renewal, and management |
| MyActiva App | Comprehensive digital account management |
| USSD services | Feature phone access for the mass market |
| Mobile money integration | Payment collection via telco wallets |
This digital-first approach allows Activa to operate with just 55 employees while serving a nationwide customer base. Competitors with larger physical footprints have higher fixed costs, which must be recovered through either higher premiums or lower claims payouts.
Market Position and Competition
Industry Standing: The Claims King
Activa is uniquely positioned in Ghana‘s insurance market: #1 in claims payout, #7 in premium income. This topsy-turvy ranking reflects a strategic choice: compete on reliability, not price; on trust, not premium volume .
The “Top 5” by Claims (2024):
-
Activa International Insurance (GHS 223M)
-
Star Assurance (GHS 217M)
-
Enterprise Insurance (GHS 201M)
-
Hollard Insurance Ghana (GHS 172M)
-
Vanguard Assurance (GHS 157M)
Source:
Competitive Landscape
Activa competes across multiple segments against a diverse set of rivals:
| Competitor | Market Position | Activa‘s Relative Strength |
|---|---|---|
| Enterprise Insurance | #1 by premium; AAA rating; 102-year history | Claims leadership (Activa pays more); leaner cost structure |
| Star Assurance | #2 by claims; A+ rating; AI-driven (Pokuaa) | Activa leads in claims volume; women‘s programme differentiation |
| Hollard Insurance | #4 by claims; Top Employer; ChatInsure WhatsApp | Activa leads in claims volume |
| SIC Insurance | State-backed; declining market share | Activa pays more than twice SIC‘s claims |
| Vanguard Assurance | 5th by claims; BlueOrchard-backed | Activa leads in claims volume |
Competitive Advantages
1. Claims Leadership
The GHS 223 million figure is not a marketing claim; it is an audited fact . In an industry where trust is the only currency, Activa has the most credible proof of reliability: it pays more claims than anyone else.
2. Lean Operating Model
With just 55 employees , Activa‘s cost-to-income ratio is likely lower than competitors with large branch networks. This efficiency allows Activa to allocate more premium income to claims rather than overhead.
3. Pan-African Parentage
As a subsidiary of Activa Finance (Mauritius), Activa Ghana has access to international capital, reinsurance capacity, and underwriting expertise that purely local insurers cannot match .
4. A+ GCR Rating
Activa holds an A+(GH) national scale financial strength rating from GCR Ratings (affirmed October 2025), with a Stable Outlook . This rating indicates a strong capacity to meet policyholder obligations relative to other insurers in Ghana.
5. ISO 27001:2022 Certification
Activa has achieved internationally recognised certification in information security, enhancing trust in its digital insurance services . This certification is particularly valuable for corporate clients with stringent data protection requirements.
6. Women‘s Market Specialisation
The Activ‘Lady programme is a genuine differentiator . No other major insurer in Ghana has a dedicated product line and distribution strategy specifically targeting women entrepreneurs. As women constitute a growing segment of Ghana‘s economy, this specialisation positions Activa for long-term growth.
7. Digital Accessibility
Activa‘s investment in online, mobile, USSD, and app-based channels ensures that it can reach customers across the digital divide—from smartphone users in Accra to feature phone users in rural villages.
Competitive Disadvantages
1. Smaller Premium Base
While Activa leads in claims, it is only 7th in premium income . This means its ability to grow claims-paying capacity is constrained by its premium volume relative to larger competitors.
2. Limited Physical Presence
With its lean model, Activa does not have the branch network of Enterprise or the agent network of Star. This may limit its ability to reach customers who prefer face-to-face interactions for high-value policies.
3. Less Brand Heritage
Activa was founded in 2005 , making it one of the younger major insurers. Enterprise (1924) and SIC (1955) have deeper historical roots and generational brand recognition.
4. Smaller Employee Base
At 55 employees , Activa is lean, but also vulnerable to key-person risk. The loss of a few senior underwriters or claims specialists could disproportionately affect operations.
5. Dependency on Reinsurance
Activa‘s ability to pay GHS 223 million in claims depends on robust reinsurance arrangements. If global reinsurance markets tighten or prices rise, Activa‘s claims capacity could be affected.
Technology and Innovation: The Digital Insurer
Activa has embraced digital transformation as a core strategic pillar, investing in technology to reduce barriers to entry, improve customer experience, and expand market reach .
The MyActiva App
The MyActiva App serves as the company‘s comprehensive digital platform for policyholders . Through the app, customers can:
-
Purchase policies
-
Renew existing coverage
-
Track claims in real-time
-
Access policy documents
-
Make payments via mobile money and cards
USSD Services
Recognising that not all Ghanaians have smartphones, Activa offers USSD services that allow feature phone users to access insurance services . This channel is critical for reaching rural and lower-income customers who may not have internet access but have basic mobile phones.
Online Platform
Activa‘s website provides a full online insurance portal where customers can get quotes, purchase policies, and manage their accounts .
ISO 27001:2022 Certification
In a significant validation of its digital security posture, Activa has achieved ISO 27001:2022 certification in information security . This internationally recognised standard demonstrates that Activa has implemented robust controls to protect customer data and secure digital transactions.
For corporate clients and partners, this certification is not merely a trophy; it is a prerequisite for consideration. Many multinational corporations require their vendors and partners to hold ISO 27001 certification before they will share sensitive data.
Digital Claims Processing
Activa has invested in digital claims processing systems that enable:
-
Online claims submission
-
Real-time claims tracking
-
Automated notifications at key milestones
-
Faster settlement times
The company‘s commitment to expanding digital claims processing is intended to improve speed and transparency .
The Digital Inclusion Mandate
Salifu Abubakari has articulated a clear vision for digital transformation: to lower barriers to entry and improve customer experience, especially for SMEs and informal workers who often remain outside formal insurance systems .
This is not merely about efficiency; it is about inclusion. By reducing the friction of purchasing insurance, Activa can reach customers who have never owned a policy—the so-called “protection gap” that characterises Ghana‘s underpenetrated insurance market.
The GCR Rating: A+(GH) with Stable Outlook
On 7 October 2025, GCR Ratings (GCR) affirmed Activa International Insurance Company Limited‘s national scale financial strength rating of A+(GH) with a Stable Outlook .
What an A+(GH) Rating Means
The A+(GH) rating indicates a strong capacity to meet policyholder obligations relative to other insurers in Ghana. It is one of the highest ratings on the national scale, placing Activa in the upper echelon of financial stability.
For context:
-
AAA (gha): Exceptional capacity (Enterprise Insurance)
-
A+(GH): Strong capacity (Activa, Star Assurance)
-
A(GH): Adequate capacity
-
BBB(GH): Moderate capacity
The Stable Outlook indicates that GCR does not expect the rating to change in the near to medium term, assuming stable economic and operating conditions.
Why the Rating Matters
-
Policyholder confidence: An A+ rating signals to customers that Activa has the financial strength to pay claims.
-
Corporate client qualification: Many multinational corporations and large Ghanaian enterprises require their insurers to hold minimum credit ratings (often A- or higher). Activa‘s A+ rating qualifies it for these relationships.
-
Reinsurance terms: Higher ratings translate to better terms from reinsurers, who view well-rated cedants as lower risk.
-
Access to capital: A strong rating supports access to capital markets and bank financing if needed.
-
Competitive differentiation: In a market where not all insurers hold published ratings, Activa‘s A+ rating with a Stable Outlook is a significant competitive asset.
Factors Supporting the Rating
While the specific GCR rationale is not detailed in available sources, the affirmation is likely supported by:
-
Strong claims-paying capacity (evidenced by the GHS 223 million figure)
-
Robust reinsurance arrangements
-
Conservative investment management
-
Support from the pan-African Activa Group
-
Stable management and governance
Challenges and Risks
No analysis of Activa International Insurance Ghana is complete without acknowledging the headwinds that accompany its claims leadership.
Risk 1: The Premium-Claims Gap
Activa‘s #1 position in claims but #7 position in premium income creates a structural tension . Paying more claims than larger competitors requires either:
-
Higher claims ratios: A higher percentage of premium income paid out as claims, which pressures underwriting profitability
-
Superior investment income: Investment returns subsidising the claims account
-
Reinsurance support: Reinsurers bearing a portion of the claims burden
If Activa‘s claims ratio is significantly higher than the industry average, it could face pressure from its parent to improve underwriting profitability.
Risk 2: The Reinsurance Dependency
Activa‘s ability to pay GHS 223 million in claims depends on robust reinsurance arrangements. Global reinsurance markets are cyclical; following periods of catastrophic losses (natural disasters, pandemics), reinsurance prices rise and capacity tightens.
If Activa cannot secure reinsurance at favourable terms, it would either need to:
-
Retain more risk (requiring more capital)
-
Reduce its claims payout (damaging its brand positioning)
-
Raise premiums (potentially losing market share)
Risk 3: Leadership Transition Uncertainty
The appointment of Salifu Abubakari as Acting Managing Director is a strength, but any leadership transition carries risk. Abubakari must:
-
Maintain Activa‘s claims leadership
-
Continue digital transformation
-
Expand market share
-
Manage relationships with regulators, reinsurers, and the parent group
If the transition is not seamless, Activa could lose momentum.
Risk 4: Competition from Enterprise and Star
Enterprise Insurance (AAA rating, 102-year heritage) and Star Assurance (A+ rating, AI-driven innovation) are formidable competitors. Both have deeper pockets, larger employee bases, and strong brand recognition. If they decide to prioritise claims leadership, they have the resources to potentially surpass Activa.
Risk 5: Economic Headwinds
As a non-life insurer, Activa is exposed to Ghana‘s macroeconomic environment:
-
Inflation: Claims costs (repairs, replacements) rise with inflation, but premiums are often fixed for policy terms
-
Currency depreciation: Reinsurance costs are often denominated in foreign currency (USD, EUR). If the cedi depreciates, those costs rise
-
Interest rates: Investment income from fixed-income securities fluctuates with policy rates
-
Claims frequency: Economic downturns often correlate with increased claims frequency (e.g., more uninsured drivers, more fires in poorly maintained properties)
Risk 6: The Digital Race
While Activa has invested in digital channels, competitors are not standing still. Star Assurance‘s Pokuaa AI offers automated claims initiation and customer support. Enterprise has its own digital portals. To maintain its digital differentiation, Activa must continue investing in technology—a costly endeavour for a lean organisation.
Risk 7: The Women‘s Market Execution
The Activ‘Lady programme is strategically sound, but execution is everything. Activa must ensure that:
-
The products are genuinely tailored to women‘s needs, not just rebranded generic policies
-
Distribution channels reach women entrepreneurs effectively
-
Claims handling for women policyholders is efficient and fair
If the programme is perceived as marketing gimmick rather than genuine inclusion, it could backfire.
Risk 8: Regulatory Scrutiny
As the #1 claims payer, Activa is now the standard against which other insurers are measured. Regulators may scrutinise Activa‘s claims practices, reserving policies, and reinsurance arrangements more closely. This scrutiny is not necessarily negative, but it imposes compliance costs.
Economic and Industry Impact
Insurance Penetration in Ghana
Ghana‘s insurance penetration (premiums as a percentage of GDP) remains stubbornly low—below 3%, far below the levels in South Africa (over 15%) . The reasons are well-documented: lack of trust, affordability concerns, cultural perceptions, and limited awareness .
Activa‘s claims leadership directly addresses the trust deficit. When Activa pays GHS 223 million in claims, it is not just settling individual policies; it is sending a signal to the entire market that insurance works, that insurers do pay, and that policyholders can rely on protection.
Employment and Ecosystem
Activa directly employs approximately 55 people . While this is a small number, the company supports a broader ecosystem of:
-
Brokers and agents: Independent intermediaries who sell Activa policies on commission
-
Loss adjusters: Firms that investigate and assess claims
-
Repair shops: Auto body shops and other service providers paid by Activa for claim repairs
-
Reinsurers: Global and regional reinsurers who assume a portion of Activa‘s risk
Women‘s Economic Empowerment
The Activ‘Lady programme is a concrete contribution to women‘s economic empowerment . By providing tailored insurance products to women entrepreneurs, Activa enables these business owners to:
-
Protect their businesses against fire, theft, and other risks
-
Access credit (lenders are more willing to lend to insured businesses)
-
Build resilience against shocks that could otherwise destroy their livelihoods
Formalising the Informal Economy
Many of Activa‘s target customers—market traders, small shop owners, transporters—operate in the informal economy. By selling them insurance policies, Activa brings these individuals into the formal financial system. A customer with an insurance policy is more likely to open a bank account, access credit, and participate in other formal financial services.
Competition and Consumer Choice
Activa‘s presence in the insurance market keeps prices competitive and gives consumers alternatives to the dominant players. The company‘s focus on claims payment disciplines the entire industry; competitors cannot afford to be seen as unreliable when Activa is paying GHS 223 million annually.
The NIC Report‘s Significance
The National Insurance Commission‘s annual report is the definitive source on industry performance . By leading the non-life claims category, Activa has secured a place in that report that analysts, journalists, and competitors will reference for years. This is permanent validation.
Future Outlook
As of May 2026, Activa International Insurance Ghana is executing a strategy built on claims leadership, digital transformation, and inclusive distribution. The appointment of Salifu Abubakari as Acting Managing Director marks the beginning of a new chapter, but the strategic direction is likely to continue the trajectory established by his predecessors.
The Immediate Agenda (2026-2027)
Activa‘s priorities are likely to include:
-
Defending claims leadership: Maintaining the #1 position in non-life claims payout against increasingly aggressive competitors
-
Expanding digital claims processing: Investing in technology to make claims submission, tracking, and settlement faster and more transparent
-
Scaling the Activ‘Lady programme: Expanding the women‘s insurance initiative to reach more entrepreneurs and deepen engagement
-
Strengthening the SME product suite: Developing new products for small and medium enterprises, including bundling options
-
Maintaining the A+ rating: Ensuring that financial metrics support the continued affirmation of the GCR rating
-
Deepening corporate relationships: Leveraging the Globus Network and credit insurance offerings to win more corporate and multinational clients
The Bull Case (Optimistic)
-
Trust premium drives growth: Activa‘s claims leadership becomes widely known; customers switch from competitors specifically because Activa pays claims reliably. Activa moves from #7 to #5 or #4 in premium income within 2-3 years.
-
Digital claims processing becomes a competitive moat: Activa‘s investment in digital claims technology yields faster settlement times than competitors; this efficiency attracts customers and reduces administrative costs.
-
Activ‘Lady scales to national programme: The women‘s insurance initiative reaches hundreds of thousands of women entrepreneurs; Activa becomes the default insurer for women-owned businesses.
-
Abubakari‘s leadership delivers: The new Acting Managing Director‘s technical expertise (CPCU) and industry relationships (CPCU Society President) drive underwriting improvements, new partnerships, and sustained growth.
-
Parent group support intensifies: Activa Finance recognises Ghana as a strategic market and provides additional capital or reinsurance capacity to support further expansion.
The Bear Case (Pessimistic)
-
Claims leadership is overtaken: Star Assurance or Enterprise surpass Activa in claims payout; Activa loses its primary differentiator and struggles to articulate why customers should choose it.
-
The premium-claims gap proves unsustainable: Activa‘s claims ratio persistently exceeds profitable levels; the parent group demands underwriting discipline, forcing Activa to tighten claims standards or raise premiums; customer trust erodes.
-
Digital investments fail to keep pace: Competitors‘ AI and automation capabilities outpace Activa‘s; Activa‘s digital channels become dated; customers migrate to more sophisticated competitors.
-
Economic downturn stresses the portfolio: Ghana enters a recession; claims frequency spikes while premium income stagnates; Activa faces liquidity pressure despite reinsurance support.
-
Leadership transition stumbles: Abubakari struggles to fill the role; key talent departs; strategic execution slows.
The Verdict
Activa International Insurance Ghana is a case study in strategic differentiation. In a market where most insurers compete on price, distribution, or brand heritage, Activa has chosen to compete on reliability—specifically, the reliability of claims payment.
The 2024 NIC report validated this strategy: GHS 223 million in claims paid, more than any other non-life insurer in Ghana . This is not a marketing claim; it is an audited fact. For a company that is only the 7th largest by premium income , this is remarkable.
The appointment of Salifu Abubakari as Acting Managing Director brings technical depth (CPCU), industry leadership (President of CPCU Society West Africa), and academic engagement to the role. His mandate is to sustain Activa‘s claims leadership while expanding digital capabilities and market reach.
The A+ rating from GCR (affirmed October 2025) with a Stable Outlook provides third-party validation of Activa‘s financial strength. The ISO 27001:2022 certification signals that digital security is taken seriously. The Activ‘Lady programme demonstrates genuine commitment to inclusion.
The risks are real: the premium-claims gap, reinsurance dependency, leadership transition execution, competition from deeper-pocketed rivals. But Activa has demonstrated that a lean, focused, digitally-enabled insurer can compete—and lead—in a market dominated by giants.
For the Ghanaian policyholder, Activa offers the most credible proof of reliability: the highest claims payout in the industry. For the corporate client, Activa offers an A+ rating and ISO certification. For the women entrepreneur, Activa offers a programme designed specifically for her needs.
Activa is not trying to be the biggest insurer in Ghana. It is trying to be the most trusted. And by the only metric that ultimately matters—claims paid—it already is.
FAQ SECTION
1. Is Activa International Insurance Ghana a Ghanaian-owned company?
No. Activa International Insurance Ghana is a subsidiary of Activa Assurances, a pan-African insurance group, which is part of Activa Finance, a Mauritius-based holding company. The company was originally incorporated in Ghana as Global Alliance Insurance in 2005 and was acquired by Activa Assurances in 2009 .
2. Who is the CEO of Activa International Insurance Ghana?
Effective February 2, 2026, Salifu Abubakari is the Acting Managing Director. He is a KNUST alumnus with over 18 years of insurance industry experience, holds the prestigious CPCU designation, and serves as President of the CPCU Society West Africa .
3. How did Activa perform in claims in 2024?
According to the 2024 National Insurance Commission (NIC) report, Activa International Insurance Ghana paid GHS 223 million in non-life claims—the highest of any non-life insurer in the country. This was ahead of Star Assurance (GHS 217M), Enterprise Insurance (GHS 201M), and all others .
4. What is Activa‘s rating from GCR?
Activa holds a national scale financial strength rating of A+(GH) from GCR Ratings, affirmed on 7 October 2025, with a Stable Outlook . This indicates a strong capacity to meet policyholder obligations relative to other insurers in Ghana.
5. What types of insurance does Activa offer?
Activa is a non-life (general) insurance company offering motor insurance, travel insurance, home insurance, personal accident, fire and allied perils, marine and assets all risks, SME risk solutions, credit insurance, and the specialised Activ‘Lady programme for women entrepreneurs .
6. What is the Activ‘Lady programme?
Activ‘Lady is Activa‘s gender-focused insurance initiative designed to support women entrepreneurs and professionals. The programme offers tailored insurance products for women-owned businesses, addressing risks specific to women entrepreneurs in Ghana‘s informal and formal sectors .
7. Does Activa have a mobile app?
Yes. Activa offers the MyActiva App for comprehensive digital account management. The company also provides online platform access, mobile access, and USSD services for feature phone users .
8. Is Activa ISO certified?
Yes. Activa has achieved ISO 27001:2022 certification in information security, demonstrating internationally recognised standards for protecting customer data and securing digital transactions .
9. How many employees does Activa have?
Activa operates with a lean team of approximately 55 employees. The company has experienced 12.22% year-over-year headcount growth and 1.85% month-over-month growth .
10. What is Activa‘s market position by premium income?
Activa is the 7th largest non-life insurer in Ghana by premium income, out of 30 licensed non-life insurance companies. However, it is the #1 non-life insurer by claims paid—demonstrating that it punches significantly above its weight in policyholder protection .
11. How does Activa compare to Enterprise Insurance?
Enterprise Insurance is the market leader by premium income with a AAA rating and 102-year history. Activa leads Enterprise in claims payout (GHS 223M vs GHS 201M) despite having a smaller premium base. Activa is leaner, more digitally focused, and has a specialised women‘s programme that Enterprise does not offer .
12. How can I contact Activa International Insurance Ghana?
Activa‘s headquarters is located in Accra. Customers can access services through the MyActiva App, the online platform, USSD services, or by calling the company‘s customer service line. Specific contact details are available on the company‘s website.
QUICK FACTS BOX
| Item | Details |
|---|---|
| Founded | 2005 (as Global Alliance Insurance); Acquired by Activa Assurances 2009 |
| Headquarters | Accra, Ghana |
| Industry | Non-Life / General Insurance |
| Services | Motor, Travel, Home, Personal Accident, Fire, Marine, SME, Credit, Activ‘Lady |
| Ownership | Subsidiary of Activa Assurances / Activa Finance (Mauritius) |
| Acting Managing Director | Salifu Abubakari (appointed February 2, 2026) |
| Employees | ~55 |
| Market Position (Premium) | 7th largest non-life insurer in Ghana |
| Market Position (Claims) | #1 non-life claims payer in Ghana |
| Claims Paid (2024) | GHS 223 million |
| GCR Rating | A+(GH) – affirmed 7 October 2025; Stable Outlook |
| Key Certification | ISO 27001:2022 (Information Security) |
| Key Initiative | Activ‘Lady (women entrepreneurs programme) |
| Digital Channels | MyActiva App, Online Platform, USSD, Mobile Access |
| Key Differentiator | Highest claims payout in the industry |
| Regulator | National Insurance Commission (NIC) |
| Website | activa.com.gh (inferred; not explicitly cited) |
Source: Accra Street Journal
Last Updated on May 4, 2026 by Samuel Kwame Boadu
Disclaimer: Some content on Accra Street Journal may be aggregated, summarized, or edited from third-party sources for informational purposes. Images and media are used under fair use or royalty-free licenses. Accra Street Journal is a subsidiary of SamBoad Publishing Hub under SamBoad Business Group Ltd, registered in Ghana since 2014.
For concerns or inquiries, please visit our Privacy Policy or Contact Page.

Samuel Kwame Boadu is a Ghanaian media entrepreneur and storyteller with a passion for amplifying urban voices and uncovering everyday truths. He is the Editor-in-Chief and Founder of Accra Street Journal, a dynamic digital platform dedicated to capturing the pulse of Ghana’s capital—its people, culture, challenges, business, sports and innovations.