From MTN’s MoMo-based financing to M-KOPA’s daily payment model, the Buy Now, Pay Later phone business is transforming how Accra residents access smartphones. This ASJ article breaks down the key players, their business models, and how it all works.
Introduction
Smartphone affordability is a major barrier in Ghana. An entry-level smartphone can cost up to 95% of a low-income earner’s monthly wages in Sub-Saharan Africa, and approximately 76% of the region’s population does not own a smartphone . With only 13% of Ghana’s eligible population having access to formal borrowing, traditional financing is out of reach for many .

This is where Buy Now, Pay Later (BNPL) phone schemes come in. They allow customers to acquire a device with a small deposit and spread the remaining cost over weeks or months. In Accra, a diverse ecosystem of players—from telecom giants to fintech startups—is making this possible .
📢 GET A DETAILED ARTICLES + JOBS
Join ASJ's WhatsApp Channel and never miss a post or opportunity.

Key Companies and Business Models in Accra
1. MTN Ghana: Pick and Pay Later
The Business Model: MTN’s “Pick and Pay Later” is a telecom-led financing scheme offered in partnership with Access Bank Ghana PLC, MobileMoney Ltd, Hollard Insurance, and PaySwitch .
How It Works:

-
Customers dial *170#, go to Financial Services → Loans → Device Pick and Pay Later
-
MTN assesses creditworthiness using a credit-scoring engine
-
Upon approval, customers pay an initial deposit via MoMo
-
They visit designated service centres (Accra Mall, Junction Mall, West Hills Mall, Osu Supreme, Achimota Mall) with their Ghana Card to collect the device
-
The remaining balance is paid monthly over 4 or 6 months via MoMo
Key Features:
-
Devices: Samsung A05, A15, A25
-
Insurance: Included for theft and accidental damage
-
Default: Phone is locked after 24 hours of non-payment
-
Limit: One active loan at a time
-
Benefit: 3GB free data monthly for 6 months
Revenue Streams: Interest, insurance fees, and increased mobile data usage.
2. M-KOPA: Pan-African Fintech Leader
The Business Model: M-KOPA operates a pay-as-you-go model where customers make daily payments based on the total cost divided by 365 days . Since launching in Ghana in 2021, it has unlocked over GHS 1.2 billion in credit for more than 550,000 customers .
How It Works:
-
Customers pay a small initial deposit and take home a phone
-
They make daily repayments that match their natural earning patterns
-
After completing payments, ownership transfers to the customer
Key Features:
-
Bundled Services: “More than a Phone” includes health insurance (via Turaco), data, device protection, and digital loans
-
Impact: 67% accessed health insurance for the first time; 76% report improved quality of life
-
Devices: X-Series smartphones (developed with HMD), Samsung phones
-
Sales Force: Over 3,000 direct sales agents in Ghana
Revenue Streams: Device margins, embedded service fees (health insurance, data), and customer data value . The parent company generates $400 million in annual recurring revenue across Africa .
3. Hala GH: Proudly Ghanaian
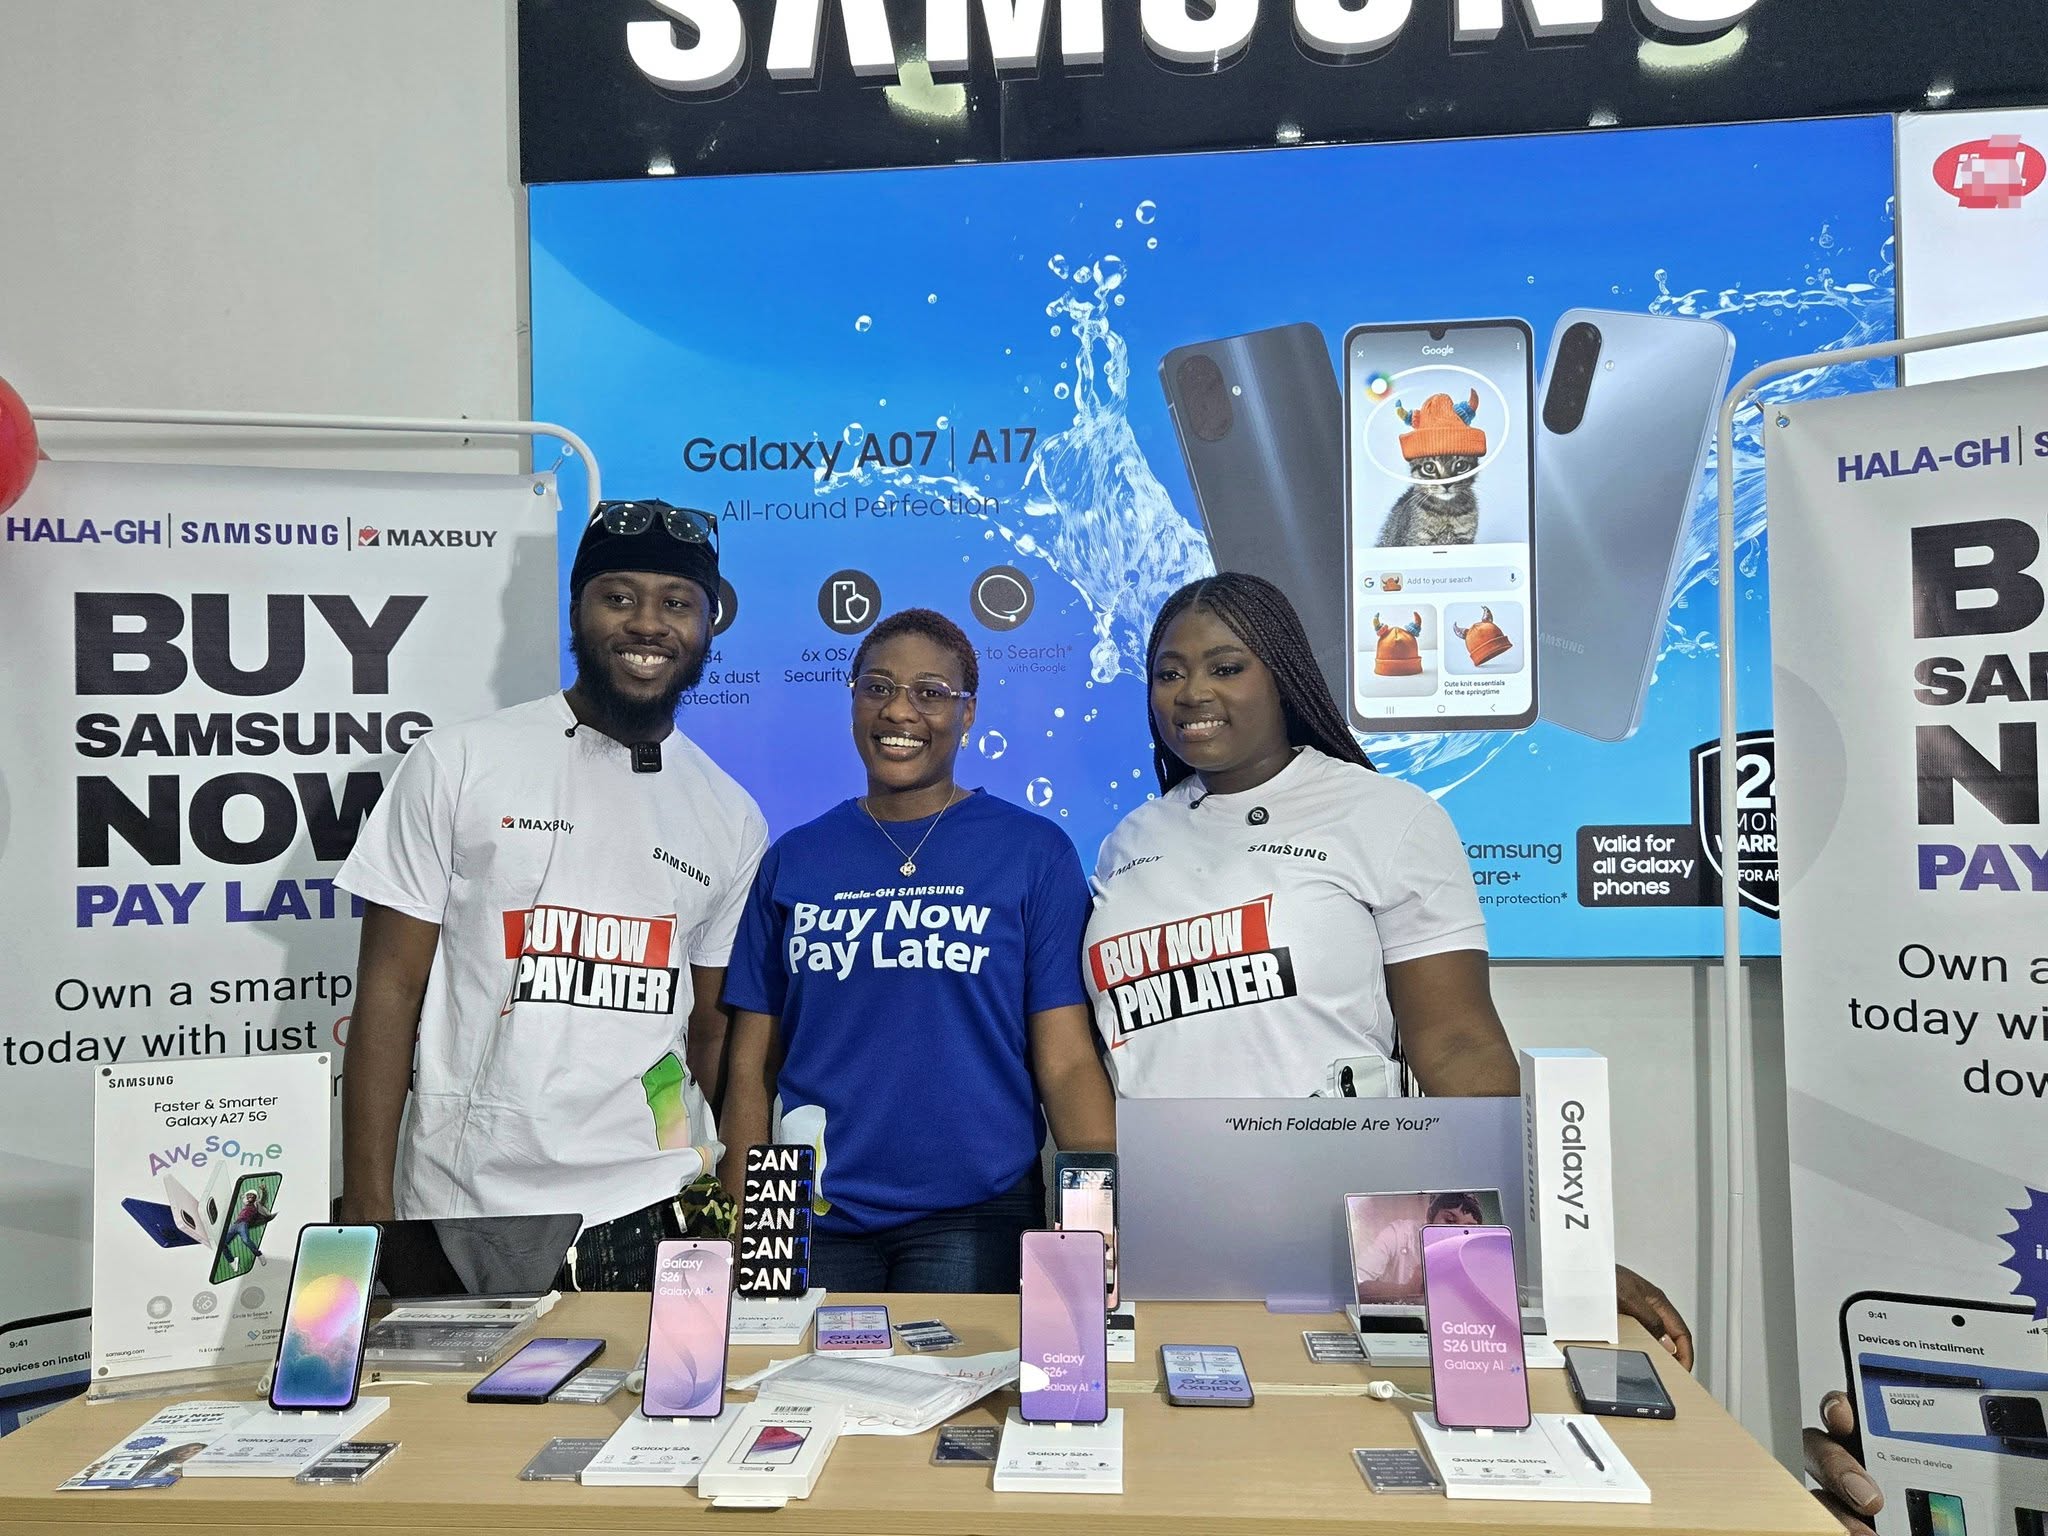
The Business Model: Hala GH is a Ghanaian company offering Samsung smartphones with a minimum deposit of GH¢300 and the balance spread over four months .
How It Works:
-
Customers need only a Ghana Card and a guarantor
-
Pay a minimum deposit of GH¢300 (e.g., for a GH¢1,700 phone)
-
Balance is spread over four months
Key Features:

-
Devices: Samsung Galaxy A06, A07, A16, A17 (with A26, A36, A56 coming)
-
Security: Samsung Knox Guard locks devices if payments are missed
-
Partners: Technology R US, Capital Phones, Gafkwa Trading Enterprise
Revenue Streams: Device margins and service fees built into repayment structures .
4. MaxBuy + Fido Partnership
The Business Model: MaxBuy, a major electronics retailer, partnered with Fido (a digital lending platform) to offer BNPL financing for smartphones .
How It Works:
-
Customers shop at MaxBuy stores (Accra locations: East Legon, Achimota Mall, Takoradi)
-
Fido determines eligibility through its app
-
The cost is spread across up to 6 equal installments
Key Features:
-
Products: Samsung, iPhone, Tecno, Infinix, itel
-
Target: All income levels, from high-income earners to low-income households
5. Motito: “PaySmallSmall” Layaway Model
The Business Model: Motito is an Accra-based fintech startup offering a layaway-first plan where customers secure today’s price, protecting against inflation .
How It Works:
-
Customers secure the price (inflation protection)
-
Payments are made daily, weekly, or monthly
-
On-time payments unlock “Early Pickup” (collect before completing payment)
Key Features:
-
Model: “PaySmallSmall” layaway-first
-
Investors: Visa Accelerator, Ecobank Transnational (raised $143,000)
-
Regulatory: Admitted into Bank of Ghana’s Regulatory Sandbox
Revenue Streams: Device margins.
6. Easybuy
The Business Model: Easybuy is an app-based consumer finance product that provides installment services for customers to buy phones .
How It Works:
-
Register and apply via the app
-
Get approval (20-40 minutes, no paperwork, no collateral)
-
Pay down payment (as low as 30%)
-
Get new phone
Key Features:
-
Payment Terms: 3, 4, 5, or 6 months
-
Devices: Any brand
-
Location: Accra-based, operated by DEXINTEC FINANCE GHANA LIMITED
7. Appiah Phones
The Business Model: Appiah Phones is an online retailer offering installment payment plans for smartphones .
How It Works:
-
Search for a product via the Appiah Phones app
-
Get an instant price quote
-
Pay a secure down payment via Paystack
-
Spread the rest over weekly payments
-
Track all installment plans in the app
How BNPL Phone Business Models Work: The Core Principles
Despite the variety of players, BNPL phone business models in Ghana operate on similar principles :
-
Provide Access to Productive Assets: Smartphones are framed as essential tools for income generation and digital inclusion .
-
Flexible Payment Structures: Payment terms are designed to match customers’ income patterns—daily, weekly, or monthly .
-
Device Locking for Default: Most providers use technology to lock devices if payments are missed . Services like Smart Mobile Finance (SMF) provide anti-tamper locks that survive factory resets, ensuring retailers can recover devices .
-
Creditworthiness Assessment: Providers use credit scoring engines, Ghana Card verification, and sometimes guarantors .
-
Revenue Generation: Revenue comes from interest, device margins, embedded service fees (data, insurance, digital loans), and customer data value .
Quick Comparison of BNPL Phone Companies in Accra
| Company | Model | Deposit | Repayment | Key Feature |
|---|---|---|---|---|
| MTN Pick and Pay Later | Telecom-led | Varies | 4–6 months | Insurance, free data |
| M-KOPA | Pay-as-you-go | Varies | 365 days daily | Health insurance, data |
| Hala GH | Device financing | GH¢300+ | 4 months | Ghana Card + guarantor |
| MaxBuy + Fido | Retailer + fintech | Varies | Up to 6 months | Various brands |
| Motito | Layaway-first | Varies | Daily/weekly/monthly | Inflation protection |
| Easybuy | App-based | 30%+ | 3–6 months | No paperwork |
| Appiah Phones | Online retail | Varies | Weekly | Paystack payments |
ASJ Conclusion
The Buy Now, Pay Later phone business model in Accra is thriving, driven by a mix of telecoms, fintechs, retailers, and local startups. These companies are making smartphone ownership accessible to millions of Ghanaians, with M-KOPA alone unlocking over GHS 1.2 billion in credit for more than 550,000 customers .
As Matilda Asante-Asiedu of Access Bank noted, “Only 13% of the eligible population currently have access to borrowing, leaving a substantial gap for those who qualify but lack access to finance. This initiative reflects Access Bank’s vision of empowering individuals to support their lifestyles in an increasingly digital world” .
Quick Facts
| Topic | Details |
|---|---|
| MTN Pick & Pay Later | Dial *170#, 4–6 months repayment, Samsung phones |
| M-KOPA | Daily payments, health insurance bundled |
| Hala GH | GH¢300+ deposit, 4-month repayment |
| Motito | In Bank of Ghana Regulatory Sandbox |
| Only ~13% | Ghana’s population has formal credit access |
| GHS 1.2 billion | Credit unlocked by M-KOPA in Ghana |
| 550,000+ | Customers reached by M-KOPA Ghana |
Frequently Asked Questions
1. What is Buy Now Pay Later for phones in Accra?
It is a device financing model where customers can acquire a smartphone with a small initial deposit and spread the remaining cost over weeks or months through flexible payment plans.
2. What companies offer BNPL phones in Accra?
MTN (Pick and Pay Later), M-KOPA, Hala GH, MaxBuy (with Fido), Motito, Easybuy, and Appiah Phones all offer BNPL phone schemes in Accra.
3. How does MTN Pick and Pay Later work?
Dial *170#, complete a credit check, pay an initial deposit via MoMo, collect your phone from an MTN service centre with your Ghana Card, and repay the balance over 4 or 6 months.
4. Where can I collect my MTN Pick and Pay Later phone?
MTN service centres include Accra Mall, Junction Mall, West Hills Mall, Osu Supreme, and Achimota Mall.
5. What is M-KOPA’s business model?
M-KOPA operates a pay-as-you-go model where customers make daily payments over 365 days. The “More than a Phone” offering bundles health insurance, data, and device protection.
6. What is Hala GH?
Hala GH is a Ghanaian company offering Samsung smartphones with a minimum deposit of GH¢300 and the balance spread over four months. Customers need a Ghana Card and a guarantor.
7. What is Motito?
Motito is an Accra-based fintech startup offering a layaway-first “PaySmallSmall” plan where customers secure today’s price and pay in installments. It was admitted into the Bank of Ghana’s Regulatory Sandbox.
Source: Accra Street Journal
Last Updated on August 29, 2026 by Samuel Kwame Boadu
Disclaimer: Some content on Accra Street Journal may be aggregated, summarized, or edited from third-party sources for informational purposes. Images and media are used under fair use or royalty-free licenses. Accra Street Journal is a subsidiary of SamBoad Publishing Hub under SamBoad Business Group Ltd, registered in Ghana since 2014.
For concerns or inquiries, please visit our Privacy Policy or Contact Page.

Samuel Kwame Boadu is a Ghanaian media entrepreneur and storyteller with a passion for amplifying urban voices and uncovering everyday truths. He is the Editor-in-Chief and Founder of Accra Street Journal, a dynamic digital platform dedicated to capturing the pulse of Ghana’s capital—its people, culture, challenges, business, sports and innovations.