A 2026 Intelligence Brief from Accra Street Journal
Executive Introduction
Ghana possesses some of West Africa’s most abundant renewable energy resources. Average solar irradiation exceeds 5 kWh/m² per day, reaching up to 6.5 kWh/m² in the northern regions . Coastal wind zones rank between levels 2 and 6 on the Energy Commission’s wind density scale—ranges considered suitable for power generation . Government targets are ambitious: 10 percent renewable penetration (excluding large hydro) by 2030, backed by a Renewable Energy Master Plan and a National Energy Compact.

Yet, by the end of 2023, installed solar and wind capacity accounted for just 2.3 percent of Ghana’s total generation—132 MW out of 5,639 MW . Annual capacity additions remain a fraction of the 340 MW per year required to meet the 2030 target.
📢 GET A DETAILED ARTICLES + JOBS
Join ASJ's WhatsApp Channel and never miss a post or opportunity.

This ASJ report examines the structural, financial, and institutional barriers that have kept Ghana’s renewable energy market underdeveloped despite favourable policy rhetoric. The evidence suggests that the constraints are not technical—Ghana has the resources and the technology is proven. The binding constraints are policy uncertainty, financial sector risk aversion, institutional dysfunction, and grid fragility. Until these are addressed, renewable energy will remain a marginal contributor to Ghana’s power mix, regardless of how many master plans are written.
Part 1: The Policy Barrier — PPA Moratoriums and Regulatory Uncertainty
The most significant barrier to renewable energy development in Ghana is not the absence of policy—it is the unpredictability of the policy environment.

The 2017–2023 PPA Moratorium
The government imposed a moratorium on new Power Purchase Agreements (PPAs) for renewables in 2017, and for gas in 2018 . This was a response to a severe policy mistake made earlier in the 2010s: Ghana signed take-or-pay contracts with independent power producers (IPPs) obligating the state to pay for unused capacity, creating what the Climate Policy Lab estimates as over $3 billion in energy sector debt .
The moratorium was partially lifted in 2023, but the regulatory framework remains tight. Investors still require guarantees from the state-owned Electricity Company of Ghana (ECG), which faces serious financial constraints. As of 2024, ECG’s debts to IPPs stood at $1.73 billion .
The investor’s dilemma: A renewable energy developer cannot secure project financing without a credible off-taker. ECG’s poor financial health and the government’s history of contract suspensions make it difficult to sign bankable PPAs. Developers who do sign face the risk that future governments will renegotiate or annul contracts—as happened with many thermal IPP contracts.
The State-Owned Power Plant Paradox
In January 2026, the government announced plans to build a 1,200 MW state-owned thermal power plant, intended to absorb additional gas from the Offshore Cape Three Points (OCTP) expansion . The announcement drew mixed reactions.
The Africa Centre for Energy Policy (ACEP) warned that the success of a new state-owned plant will depend less on technical merits than on whether Ghana’s power sector reforms can resolve deep-rooted financial and liquidity constraints. ACEP noted that VRA’s existing plants have been weakened by chronic payment delays and liquidity shortfalls across the energy value chain, resulting in degraded maintenance cycles, rising debt levels, and declining operational efficiency .
The contradiction for renewable energy: The government continues to invest in thermal generation while expecting private capital to flow to renewables. This sends mixed signals to investors. If the state prioritises thermal capacity expansion, private developers question whether the government is genuinely committed to the renewable transition—or whether renewables are merely a rhetorical add-on to a fossil-fuel-dominated strategy.
Part 2: The Financial Barrier — High Costs, Currency Risk, and Limited Access to Capital
Even where policy is favourable, the financial barriers to renewable energy adoption in Ghana are formidable.
Identified Financial Barriers
A comprehensive 2025 study using the Delphi method and fuzzy synthetic evaluation identified 44 barriers to renewable energy adoption in Ghana, grouped into six categories: policy, institutional, economic/financial, structural/technical, political/legal/regulatory, and social . The analysis ranked policy, economic/financial, and institutional barriers as the most important.
Specific financial impediments included:

| Barrier | Description |
|---|---|
| High commercial interest rates | Renewable energy projects require upfront capital; Ghana’s high lending rates (typically 25–30%) make projects difficult to finance |
| Currency fluctuation risk | PPAs are typically denominated in US dollars or cedis; cedi volatility creates currency mismatch risk for developers |
| Lack of market-driven support mechanisms | Feed-in tariffs exist but are not consistently applied; subsidies are insufficient |
| High upfront costs | Solar and wind projects remain capital-intensive, and local financing is scarce |
The Mini-Grid Financing Gap
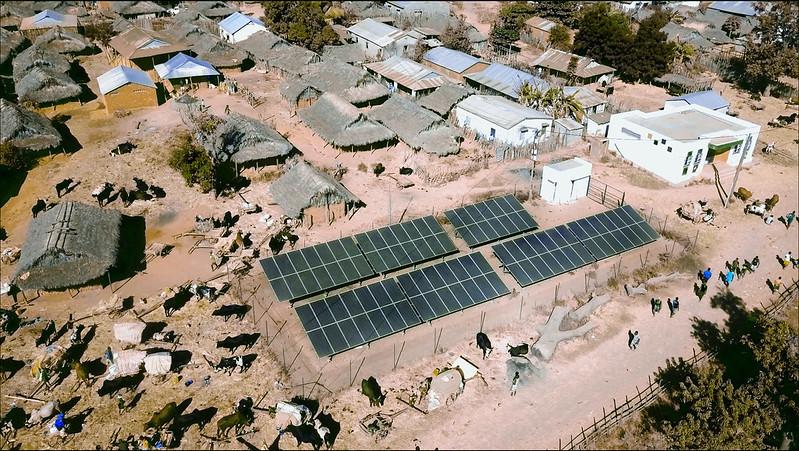
The financing constraint is particularly acute for off-grid renewable energy. Energy Minister John Abdulai Jinapor acknowledged in February 2026 that “financing remains a hurdle — high costs and risks deter private players” from investing in mini-grids .
Despite Ghana’s national electricity access rate reaching 89.03 percent, about 3.5 million people—mainly in remote, island, and lakeside communities—lack reliable power . Extending the national grid to these communities is often slow and capital-intensive, making mini-grids a logical solution. But the high upfront costs and perceived risks continue to deter private sector participation.
The Scaling-Up Renewable Energy Programme (SREP), backed by the African Development Bank, is a step forward, but its $85 million budget is a fraction of what is required to electrify the 3.5 million Ghanaians still without access.
The Cross-Sectoral Debt Crisis
The broader energy sector debt crisis—estimated at over $3 billion —crowds out investment in renewables. When ECG cannot pay its existing IPPs, it cannot credibly commit to paying new renewable energy producers. The Cash Waterfall Mechanism (CWM), designed to streamline payments, prioritises standing payments to IPPs, leaving state-owned generators exposed to revenue shortfalls . Renewable energy developers, many of which are not vertically integrated with state-owned entities, face uncertain payment timelines.
Part 3: The Institutional Barrier — Dysfunction, Skills Gaps, and Maintenance Deficits
Beyond policy and finance, Ghana’s renewable energy market suffers from institutional weaknesses that undermine project implementation and long-term sustainability.
Institutional Dysfunction as an Impeding Force
A 2024 study published in World Development examined how institutional dysfunction affects solar PV scaling-up efforts in Ghana
| Phase | Description |
|---|---|
| Phase 1 | Institutional dysfunctions (bureaucratic agencies, weak information disclosure, poor legal enforcement) act as impeding forces on both upstream and downstream activities |
| Phase 2 | Organisations engage in strategic interventions to reshape institutional dysfunctions, turning them into potential sources of opportunity |
| Phase 3 | Focus shifts to deficiencies in the aftermarket support environment—specifically maintenance and repair services after sales |
The study highlights that weak legal enforcement mechanisms and bureaucratic government agencies remain powerful forces constraining solar PV firms’ ability to scale. For a developer trying to secure permits, connect to the grid, or enforce a PPA, these dysfunctions translate directly into delays, increased costs, and heightened risk.
Skills Shortages and Technical Capacity Gaps
A 2025 study on utility-scale solar PV implementation identified lack of skilled professionals as one of the critical barriers to solar adoption in Ghana . Using a mixed-method approach (literature review, Delphi surveys, and interpretive structural modeling), researchers found that skills shortages are not isolated—they are interconnected with other barriers.
The absence of locally trained technicians, engineers, and project managers means that solar PV projects depend on foreign expertise, increasing costs and complicating maintenance. When systems break down, troubleshooting is difficult, and replacement parts may not be readily available.
The Maintenance and Aftermarket Gap
Phase 3 of the institutional dysfunction study focuses on aftermarket support: maintenance and repair services after sales. Across Ghana’s renewable energy sector, maintenance ecosystems are weak. This is particularly acute for off-grid systems. A Ghanaian official warned that sustaining off-grid solar systems “will require stronger operation and maintenance frameworks than those typically observed across the region” . Without such frameworks, even well-designed renewable assets risk falling into disrepair.
Part 4: The Technical Barrier — Grid Integration and Intermittency
Even if financing and policy barriers were resolved, Ghana’s grid cannot currently absorb large amounts of variable renewable energy without significant upgrades.

Grid Instability from Solar Integration
ASEC Executive Director Justice Ohene-Akoto explained the technical challenge: “When you feed solar into the grid, it can destabilize the frequency, which could collapse the system” . Solar PV generation is intermittent—it fluctuates with cloud cover and stops entirely at night. Integrating large amounts of solar requires:
-
Battery storage to smooth output and shift generation to peak demand periods
-
Smart grid technologies to manage bidirectional power flows
-
Demand response systems to match consumption with variable generation
Ghana has made limited investment in any of these enabling technologies.
The Grid Modernisation Gap
A 2025 study on utility-scale solar PV found that grid integration challenges are a significant barrier to solar implementation . The study, which used interpretive structural modeling to map interrelationships among barriers, revealed that grid integration issues are not independent—they are driven by policy uncertainty, financial constraints, and institutional dysfunction.
The April 2026 Akosombo substation fire, which damaged critical control systems at one of the country’s most important transmission hubs, exposed the fragility of grid infrastructure. Benjamin Nsiah, Director of the Centre for Environmental Management and Sustainable Energy, attributed the fire to “poor planning, over-politicisation, and the absence of regular system audits.” The same planning deficits that caused the substation fire threaten the grid’s ability to integrate renewable energy.
The 2027 Capacity Gap
IPP-Ghana CEO Elikplim Kwabla Apetorgbor warned that delays in capacity additions beyond the 2028–2030 projected supply shortfall window could materially weaken system reliability. Studies indicate that reserve margins could fall below the 15 percent planning threshold, increasing the Loss of Load Probability . In such a scenario, emergency power procurement could cost between US$0.20 and US$0.30 per kilowatt-hour, compared with thermal generation costs of about US$0.08 to US$0.12 per kWh .
The irony: The capacity gap that makes thermal investment urgent also creates an opportunity for renewables—if they can be deployed quickly enough. But grid constraints prevent rapid renewable deployment. This is the central technical paradox of Ghana’s energy transition.
Part 5: Policy Implementation Gaps — Plans Without Execution
Ghana is not lacking in renewable energy plans. The Renewable Energy Act (2011), the Renewable Energy Master Plan (2019), the National Energy Transition Plan (2023), and the National Energy Compact all articulate ambitious targets. The problem is implementation.
The Mini-Grid Policy Gap
A 2025 study assessing the effectiveness of energy policies in accelerating renewable energy-based mini-grid deployment used Ghana as a case study . The research, employing weighted sum multi-criteria decision and SWOT analysis, evaluated the impact of energy policies on mini-grid development.
The results: numerous energy policies implemented across Ghana did not fully promote mini-grid development. Only the Renewable Energy Master Plan and the Scaling-Up Renewable Energy Programme had clearly defined strategies for mini-grid deployment. Financial constraints, complex implementation strategies, and limited monitoring mechanisms were identified as the main reasons policies are ineffective.
The SREP Disbursement Gap
As of late 2025, only 12.6 percent of SREP funds had been disbursed . The reasons are administrative—slow tax-exemption approvals, late release of government counterpart financing—but the consequence is that projects are delayed, and the 3.5 million Ghanaians without electricity remain in the dark. The Bank’s November 2025 review rated progress as “satisfactory,” but the disbursement rate raises serious questions about whether the 150 additional mini-grids planned for the Afram Plains can be delivered by 2030.
The Renewable Energy Authority Gap
The 2026 Budget Programme Summary notes that the Renewable Energy Directorate currently has only seven civil servants working to ensure the effective delivery of programmes and projects [citation:1 in original energy report]. The government plans to establish a Renewable Energy Authority to address this, but the authority has not yet been operationalised. Without a dedicated agency with staffing, funding, and enforcement authority, policy implementation will continue to lag.
Part 6: The Political and Legal Barrier — Land Litigation and Regulatory Complexity
Renewable energy projects require land—often in contested areas. In Ghana, land litigation and availability issues are significant barriers to renewable energy adoption .
Land Acquisition Challenges
The 44-barrier Delphi study identified “issues related to land litigation and availability” as a key impediment . Securing land for utility-scale solar projects involves navigating customary land ownership systems, multiple claims, and lengthy court processes. For a developer, the time and cost of land acquisition can render a project uneconomical.
Regulatory Complexity and Overlap
Multiple agencies have overlapping jurisdiction over renewable energy projects: the Energy Commission, PURC, EPA, local assemblies, and the Lands Commission all have approval authority. The resulting regulatory complexity creates permitting delays that discourage investment. The Global Renewables Congress report identifies regulatory complexity as a key barrier to renewable energy deployment.
The Feed-in Tariff Gap
The 2025 Delphi study found that a lack of robust incentives, specifically feed-in tariffs, remains a barrier . While Ghana has feed-in tariffs on paper, they are not consistently applied, and the rates offered have not been sufficient to attract significant private investment. Without predictable, bankable tariffs, renewable energy projects cannot secure financing.
Part 7: The Path Forward — What Must Change
Ghana’s renewable energy market will remain underdeveloped until the following structural barriers are addressed:
1. Resolve ECG’s Financial Distress
No amount of policy rhetoric will attract renewable energy investment while the primary off-taker cannot pay its bills. ECG’s financial turnaround—through operational efficiency improvements, loss reduction, and credible private sector participation—is the single most important enabler of renewable energy scale-up.
2. Lift the Shadow of PPA Uncertainty
The government must demonstrate that PPAs signed today will be honoured tomorrow. This requires legislative reforms that make contract renegotiation more difficult for future governments and independent dispute resolution mechanisms that investors trust.
3. Establish and Resource the Renewable Energy Authority
A dedicated agency with adequate staffing, funding, and enforcement authority is a prerequisite for scale. Seven civil servants cannot implement a national renewable energy strategy.
4. Accelerate Grid Modernisation
Transmission and distribution upgrades, battery storage deployment, and smart grid technologies are essential for integrating variable renewable energy. The Akosombo substation fire was a warning. Without grid modernisation, additional renewable capacity cannot be effectively utilised.
5. Develop Local Skills and Maintenance Ecosystems
Ghana must invest in training programmes for renewable energy technicians, engineers, and project managers. Local maintenance capacity is essential for the long-term sustainability of off-grid systems.
6. Simplify Regulatory Approval Processes
A one-stop shop for renewable energy permits would reduce transaction costs and accelerate project timelines. Land acquisition processes must be streamlined, and feed-in tariffs must be made predictable and bankable.
7. Close the Financing Gap with De-risking Mechanisms
The government, in partnership with development finance institutions, must provide de-risking instruments—partial risk guarantees, first-loss provisions, and currency hedging facilities—to attract private capital to renewable energy projects.
ASJ Conclusion
Ghana’s renewable energy market remains underdeveloped not because the country lacks resources or ambition, but because the structural conditions necessary for private investment are absent.
Policy uncertainty—embodied in the 2017–2023 PPA moratorium and the government’s history of contract renegotiation—has damaged investor confidence. Financial barriers—high interest rates, currency volatility, and ECG’s $1.73 billion in unpaid IPP debts—make projects difficult to finance. Institutional dysfunction—bureaucratic agencies, weak legal enforcement, and a Renewable Energy Directorate with only seven staff—slows implementation. Grid fragility prevents the integration of variable renewable energy even when projects are built.
The government has articulated a vision for renewable energy, but vision without execution is merely rhetoric. The 2026 Budget’s commitment to establishing a Renewable Energy Authority and promoting net-metering are positive steps, but they are not sufficient. Without ECG reform, grid modernisation, and credible PPA guarantees, the 10 percent renewable target by 2030 will remain unfulfilled—just as the earlier targets in the Renewable Energy Master Plan remain unfulfilled.
As the Africa Sustainable Energy Centre’s Justice Ohene-Akoto noted, Ghana has the potential not only to achieve energy security but to lead in clean energy across Africa . Realising that potential requires moving from policy documents to implementation, from pilot projects to scale, and from institutional dysfunction to institutional effectiveness. The barriers are well documented. The solutions are well understood. The missing ingredient is execution.
Quick Reference: Barriers to Renewable Energy Adoption in Ghana
| Barrier Category | Specific Barriers | Source |
|---|---|---|
| Policy | PPA moratorium (2017–2023); uncertain regulatory environment; inconsistent feed-in tariffs | |
| Economic/Financial | High commercial interest rates; currency fluctuation risk; limited access to capital; ECG debt ($1.73bn to IPPs) | |
| Institutional | Weak legal enforcement; bureaucratic agencies; Renewable Energy Directorate understaffed (7 civil servants) | |
| Technical | Grid integration challenges; lack of skilled professionals; weak maintenance ecosystems | |
| Political/Legal | Land litigation and availability; regulatory complexity; feed-in tariff gaps | |
| Social | Limited awareness; insufficient training programmes |
Key Statistics:
-
Solar/wind installed capacity: 132 MW (2.3% of total generation)
-
Renewable energy target: 10% by 2030 (excluding large hydro)
-
Required annual addition: ~340 MW per year (2026–2030)
-
Ghana’s solar irradiation: 5–6.5 kWh/m²/day
-
Population without reliable electricity: ~3.5 million
-
ECG debt to IPPs: $1.73 billion (2024)
-
Energy sector total debt: >$3 billion
-
SREP disbursement rate: 12.6% (as of late 2025)
Source: Accra Street Journal
Last Updated on June 6, 2026 by Samuel Kwame Boadu
Disclaimer: Some content on Accra Street Journal may be aggregated, summarized, or edited from third-party sources for informational purposes. Images and media are used under fair use or royalty-free licenses. Accra Street Journal is a subsidiary of SamBoad Publishing Hub under SamBoad Business Group Ltd, registered in Ghana since 2014.
For concerns or inquiries, please visit our Privacy Policy or Contact Page.

Samuel Kwame Boadu is a Ghanaian media entrepreneur and storyteller with a passion for amplifying urban voices and uncovering everyday truths. He is the Editor-in-Chief and Founder of Accra Street Journal, a dynamic digital platform dedicated to capturing the pulse of Ghana’s capital—its people, culture, challenges, business, sports and innovations.