










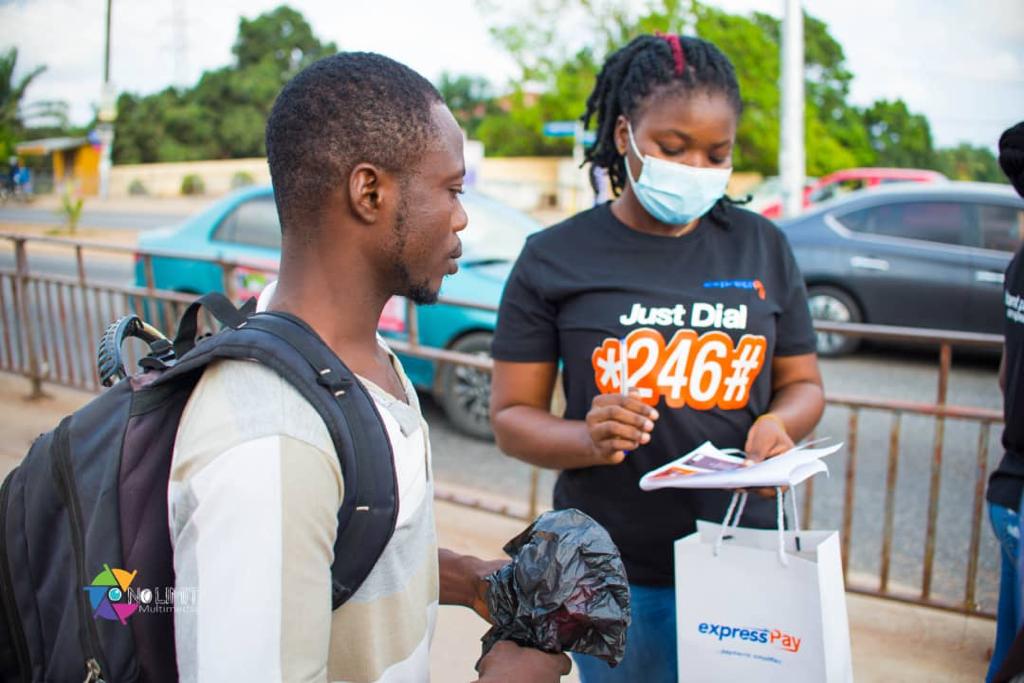

With a PCI-DSS certified platform, a merchant-first business model, and partnerships spanning universities, insurance companies, and government agencies, this 13-year-old fintech has built the transactional backbone for institutions that Zeepay and Hubtel don’t even reach.

Executive Introduction
In Ghana’s rapidly evolving fintech landscape, the loudest names often dominate the headlines. Zeepay grabs attention with its exclusive EMI license and $50 million fundraising. Hubtel claims fame as a payments pioneer with a decade of market presence. But operating in the spaces these giants don’t fully occupy—the institutional payment corridors of universities, insurance companies, and government agencies—is expressPay Ghana Ltd, a quieter but arguably more strategically entrenched fintech .
Founded in 2012, expressPay has spent over a decade building what it calls the “payment gateway of choice” for businesses ranging from educational institutions to insurance companies . Its model is fundamentally different from consumer-facing apps: expressPay provides white-label payment solutions that allow organizations to collect payments through multiple channels—mobile money, card payments, and direct bank transfers—while maintaining their own branding .
📢 GET A DETAILED ARTICLES + JOBS
Join ASJ's WhatsApp Channel and never miss a post or opportunity.
The results speak for themselves. Universities across Ghana rely on expressPay to collect tuition fees. Insurance companies use its platform for premium collections. The platform processes millions of cedis monthly, operating with PCI-DSS certification and robust fraud prevention mechanisms that provide peace of mind for businesses handling sensitive financial transactions .
For investors, business leaders, and technology professionals, expressPay represents a case study in sustainable fintech growth. While many startups chase venture capital and consumer market share, expressPay has quietly built a B2B payment infrastructure business with institutional-grade security, deep integration with both mobile money operators (MTN, AirtelTigo, Telecel) and card schemes (Visa, MasterCard), and a founder with credentials from MIT and Visa who understands both the technology and the regulatory landscape .
This profile examines expressPay’s business model, its white-label merchant strategy, the leadership of Co-Founder and CEO Curtis Vanderpuije, its competitive position relative to Hubtel and Zeepay, and the critical question: can a 13-year-old fintech with modest funding and a B2B focus survive as consumer-facing giants with deeper pockets enter its market? .
Company Overview
Founding Story: From MIT to Accra
expressPay was founded in 2012 by Curtis Vanderpuije, a Ghanaian entrepreneur with an extraordinary academic and professional pedigree . Vanderpuije holds a Master of Engineering (M.Eng.) from the Massachusetts Institute of Technology (MIT), where he studied between 2005 and 2007 . Before founding expressPay, he worked as an Associate Consultant at Bain & Company and as a Senior Associate at Visa—the global payments giant .
This background is crucial to understanding expressPay’s strategic positioning. Unlike many fintech founders who come from software development or banking, Vanderpuije brought deep expertise in payment networks, card scheme operations, and institutional consulting. He understood how Visa and MasterCard worked from the inside, and he understood how large organizations (universities, insurers, government agencies) needed to collect payments .
The company was founded in 2012 and has been operating independently for 13 years . It has not pursued the aggressive venture capital fundraising seen at competitors like Zeepay (which raised $50 million) or Hubtel (which has secured substantial backing). Instead, expressPay appears to have grown organically, building its customer base one institution at a time .
Operations and Footprint
expressPay is headquartered in the Airport Residential Area of Accra, at 12 Senchi Street . The company maintains a second office in Cantonments, Greater Accra Region . It employs between 100 and 200 people .
Key Operational Metrics:
| Metric | Value |
|---|---|
| Founded | 2012 |
| Headquarters | 12 Senchi Street, Airport Residential Area, Accra |
| Employees | 100–200 |
| Estimated Annual Revenue | $3.9 million |
| Operating Status | Independent, privately held |
| Key Leadership | Curtis Vanderpuije (Co-Founder & CEO), Kodjo Hesse (Director) |
Physical Presence:
-
Airport Residential Area Office: 12 Senchi Street, Accra (primary operations)
-
Cantonments Office: Second location in Greater Accra Region
Contact Information:
-
Phone: +233 55 716 6722, +233307000503
-
Email: [email protected]
Leadership: Curtis Vanderpuije and the Executive Team
Curtis Vanderpuije – Co-Founder and Chief Executive Officer
Vanderpuije leads expressPay with a unique combination of technical expertise, institutional experience, and entrepreneurial vision. His career trajectory includes:
-
MIT: Master of Engineering (M.Eng.)
-
Bain & Company: Associate Consultant
-
Visa: Senior Associate—where he gained deep knowledge of payment card operations, network economics, and institutional payment processing
-
expressPay: Co-Founder and CEO since 2012
This background positions Vanderpuije differently from many fintech founders. He understands how large enterprises think about payment collection, how card schemes operate, and how to build compliant, secure payment infrastructure.
Kodjo Hesse – Director
Kodjo Hesse serves as a Director at expressPay, having joined the company in 2012—the same year it was founded . His background includes quantitative development at Citadel Investment Group, Vice President at Merrill Lynch, and Director at Temple Investments . He holds an MSc from the University of Oxford .
Hesse’s experience in quantitative finance and investment banking brings institutional credibility to expressPay’s leadership team.
Key Leadership Team:
| Name | Position |
|---|---|
| Curtis Vanderpuije | Co-Founder & Chief Executive Officer |
| Kodjo Hesse | Director |
| Emmanuel Ossom | Brand and Communications Manager |
| Patrick Larbi | Customer Experience Manager |
| Barbara Appiah | Finance Associate Manager |
The Mobile App: Consumer Face of a B2B Engine
While expressPay’s core business is B2B payment infrastructure, the company maintains a consumer-facing mobile app available on both iOS and Android platforms .
App Features:
The expressPay app allows users to:
-
Send instant money transfers directly to AirtelTigo Money, MTN mobile money, Tigo Cash, Telecel Cash, or to bank accounts
-
Purchase airtime instantly for any network: Airtel, Glo, MTN, AirtelTigo ,Telecel
-
Purchase internet data for 4G and 3G services
-
Pay merchants with instant notification to the merchant
Payment Methods Accepted:
The app accepts:
-
Visa
-
MasterCard
-
MTN Mobile Money
-
AirtelTigo Money
-
Vodafone Cash
Platform Availability:
| Platform | Requirements |
|---|---|
| iOS | Requires iOS 15.0 or later; size 70 MB |
| Android | Available via Google Play Store |
| Mac | Requires macOS 12.0 or later and Apple M1 chip or later |
| Apple Vision | Requires visionOS 1.0 or later |
Languages: English and French
User Review Feedback:
The app has received positive user feedback, with one reviewer noting: “This app is very easy to navigate and use, always top up airtime for friends and family through here and also make mobile money payments to other networks with lowest charge” . The same reviewer suggested adding passcode or fingerprint security features for enhanced protection .
However, the app’s primary function is not to compete with P2P payment apps like Chipper Cash or WorldRemit. Rather, it serves as a demonstration of expressPay’s payment capabilities—a consumer-facing interface that showcases the underlying technology that institutional clients can white-label for their own use .
Business Model: The White-Label Payment Gateway
expressPay’s business model is fundamentally different from consumer-facing fintechs. The company positions itself as the payment gateway of choice for businesses, enabling organizations to collect payments through multiple channels while maintaining their own branding .
The White-Label Strategy
Instead of forcing institutional clients to send their customers to an “expressPay” portal, expressPay offers white-label solutions. A university can collect tuition fees through a payment page that carries the university’s logo, colors, and branding—but the underlying payment processing is powered by expressPay’s infrastructure .
Similarly, an insurance company can offer premium payment portals that reflect its corporate identity, while expressPay handles the complex integration with mobile money operators, card schemes, and banks in the background .
This strategy has several advantages:
-
Brand preservation: Institutional clients maintain their brand identity with their customers
-
Customer trust: Customers pay through familiar channels (their university’s portal, their insurer’s website) rather than an unfamiliar fintech brand
-
Sticky relationships: Once expressPay is integrated into an institution’s systems, switching costs are high
Target Markets: Universities, Insurance Companies, and Government Agencies
expressPay has deliberately focused on institutional segments with recurring, high-volume payment flows:
Educational Institutions
Universities across Ghana rely on expressPay to collect tuition fees . The education sector represents a particularly attractive market because:
-
Tuition payments are large-ticket, high-value transactions
-
Payment volumes are concentrated at the beginning of each semester
-
Students and parents need multiple payment options (mobile money, cards, bank transfers)
-
Universities lack the technical expertise to build their own payment infrastructure
Insurance Companies
Insurance companies use expressPay’s platform for premium collections . This market is attractive because:
-
Premium payments are recurring (monthly, quarterly, annually)
-
Insurance companies need reliable, compliant payment processing
-
Customers expect multiple payment channels
Government Agencies
While specific government clients are not named in public sources, expressPay’s focus on “service providers” and its PCI-DSS certification suggest that government entities—which handle sensitive citizen data and require high-security payment processing—are within its target market .
The Technology Stack: PCI-DSS Certification and Security
expressPay’s competitive moat is not its consumer brand awareness (which is modest) but its institutional-grade security and compliance .
PCI-DSS Certification
expressPay holds PCI-DSS (Payment Card Industry Data Security Standard) certification . This is the global standard for organizations that handle credit card information. Achieving and maintaining PCI-DSS compliance requires:
-
Annual security audits
-
Stringent data protection protocols
-
Regular vulnerability scans
-
Incident response planning
-
Restricted access to cardholder data
For an educational institution or insurance company, partnering with a PCI-DSS certified payment provider is not optional; it is a regulatory requirement. By achieving this certification, expressPay has cleared a compliance hurdle that many fintechs cannot or will not clear.
Fraud Prevention Mechanisms
expressPay has implemented robust fraud prevention mechanisms to protect businesses handling sensitive financial transactions . These include:
-
Real-time transaction monitoring
-
Pattern recognition for suspicious activity
-
Velocity checks (detecting unusually rapid transaction volumes)
-
Integration with card scheme fraud databases
Revenue Streams
While expressPay does not publicly disclose its revenue structure, the B2B payment gateway model typically generates revenue through:
-
Transaction Fees: A percentage of each payment processed (typically 1-3% for cards, lower for mobile money)
-
Setup and Integration Fees: One-time charges for onboarding new institutional clients
-
Monthly or Annual Platform Fees: Subscription fees for access to the payment gateway
-
White-Label Licensing Fees: Premium pricing for fully branded solutions
Estimated Annual Revenue: Based on SignalHire data, expressPay’s annual revenue is estimated between 3.9million[citation:2].With100−200employees,thisyieldsapproximately20,000-39,000 in revenue per employee—lower than Zeepay’s $212,500 per employee figure, reflecting the different business models (B2B service vs. infrastructure scale).
Mobile Money Aggregation
Like its competitors, expressPay aggregates multiple mobile money operators under a single integration. The platform accepts:
-
MTN Mobile Money
-
AirtelTigo Money
-
Vodafone Cash
For a university or insurance company, dealing directly with each mobile money operator would require separate legal agreements, technical integrations, and compliance reviews. expressPay provides a single integration point that connects to all three .
Card Processing
Through its partnership with Visa and MasterCard (Vanderpuije’s former employer), expressPay enables card payments for institutional clients . This is particularly valuable for international students or diaspora customers paying fees or premiums from abroad.
Market Position and Competition
Industry Standing: The Institutional Payment Specialist
expressPay occupies a distinct position in Ghana’s fintech landscape. It is not the largest player by transaction volume—Hubtel likely holds that crown. It is not the most funded—Zeepay’s $50 million exceeds expressPay’s resources by a wide margin . But it may be the most deeply embedded in institutional payment flows.
The company’s focus on white-label solutions for universities, insurers, and government agencies has created a defensible niche. These clients do not switch payment providers frequently; once expressPay is integrated into a university’s student information system, the cost and complexity of migration are substantial.
Competitive Landscape
expressPay competes across multiple fronts in Ghana’s fintech ecosystem.
1. Hubtel – The Established Pioneer
Hubtel is one of Ghana’s most established fintech pioneers, having served the market for over a decade . The company provides comprehensive payment solutions enabling businesses to accept payments through multiple channels, including mobile money, cards, and USSD. Hubtel’s robust SMS and payment API infrastructure powers thousands of businesses across Ghana, processing millions of transactions monthly .
Where expressPay Wins: Deeper specialization in institutional clients (universities, insurers). White-label focus allows clients to maintain their own brand identity.
Where Hubtel Wins: Larger scale, broader merchant base, SMS API capabilities that expressPay does not emphasize.
2. Zeepay – The Infrastructure Player
Zeepay provides mobile financial services including mobile money, remittances, and payment solutions, serving both unbanked and banked populations . Zeepay has raised significantly more funding than expressPay and holds an exclusive EMI license.
Where expressPay Wins: B2B white-label focus; expressPay does not compete for consumer mindshare, allowing it to serve institutional clients without brand confusion.
Where Zeepay Wins: EMI license enables direct issuance of mobile money; deeper cross-border remittance capabilities.
3. Mazumma – The Interoperability Specialist
Mazumma pioneered aggregated mobile money services in Ghana, creating an interoperable platform allowing users to send money across different networks seamlessly . The company has developed robust APIs for businesses to integrate mobile money payments.
Where expressPay Wins: Institutional focus, white-label solutions, PCI-DSS certification.
Where Mazumma Wins: Developer-friendly APIs, interoperability focus.
4. Tap & Hop – The Vertical Player
Tap & Hop focuses on transportation payments, providing contactless smart cards for trotro and taxi rides . This vertical specialization is distinct from expressPay’s horizontal B2B focus.
5. Chipper Cash / Eversend – The Pan-African P2P Players
These companies focus on cross-border P2P transfers and multi-currency wallets, a segment expressPay does not target meaningfully .
Competitive Advantages
1. Institutional Client Lock-In
Universities, insurance companies, and government agencies are sticky clients. Once expressPay is integrated into their payment workflows, switching costs are high. This creates a predictable, recurring revenue stream.
2. PCI-DSS Certification
Not every fintech holds PCI-DSS certification. This compliance milestone is essential for institutions handling cardholder data and serves as a barrier to entry for less sophisticated competitors .
3. White-Label Capability
expressPay’s ability to provide fully branded payment portals allows institutional clients to maintain their own customer relationships. The client’s customer pays the client, not expressPay—a subtle but important distinction for brand-conscious organizations.
4. MIT-Visa Leadership
Curtis Vanderpuije’s background at MIT and Visa brings technical credibility and industry relationships. His Visa experience is particularly valuable for maintaining card processing relationships and understanding scheme compliance requirements .
5. Multi-Channel Integration
expressPay integrates with mobile money operators (MTN, AirtelTigo, Vodafone), card schemes (Visa, MasterCard), and bank transfers under a single API . This reduces integration complexity for institutional clients.
Competitive Disadvantages
1. Limited Consumer Brand Awareness
Unlike Hubtel or Zeepay, expressPay is not a household name. This limits its ability to launch consumer-facing products or benefit from viral growth.
2. Smaller Scale
With estimated annual revenue of approximately 3.9million,expressPayissignificantlysmallerthanHubtel(estimated63.9 million revenue) . This scale disadvantage affects negotiating power with mobile money operators and card schemes.
3. No EMI License
Unlike Zeepay, expressPay cannot issue its own mobile money or hold customer float independently. It must work through partner mobile money operators for settlement .
4. Limited Cross-Border Capability
expressPay’s focus on domestic Ghanaian payments means it lacks the cross-border remittance capabilities of Zeepay, Chipper Cash, or Eversend.
5. Funding Disadvantage
expressPay has not raised the level of venture capital seen at competitors. This limits its ability to invest in aggressive marketing, talent acquisition, or geographic expansion .
expressPay vs. Hubtel vs. Zeepay
| Dimension | expressPay | Hubtel | Zeepay |
|---|---|---|---|
| Founded | 2012 | 2005 (older) | 2017 (newer) |
| Core Model | White-label B2B gateway | Payment API + SMS | EMI license + remittance infrastructure |
| Target Clients | Universities, insurers, government agencies | SMEs, retailers, enterprises | IMTOs, mobile money operators, diaspora |
| Revenue (est.) | $3.9 million | $63.9 million | $34 million (2025) |
| Employees | 100–200 | 500–1000 | 160 |
| Key Certification | PCI-DSS | Not specified | EMI license |
| Funding | Modest | Substantial | $50 million+ |
| Consumer App | Yes (B2B-focused) | Yes | Yes (B2B-focused) |
| CEO Background | MIT, Bain, Visa | Not specified | Entrepreneur |
Technology and Innovation
Payment Gateway Architecture
expressPay’s core technology is its payment gateway—a software platform that connects:
-
Merchants (universities, insurance companies, government agencies) needing to collect payments
-
Payment methods (mobile money, cards, bank transfers)
-
Customers (students, policyholders, citizens)
The gateway handles:
-
Payment orchestration (routing transactions to the appropriate processor)
-
Fraud detection and prevention
-
Settlement and reconciliation
-
Reporting and analytics
White-Label Capability
expressPay’s white-label solution allows institutional clients to:
-
Use their own domain name for payment pages (e.g., pay.university.edu.gh)
-
Apply their own branding (logos, colors, typography)
-
Customize the user experience to match their existing digital properties
-
Maintain customer relationships without third-party branding
This capability is technically complex. The payment gateway must be fully skinnable while maintaining PCI-DSS compliance—a requirement that rules out many off-the-shelf solutions.
API-First Design
expressPay provides API access for institutional clients who wish to build custom integrations. This allows:
-
Direct integration with student information systems
-
Automatic payment reconciliation
-
Real-time payment confirmation
-
Custom reporting
Fraud Prevention
The platform includes proprietary and third-party fraud detection tools:
-
Velocity checking (detecting multiple rapid transactions)
-
IP geolocation analysis
-
Device fingerprinting
-
Pattern recognition algorithms
Mobile Application
The consumer-facing mobile app provides:
-
Instant money transfers to mobile wallets and bank accounts
-
Airtime and data purchases
-
Merchant payments
The app accepts payments via Visa, MasterCard, MTN Mobile Money, AirtelTigo Money, and Vodafone Cash .
Challenges and Risks
No analysis of expressPay is complete without acknowledging the headwinds that accompany its B2B focus.
Risk 1: Competition from Well-Funded Rivals
Hubtel has a larger merchant base and a decade of operating history. Zeepay has $50 million in funding and an exclusive EMI license. Both competitors have the resources to invest in product development, marketing, and price competition in ways that expressPay may struggle to match.
Risk 2: Disintermediation by Mobile Money Operators
MTN, AirtelTigo, and Vodafone could choose to offer their own B2B payment gateways, cutting out third-party aggregators like expressPay. MTN has already launched MTN MoMo API services for businesses, and further expansion into this space would directly compete with expressPay’s core offering.
Risk 3: Margin Compression
As competition intensifies, transaction fees—the primary revenue source for payment gateways—are likely to decline. expressPay’s estimated $3.9 million in annual revenue provides a modest margin for absorbing price competition .
Risk 4: Client Concentration Risk
expressPay’s focus on universities, insurance companies, and government agencies creates concentration risk. The loss of a single major client (e.g., a large university switching to a competitor) could significantly impact revenue.
Risk 5: Limited Geographic Diversification
expressPay operates primarily in Ghana. Unlike Zeepay, which spans 20+ countries, expressPay lacks geographic diversification. A downturn in Ghana’s economy or a regulatory shock would directly affect the company’s entire revenue base.
Risk 6: No EMI License
Zeepay’s EMI license creates a regulatory moat . expressPay, lacking this license, must partner with licensed entities for mobile money issuance and float management. This adds counterparty risk and reduces independence.
Economic and Industry Impact
Education Sector Digitization
expressPay’s role in digitizing tuition payments at Ghanaian universities has accelerated the shift from cash-based fee collection to digital payments. This benefits:
-
Students and parents: No need to carry large amounts of cash to campus
-
Universities: Automated reconciliation reduces administrative burden
-
Financial inclusion: Students without bank accounts can pay via mobile money
Insurance Sector Modernization
By enabling premium collections through multiple digital channels, expressPay has helped modernize Ghana’s insurance industry. Policyholders can now pay premiums via mobile money or cards rather than visiting branch offices with cash.
Employment
expressPay employs 100–200 people directly, providing stable, skilled jobs in Ghana’s technology sector .
The “Gateway Provider” Ecosystem
expressPay’s success demonstrates that a sustainable fintech business in Ghana does not require consumer-facing brand awareness or massive venture capital. The company’s B2B, white-label model proves that supplying infrastructure to institutions can be as valuable as competing for consumer mindshare.
Competitive Pressure for Innovation
expressPay’s presence in the payment gateway space creates competitive pressure on Hubtel, Zeepay, and other players. This competition drives innovation, lower fees, and better service for merchants and consumers.
Future Outlook
As of May 2026, expressPay continues to operate as an independent, privately held fintech with a B2B white-label focus. The company’s future trajectory depends on its ability to defend its institutional client base against better-funded competitors while potentially expanding into new markets or product lines.
The Immediate Agenda
expressPay’s priorities for 2026-2027 are likely to include:
-
Defending institutional client relationships against Hubtel and Zeepay
-
Expanding white-label capabilities to attract new clients in sectors like healthcare, utilities, and religious organizations
-
Enhancing the mobile app with biometric security features (as user reviews have requested)
-
Exploring partnerships with banks to expand payment processing capabilities
-
Maintaining PCI-DSS certification through annual compliance audits
The Bull Case (Optimistic)
-
Institutional lock-in deepens: expressPay’s white-label solutions become deeply embedded in client systems; switching costs become prohibitive for competitors to overcome.
-
New sector expansion: expressPay successfully expands into healthcare (hospital bill payments), utilities (water, electricity), and religious organizations (tithe and offering collections).
-
Strategic partnership with a bank: A Ghanaian bank acquires a minority stake, providing capital and banking license access while expressPay maintains operational independence.
-
Profitability sustains: expressPay’s organic, capital-efficient growth model delivers consistent profitability while competitors burn cash on marketing.
The Bear Case (Pessimistic)
-
Competition erodes market share: Hubtel or Zeepay aggressively target expressPay’s university and insurance clients with subsidized pricing; expressPay loses key accounts.
-
Mobile money operator disintermediation: MTN or Vodafone launch competing B2B payment gateways; expressPay’s aggregation model becomes less valuable.
-
Margin compression accelerates: Transaction fees decline faster than expressPay can reduce costs; profitability disappears.
-
No funding limits growth: expressPay cannot raise capital to invest in product development or sales expansion; the company remains small while competitors scale.
The Verdict
expressPay Ghana Ltd is a classic example of the “quiet fintech”—a company that has built a sustainable, profitable business without chasing venture capital or consumer headlines. Its white-label payment gateway serves institutional clients that larger, better-funded competitors have not fully captured: universities, insurance companies, and government agencies.
The company’s competitive moat is not technology alone—though its PCI-DSS certification and multi-channel integration are significant assets—but institutional relationships. Once a university integrates expressPay into its student information system, the cost and complexity of switching to a competitor are substantial.
The leadership team brings exceptional credentials: Curtis Vanderpuije (MIT, Bain, Visa) and Kodjo Hesse (Oxford, Citadel, Merrill Lynch) . Their backgrounds in institutional finance, payment networks, and quantitative analysis distinguish expressPay from fintechs founded by software engineers alone.
The risks are real. Hubtel has a larger merchant base and deeper pockets. Zeepay has an EMI license and cross-border capabilities. MTN could decide to capture the B2B payment gateway market directly. expressPay’s modest revenue base ($3.9 million estimated) provides limited margin for error .
But the company has survived and grown for 13 years[^7] without the venture capital that fuels so many fintech startups. That longevity is not an accident; it reflects a business model that works, clients that stay, and a leadership team that understands both the technology and the economics of payment processing.
expressPay is not trying to be the largest fintech in Ghana. It is trying to be the most trusted payment gateway for institutions that need reliability, security, and white-label flexibility. And for a growing number of universities, insurance companies, and government agencies, it already is.
Last Updated on May 4, 2026 by Samuel Kwame Boadu
Disclaimer: Some content on Accra Street Journal may be aggregated, summarized, or edited from third-party sources for informational purposes. Images and media are used under fair use or royalty-free licenses. Accra Street Journal is a subsidiary of SamBoad Publishing Hub under SamBoad Business Group Ltd, registered in Ghana since 2014.
For concerns or inquiries, please visit our Privacy Policy or Contact Page.

Samuel Kwame Boadu is a Ghanaian media entrepreneur and storyteller with a passion for amplifying urban voices and uncovering everyday truths. He is the Editor-in-Chief and Founder of Accra Street Journal, a dynamic digital platform dedicated to capturing the pulse of Ghana’s capital—its people, culture, challenges, business, sports and innovations.



