





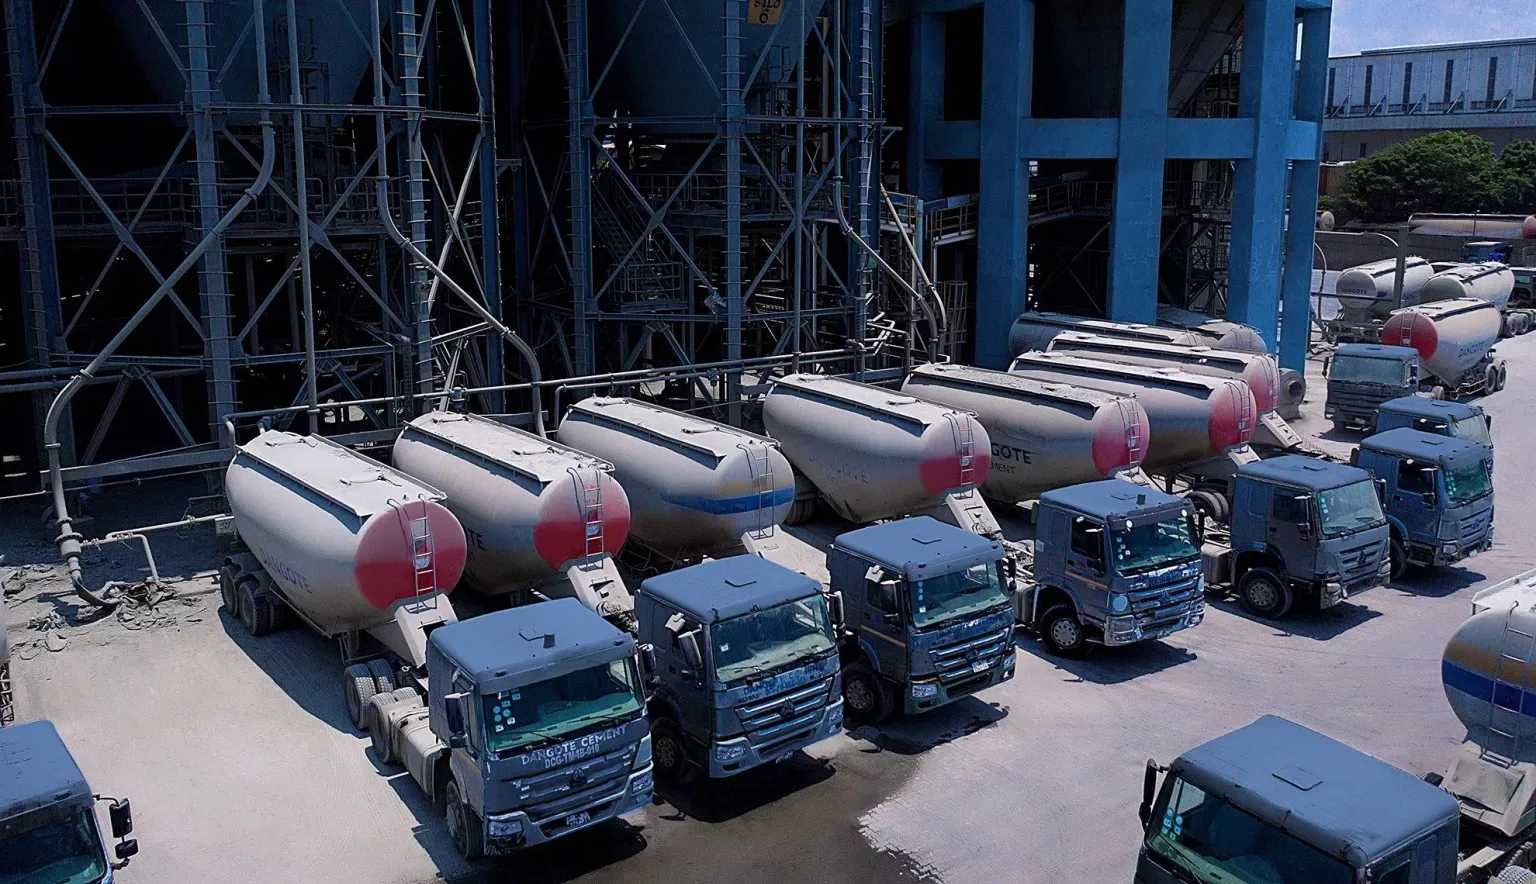
From bulk importer to local grinding giant — the evolution of Africa’s largest cement producer in Ghana
Executive Introduction
Dangote Cement entered Ghana in 2011 as a bulk importer, bagging cement at its Tema terminal and selling into a market dominated by GHACEM . Four years later, in 2015, it commenced operations at its Takoradi grinding plant, a 0.4 million tonnes per annum (Mta) facility that marked its transition from pure importer to local producer . Today, that facility has been upgraded to handle up to 1.5 million tonnes of bulk cement annually, and a new US$100 million, 1.5-million-tonne grinding plant in Takoradi is under development .

Dangote Cement is Africa’s leading cement producer, with production capacity of up to 55 million tonnes per annum across 11 African countries as of 2025 . The parent company reported revenues exceeding US$3 billion in 2025 and is forecast to grow earnings at 12.8% per annum, with earnings per share expected to increase by 13.8% annually . The return on equity is forecast to reach 45% in three years—a level that would place it among the most profitable cement manufacturers globally .
📢 GET A DETAILED ARTICLES + JOBS
Join ASJ's WhatsApp Channel and never miss a post or opportunity.

In Ghana, Dangote holds an estimated 5–11% market share but has publicly stated its ambition to capture 30% of the market within the next few years . This ASJ Industry Analysis report provides a comprehensive analysis of Dangote Cement’s Ghana operations: its corporate structure, production capacity, expansion plans, product strategy, distribution model, competitive positioning, and future outlook within Ghana’s rapidly growing cement market.
Part 1: Corporate Overview — A Pan-African Giant in Ghana
Parent Company Profile
Dangote Cement is a subsidiary of the Dangote Industries Group, a Nigerian conglomerate led by Aliko Dangote, Africa’s richest person. The cement division is the flagship of the Group and has been described as “the largest and leading cement producer in Sub-Saharan Africa” .

| Metric | Value |
|---|---|
| Parent Group | Dangote Industries (Nigeria) |
| Group Target | US$100 billion enterprise by 2030 (Vision 2030) |
| African Presence | 11 countries |
| Production Capacity | 55 million tonnes per annum (2025) |
| 2025 Revenues | >US$3 billion |
| Stock Listing | Nigerian Exchange (NGSE:DANGCEM) |
| Market Cap | ₦13.8 trillion (approx.) |
Sources: ASJ Industry Analysis
Ghana Subsidiary Overview
Dangote Cement Ghana Limited is the local operating entity. The company initially entered the Ghanaian market in 2011 as a bulk importer, bagging cement at its terminal in Tema and selling into the domestic market . The facility has since been upgraded to handle up to 1.5 million tonnes of bulk cement per year .
Key Ghana-specific metrics:
| Metric | Value |
|---|---|
| Year of Entry | 2011 |
| Operational Model | Bulk import terminal + grinding plant |
| Tema Terminal Capacity | 1.5 million tonnes per annum |
| Takoradi Grinding Plant (existing) | 0.4 million tonnes per annum |
| Takoradi Grinding Plant (new) | 1.5 million tonnes per annum (US$100 million investment) |
| Total Ghana Capacity (post-expansion) | ~3 million tonnes per annum |
| Job Creation (direct and indirect) | 5,000+ |
| Estimated Market Share | 5–11% |
| Market Share Target | 30% (within next few years) |
The Pan-African Footprint
Dangote Cement’s scale across Africa gives it strategic advantages that local competitors cannot match. The parent company has integrated factories in seven countries, a clinker grinding plant in Cameroon, and import and distribution facilities for bulk cement in Ghana and Sierra Leone .
Dangote’s African footprint includes :
| Country | Operation Type | Capacity | Estimated Market Share |
|---|---|---|---|
| Nigeria | Integrated factories | 35.3 Mta | Mid-60s |
| Senegal | Integrated factory | 3.0 Mta | 28% |
| South Africa | Integrated factory | 2.8 Mta | Cannot be published |
| Ethiopia | Integrated factory | 2.5 Mta | 34% |
| Zambia | Integrated factory | 1.5 Mta | 34% |
| Tanzania | Integrated factory | 1.5 Mta | 53% |
| Congo | Integrated factory | 1.5 Mta | 20% |
| Cameroon | Clinker grinding | 1.5 Mta | 30% |
| Ghana | Import/grinding | 1.5 Mta | 5% |
| Sierra Leone | Import/distribution | 0.5 Mta | 25% |
| Ivory Coast | Grinding plant | Under development | — |
Part 2: Production Capacity — The Evolution from Importer to Grinder
Phase 1: The Tema Bulk Import Terminal
When Dangote Cement first entered Ghana in 2011, it operated exclusively as an importer. Bulk cement arrived at the Tema terminal, where it was bagged and distributed to the domestic market. The terminal was originally sized at 0.4 million tonnes capacity and has since been upgraded to handle up to 1.5 million tonnes of bulk cement per year .
This model allowed Dangote to enter the market quickly without the capital expenditure required for local grinding facilities—but it also left the company exposed to shipping costs, port delays, and exchange rate volatility.
Phase 2: The Takoradi Grinding Plant (Original)
In 2023, Dangote Cement commenced operation of its 0.4 million tonnes per annum grinding unit in Takoradi . This facility marked the company’s transition from pure importer to local producer and increased Dangote Cement’s total installed capacity to 52 million tonnes across Africa .
The grinding plant produces cement by grinding imported clinker with gypsum and other additives—the same model used by most cement manufacturers in Ghana, including GHACEM.

Phase 3: The US$100 Million Expansion
The most significant development in Dangote Cement’s Ghana operations is the US$100 million, 1.5-million-tonne cement grinding plant under construction in Takoradi . This investment was identified by the Ministry of Trade, Agribusiness and Industry’s audit team as one of the emerging new operations in the industry .
Key facts about the expansion:
| Metric | Value |
|---|---|
| Investment | US$100 million |
| Capacity | 1.5 million tonnes per annum |
| Type | Clinker grinding plant |
| Location | Takoradi, Western Region |
| Status | Under development |
| Total Direct/Indirect Jobs | 5,000+ |
Once completed, Dangote’s total Ghana capacity will increase to approximately 3 million tonnes per annum (1.5 million tonnes from the Tema terminal plus 1.5 million tonnes from the new grinding plant). This will significantly enhance the company’s ability to compete with GHACEM, which will have post-expansion capacity of approximately 3.9 million tonnes (existing 2.4 million tonnes plus 1.5 million tonnes from its new Kumasi plant).
Parent Group’s Continental Expansion
Dangote Cement’s Ghana investments are part of a broader continental expansion strategy. The parent group is targeting a cement production capacity expansion to approximately 90 million tonnes by 2030—a figure Aliko Dangote notes is “50 per cent more than the entire production of Saudi Arabia” .
This expansion is part of the Group’s Vision 2030 strategy, aimed at transforming Dangote Group into a US$100 billion enterprise by 2030 .
Part 3: Product Strategy — The 42.5R Focus
The “Dangote 3X Cement” Grade
Dangote Cement has differentiated itself through product strategy. Unlike GHACEM, which offers both 32.5R and 42.5R grades, Dangote’s Ghana operations focus primarily on the premium 42.5R grade—marketed as “Dangote 3X Cement” .
The 3X meaning: “Xtra strong, Xtra life and Xtra yield” .
The 42.5R grade is described as “the highest that could be acquired in the West African market” . The company’s own marketing claims that a bag of Dangote 3X Cement (42.5R) is “equivalent to one and half bag of the regular cement bag” .
Product Grades Offered
| Grade | Classification | Applications | Available in Ghana |
|---|---|---|---|
| 32.5R CEM II | Lower clinker content + pumice additive | Plastering, low-rise buildings, masonry | No |
| 42.5R (3X) CEM II-AL | Higher clinker content | Most building uses including high-rise, some infrastructure | Yes |
| 52.5 CEM I | Highest clinker content | Major infrastructure (bridges, dams) | No |
Source: ASJ Industry Analysis
Quality Assurance — Academic Validation
A peer-reviewed academic study analyzed the compressive strength of cement from major manufacturers in Ghana, including Dangote, GHACEM, SUPACEM, CIMAF, and Diamond Cement .
Key findings for Dangote 42.5R cement :

| Cement Brand | Grade | Average Compressive Strength (MPa) | C30 Standard (30 MPa) | C40 Standard (40 MPa) |
|---|---|---|---|---|
| Dangote | 42.5R | Not explicitly stated | Exceeds significantly | Approaching |
| GHACEM | 42.5R | 37.9 MPa | ✓ | Near |
| SUPACEM | 42.5R | 37.4 MPa | ✓ | Near |
| Diamond | 42.5R | 35.6 MPa | ✓ | Near |
| CIMAF | 42.5R | 33.5 MPa | ✓ | Below |
The study confirms that all major brands meet international strength standards, with the 42.5R grade consistently exceeding the requirements for normal construction work. Dangote’s 42.5R cement performs comparably to its peers.
Differentiation Challenge
While Dangote’s exclusive focus on 42.5R cement positions the brand as a premium product for high-strength applications, this also means the company does not compete in the 32.5R segment—a significant portion of the market used for plastering and general construction.
This is in contrast to GHACEM, which offers both 32.5R and 42.5R grades, allowing it to serve the entire market spectrum .
Part 4: Distribution Strategy — The 1,000-Truck Fleet
Direct Distribution as Competitive Advantage
Dangote has taken a dramatically different approach to cement distribution in Ghana compared to its competitors. Instead of relying on independent distributors (the model used by GHACEM and others), Dangote has built its own distribution fleet.
The parent company acquired 1,000 trucks from Chinese manufacturer Sino-Truk in July 2016 . This fleet was initially used to transport cement produced in Nigeria to Ghana . The company has since invested over US$80 million in its fleet, including the procurement of additional trucks, as part of its mission “to stimulate Ghanaian consumers of our products” .
Why Dangote bypasses third-party distributors:
According to the company’s Media Relations Manager, Etornam Komla Buami, Dangote decided “to engage in distribution of cement to make it affordable in Ghana as engaging private distribution company could subsequently cause price hikes” .
Benefits of Direct Distribution
| Benefit | Mechanism |
|---|---|
| Lower consumer prices | Eliminates intermediary margins |
| Supply chain control | Direct oversight of delivery times and product quality |
| Independence from transport lobbies | Not subject to strikes or price manipulation by third-party transporters |
| Rapid response to demand fluctuations | Can redeploy fleet to high-demand areas |
The Tema Logistics Hub
From its Tema terminal, Dangote redistributes cement to resellers located in Ghana, as well as to neighbouring countries including Burkina Faso and Mali, where cement is significantly more expensive . This re-export strategy allows Dangote to capture higher margins in markets with less local production capacity.
Integration Across Borders
The fleet strategy is part of a broader spatial strategy. Dangote’s trucks “crisscross the roads of Africa” from Nigeria through Benin and Togo to Ghana, then onwards to Burkina Faso and Côte d’Ivoire . The company now controls “the entire industry,” from production to distribution, making it “completely independent from transporters and their potential nuisance (lobbies and strikes)” .
Part 5: Competitive Positioning — Market Share and Growth Ambition
Current Market Position
Dangote Cement currently holds an estimated 5–11% market share in Ghana . This places it behind market leader GHACEM (estimated 54% share) but competitive with other players including Diamond Cement (~25%) and CIMAF.
Market share estimates for major players :
| Company | Estimated Market Share |
|---|---|
| GHACEM | ~54% |
| Diamond Cement | ~25% |
| Dangote Cement | 5–11% |
| CIMAF | Growing |
| SUPACEM | Growing |
The 30% Market Share Target
Dangote Cement has publicly stated its ambition to capture 30% of the Ghanaian market within the next few years . Achieving this target would require:
-
Significant capacity expansion (already underway with US$100 million Takoradi plant)
-
Aggressive distribution (already enabled by 1,000-truck fleet)
-
Potential pricing pressure (made possible by direct distribution cost savings)
Competitive Advantages
| Advantage | Source |
|---|---|
| Pan-African scale | 55 million tonnes capacity across 11 countries; can cross-subsidise Ghana operations |
| Direct distribution | 1,000-truck fleet eliminates intermediary margins |
| Premium product positioning | Exclusive focus on 42.5R grade for higher strength applications |
| Parent group financial strength | ₦13.8 trillion market cap; US$100 billion enterprise target by 2030 |
| Future export capability | Tema hub already serving Burkina Faso and Mali |
Competitive Disadvantages
| Disadvantage | Constraint |
|---|---|
| No 32.5R product | Does not compete in significant portion of market |
| Clinker import dependence | Exposed to same exchange rate and shipping constraints as GHACEM |
| Lower market share | 5–11% share requires significant growth to challenge GHACEM’s 54% |
The Competitive Landscape
The Ghana cement market is “characterized by a competitive landscape with major players such as Dangote Cement, Ghacem, CIMAF, and Diamond Cement” . The market is driven by “increasing construction activities in both residential and commercial sectors, fueled by urbanization and infrastructure development projects” .
Government initiatives to boost the construction industry, coupled with a growing population and rising investments in real estate, are driving cement demand—but also intensifying competition .
Part 6: Financial Performance and Parent Group Outlook
Parent Group Financials
Dangote Cement’s parent group reported revenues exceeding US$3 billion in 2025 . Analyst forecasts for the parent company project robust growth through 2028 :
| Period | Revenue (₦ million) | Earnings (₦ million) | EPS Growth |
|---|---|---|---|
| 2025 (actual) | 4,306,704 | 1,002,847 | — |
| 2026 (forecast) | 5,070,800 | 1,176,270 | — |
| 2027 (forecast) | 5,765,806 | 1,274,167 | — |
| 2028 (forecast) | 7,124,331 | 1,475,014 | — |
Source: ASJ Industry Analysis
Key growth metrics for the parent company :
| Metric | Forecast |
|---|---|
| Earnings growth (per annum) | 12.8% |
| Revenue growth (per annum) | 14.5% |
| EPS growth (per annum) | 13.8% |
| Return on Equity (3 years) | 45.00% |
Profitability Comparison
Dangote Cement’s financial metrics compare favourably with global peers in the cement manufacturing sector. According to sector analysis, key metrics for Dangote Cement include :
| Metric | Dangote Cement | Sector Average (Weighted) |
|---|---|---|
| Net Margin | 11.82% | 11.82% (equal) |
| EBIT Margin | 18.29% | 18.29% (equal) |
| Return on Equity (ROE) | 14.15% | 14.15% (equal) |
| Return on Assets (ROA) | 6.16% | 6.16% (equal) |
The parent group’s strong financial performance provides the capital base for continued investment in Ghana operations, including the US$100 million Takoradi grinding plant.
Part 7: Challenges and Risks
Clinker Import Dependency
Like all cement manufacturers in Ghana, Dangote depends on imported clinker. This creates exposure to:
| Risk Factor | Mechanism |
|---|---|
| Exchange rate volatility | Clinker priced in US dollars; cedi depreciation raises costs |
| Global freight costs | Shipping rate fluctuations affect landed cost |
| Port congestion | Delays lead to demurrage charges |
| Supply chain disruptions | Global events affect clinker availability |
The Chamber of Cement Manufacturers (COCMAG) has raised concerns about these vulnerabilities, noting that “the cement deficit on the local market could occur at the end of the year 2025” .
Counterfeit and Substandard Cement
The influx of imported bagged cement—primarily from Togo—has created a parallel market for cheaper, often substandard cement . This affects all legitimate manufacturers, including Dangote, by:
-
Undercutting prices in the informal market
-
Potentially eroding consumer trust in cement quality generally
-
Evading taxes, creating unfair competition
The Ministry of Trade, Agribusiness and Industry has been reviewing cement industry regulations to address these challenges .
Competitive Pressure from GHACEM
GHACEM’s response to Dangote’s expansion includes:
-
New US$100 million Kumasi plant (1.5 million tonnes capacity)
-
Export ambition to Burkina Faso (directly competing with Dangote’s re-export strategy)
-
Defensive distributor relationships built over 58 years
Regulatory Environment
The cement industry in Ghana is governed by regulations covering “the registration and licensing of manufacturers of cement and components of cement; the enforcement of applicable standards and guidelines in the siting of cement manufacturing plants; and the establishment and enforcement of measures to govern the operations of cement manufacturing entities” .
Compliance with these regulations—including local content requirements, environmental standards, and quality certification—adds to operational costs.
Part 8: Future Outlook
Short-Term (2026–2027)
-
Completion of Takoradi grinding plant — The US$100 million, 1.5-million-tonne facility is under development and expected to become operational
-
Total capacity increase — Post-completion, Dangote’s Ghana capacity will reach approximately 3 million tonnes annually
-
Distribution expansion — The 1,000-truck fleet will be deployed to maximize market reach
Medium-Term (2027–2030)
-
Market share capture — Dangote aims to reach 30% market share within the next few years
-
Continued pressure on GHACEM — Increased capacity will likely lead to intensified price competition
-
Export expansion — Dangote may strengthen its re-export position to Burkina Faso, Mali, and Côte d’Ivoire
Long-Term (2030+)
-
Parent group expansion — Dangote Cement is targeting 90 million tonnes of continental capacity by 2030
-
Vertical integration potential — The parent group may consider clinker production in Ghana to reduce import dependence
-
AfCFTA opportunity — Ghana’s location could serve as a hub for West African cement exports under the African Continental Free Trade Area
Growth Drivers
The Ghana cement market is projected to grow at a compound annual rate of approximately 6% through 2029 . Key demand drivers include:
| Driver | Description |
|---|---|
| Infrastructure spending | GH¢60 billion Big Push programme |
| Housing deficit | Persistent shortage of affordable housing |
| Urbanisation | Rapid population growth in Accra, Kumasi, and secondary cities |
| 24-Hour Economy Programme | Industrial park development requiring new construction |
| AfCFTA implementation | Need for trade-related infrastructure |
Conclusion: A Challenger on the Rise
Dangote Cement has evolved from a bulk importer with 5% market share to a major producer with a US$100 million grinding plant, a 1,000-truck fleet, and an ambitious target of 30% market share. Its strategy is defined by aggressive capacity expansion, direct distribution, and premium product positioning.
The parent group’s financial strength—₦13.8 trillion market cap, 12.8% annual earnings growth forecast, 45% ROE target—provides the capital base for continued investment in Ghana . Dangote’s 1,000-truck distribution fleet gives it a competitive advantage in logistics that GHACEM’s distributor model may struggle to match .
The challenges are significant: clinker import dependence affects all manufacturers, counterfeit cement undercuts legitimate producers, and GHACEM is not standing still—its own US$100 million Kumasi plant will add 1.5 million tonnes of capacity . The competitive battle between these two giants will define Ghana’s cement industry for the next decade.
For now, GHACEM remains the market leader with 54% share. But Dangote’s trajectory suggests that the gap is closing. The next three to five years will determine whether Dangote can achieve its target of 30% market share—fundamentally reshaping the balance of power in Ghana’s cement industry.
Quick Reference: Dangote Cement Ghana at a Glance
| Dimension | Value |
|---|---|
| Year of Entry | 2011 |
| Tema Terminal Capacity | 1.5 million tonnes per annum |
| Takoradi Plant (existing) | 0.4 million tonnes per annum |
| Takoradi Plant (new) | 1.5 million tonnes per annum (US$100 million) |
| Total Ghana Capacity (post-expansion) | ~3 million tonnes per annum |
| Estimated Market Share | 5–11% |
| Market Share Target | 30% |
| Product Grade | 42.5R only (not 32.5R) |
| Distribution Fleet | 1,000+ trucks |
| Job Creation | 5,000+ direct and indirect |
| Parent Group Capacity | 55 million tonnes across 11 countries |
| Parent Group Revenue (2025) | >US$3 billion |
| Parent Group Earnings Growth Forecast | 12.8% per annum |
Source: Accra Street Journal
Last Updated on June 9, 2026 by Samuel Kwame Boadu
Disclaimer: Some content on Accra Street Journal may be aggregated, summarized, or edited from third-party sources for informational purposes. Images and media are used under fair use or royalty-free licenses. Accra Street Journal is a subsidiary of SamBoad Publishing Hub under SamBoad Business Group Ltd, registered in Ghana since 2014.
For concerns or inquiries, please visit our Privacy Policy or Contact Page.

Samuel Kwame Boadu is a Ghanaian media entrepreneur and storyteller with a passion for amplifying urban voices and uncovering everyday truths. He is the Editor-in-Chief and Founder of Accra Street Journal, a dynamic digital platform dedicated to capturing the pulse of Ghana’s capital—its people, culture, challenges, business, sports and innovations.