










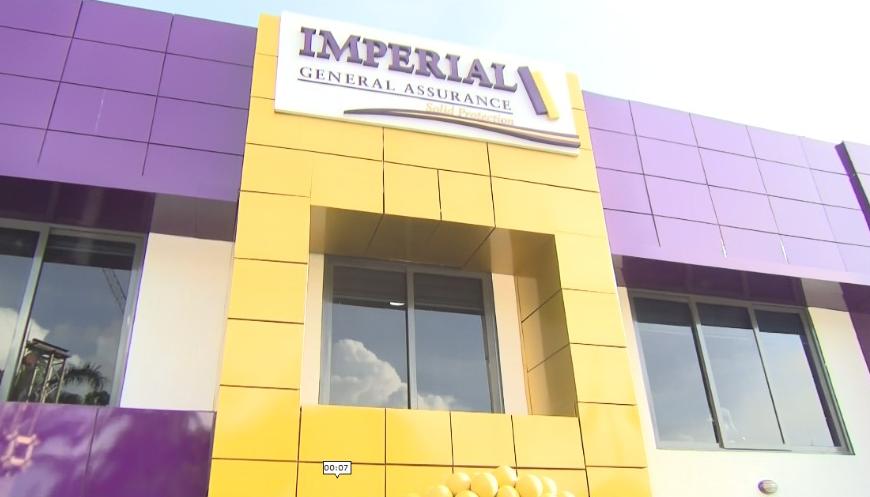

For three consecutive years, this wholly-owned Ghanaian non-life insurer has been named the fastest-growing in the country. With a new Managing Director at the helm, a disruptive Collision Insurance product bridging the gap between Third Party and Comprehensive cover, and a place among Ghana‘s top 100 companies, it is proving that innovation and agility can outrun even the most entrenched competitors.

Executive Introduction
In Ghana‘s general insurance landscape, talk of “fastest growing” often translates into aggressive marketing spend or unsustainable discounting. But when Imperial General Assurance was named Fastest Growing Insurance Company of the Year at the Ghana Insurance Awards for the third consecutive year in 2025—following wins in 2023 and 2024—the industry took notice. This was not a flash in the pan. It was a pattern .
Founded in 2012, Imperial General Assurance is a wholly-owned Ghanaian company licensed by the National Insurance Commission (NIC) to underwrite non-life business . It operates from a head office in the upscale Labone district of Accra and maintains branch offices in six strategic locations: Tema, Spintex, Dawhenya, Weija, Kumasi, and Takoradi .
📢 GET A DETAILED ARTICLES + JOBS
Join ASJ's WhatsApp Channel and never miss a post or opportunity.
The company‘s meteoric rise is anchored on two pillars: product innovation and operational leadership. In 2025, it introduced Collision Insurance, a market-disrupting product that sits between Third Party and Comprehensive cover. It is the first general insurer in Ghana to offer life insurance and hospitalisation benefits on a motor policy . This innovation won it the Product Innovation Award (General Insurance) at the 2025 Ghana Insurance Awards.
Leadership has been a point of strength and recent transition. The company‘s remarkable growth trajectory was set under the tenure of Robert Wugah as Managing Director, who drove Imperial to unprecedented profitability . Wugah has since moved on to Best Assurance. In August 2024, Harry E. B. Ofori-Attah, a seasoned Chartered Insurer with two decades of experience across Enterprise Insurance and Enterprise Life, took over as Managing Director .
For corporate risk managers, insurance brokers, and competitors, Imperial General represents a case study in agile underwriting and segment specialisation. It is not the largest insurer by asset base, but its ability to identify gaps in the market (Collision Insurance) and execute rapidly has made it a formidable mid-tier contender.
This ASJ profile examines the 2012 founding, the 2024 leadership handover from Wugah to Ofori-Attah, the innovative Collision Insurance product, the company‘s wins at the Ghana Insurance Awards, its ranking as 44th on the Ghana Club 100, and the critical question: Can Imperial General sustain its “fastest growing” momentum as the market consolidates and larger players begin copying its product innovations?
Company Overview
The Genesis: A Wholly Ghanaian Insurer (2012)
Imperial General Assurance Company Limited was incorporated in 2012 as a wholly-owned Ghanaian business, licensed by the National Insurance Commission (NIC) to transact general (non-life) insurance .
From its inception, the company positioned itself as a general business insurer, providing flexible risk solutions for both corporate and individual clients. Unlike composite insurers, Imperial General focuses exclusively on non-life products: Motor, Accident, Fire, Bond, Engineering, and Marine Cargo insurance .
It operates from its head office at No 10 1st Norla Street, Labone, Accra, with additional branches in Tema, Spintex, Dawhenya, Weija, Kumasi, and Takoradi, as well as agency offices across the country .
The Management Transition: From Wugah to Ofori-Attah (2024)
The Turnaround Architect: Robert Wugah
Imperial General‘s extraordinary growth trajectory was engineered under the leadership of Robert Wugah, who served as Managing Director . Under his stewardship, the company experienced “remarkable growth and profitability in the last two years” (relative to the pre-2025 period). Wugah brought deep expertise in strategy, general management, insurance underwriting, reinsurance, and claims management, holding an Executive MBA from the University of Ghana Business School .
The success under Wugah is well-documented. He led Imperial General to become the third consecutive winner of the Fastest Growing Insurance Company of the Year award at the Ghana Insurance Awards .
The New Captain: Harry E. B. Ofori-Attah (August 2024)
In August 2024, Imperial General appointed Harry E. B. Ofori-Attah as its new Managing Director, effective August 1, 2024 . Prior to his appointment, Ofori-Attah served as Deputy Managing Director and later Acting Managing Director of the company.
The Enterprise Lineage:
Ofori-Attah brings 20 years of extensive experience across both non-life and life insurance markets. His career trajectory is particularly noteworthy:
| Role | Organisation |
|---|---|
| Senior Client Relations Executive (Corporate Workgroup) | Enterprise Insurance |
| Branch Operations Manager (Takoradi) | Enterprise Insurance |
| Senior Manager, Corporate Business, Business Retention & Specialist Business | Enterprise Insurance |
| Senior Manager, Corporate Business | Enterprise Life |
At Enterprise Insurance, Ofori-Attah was pivotal in underwriting the company’s first aviation risk—a testament to his technical underwriting capability .
Professional Credentials:
-
Chartered Insurance Professional (CIP) – Insurance Institute of Canada
-
Fellow of the Chartered Insurance Institute of Ghana (FCIIG)
-
BSc in Natural Resources Management – Kwame Nkrumah University of Science and Technology
-
Law degree – GIMPA
-
Executive MBA in Management – KNUST
-
Graduate, University of Stellenbosch Leadership Development Program
-
Specialised training, Swiss Re Academy (Engineering & Marine Cargo underwriting)
Academic Contribution:
Since 2008, Ofori-Attah has served as an adjunct lecturer at the Ghana Insurance College, helping to train the next generation of insurance professionals. He is described as a “blue ocean thinker,” passionate about innovation, strategic thinking, and business retention .
The Board Appointments:
Alongside Ofori-Attah‘s elevation, Imperial General appointed two new directors to its board:
-
David Boafo – Acting Board Chairman
-
Stephen Nketia Kyere – Management and Finance Consultant
-
William Amokona-Yeboah – Development Consultant
Operations and Footprint
Head Office:
No 10 1st Norla Street, Labone, Accra, Ghana
Branch Network:
| Branch | Location |
|---|---|
| Tema | Greater Accra |
| Spintex | Greater Accra |
| Dawhenya | Greater Accra |
| Weija | Greater Accra |
| Kumasi | Ashanti Region |
| Takoradi | Western Region |
Workforce:
Imperial General employs between 51–200 people (LinkedIn data), with Crustdata reporting an approximate headcount of 80 as at Q2 2025 (year-over-year headcount growth of 3.89%) .
The Glory Years: Three-Time Fastest Growing Winner
Imperial General Assurance‘s defining characteristic is its sustained recognition as Ghana‘s fastest-growing insurance company.
Ghana Insurance Awards: A Three-Peat
The company was adjudged Fastest Growing Insurance Company of the Year at the Ghana Insurance Awards for three consecutive years:
| Year | Award | Organiser |
|---|---|---|
| 2023 | Fastest Growing Insurance Company | Ghana Insurance Awards |
| 2024 | Fastest Growing Insurance Company | Ghana Insurance Awards |
| 2025 | Fastest Growing Insurance Company | Ghana Insurance Awards |
In 2025, the company also won the Product Innovation Award (General Insurance) for its Collision Insurance product .
Speaking on the recognition, Romeo Adzah (Ag. Head of Corporate Affairs) stated: “Innovation is one of our core values, and as a business in tune with the evolving needs of our customers and the insurance industry, we keep innovating by showing leadership to meeting their demands” .
Ghana Club 100: 44th Among Top Companies
Imperial General Assurance made its maiden entry into the Ghana Club 100 list—a ranking of the top 100 companies in Ghana by the Ghana Investment Promotion Centre (GIPC)—in 2023.
The company was ranked No. 44 overall and placed 3rd in the insurance sector at the 20th anniversary commemoration of the Ghana Club 100 Awards .
The company‘s official statement emphasised its commitment as: “an indigenous insurance company, to be recognised for our pursuit of excellence in providing risk solutions to protect our clients” .
“Most Promising” Start
Imperial General‘s potential was recognised early. At the 5th Ghana Insurance Awards (2022), the company won Most Promising Insurance Company of the Year, a precursor to its “Fastest Growing” run .
Membership & Affiliations
-
African Insurance Organisation (AIO)
-
Ghana Club 100
-
Member of the NIC (licensed non-life insurer)
Business Model: The General Insurance Specialist
Imperial General underwrites only non-life (general) insurance. It offers a range of flexible insurance solutions for both corporate and individual markets.
Product Portfolio
| Category | Specific Products |
|---|---|
| Motor | Comprehensive, Third Party, Collision Insurance |
| Accident | Personal and Group Accident |
| Fire | Residential, Commercial, Industrial |
| Bond | Bid Bonds, Performance Bonds |
| Engineering | Contractors All Risks, Machinery Breakdown |
| Marine | Cargo Insurance |
| Special Risks | (to be confirmed) |
The Game-Changer: Collision Insurance
In 2025, Imperial General launched Collision Insurance, described as a “bridge between Third Party and Comprehensive insurance” .
The Gap It Fills:
-
Third Party Insurance covers damage to other people‘s property or injury to other people. It does NOT cover your own vehicle.
-
Comprehensive Insurance covers both Third Party liabilities AND damage to your own vehicle.
The problem? Comprehensive insurance can be expensive. Third Party leaves you exposed to repair costs for your own car. Collision Insurance is the middle ground: it gives the insured protection to repair their damaged car parts after an accident.
The Innovation:
Imperial General is the first general insurance company in Ghana to introduce life insurance and hospitalisation benefits on motor insurance within this Collision Insurance product .
As Romeo Adzah explained: “We believe Third Party insurance is no longer enough, every policy buyer deserves protection, not just third parties” .
Distribution Channels
Imperial General distributes through:
-
Direct Sales Force – Corporate and individual clients served directly
-
Broker and Agent Network – Independent intermediaries
-
Branch Network – Six physical branches
-
Agency Offices – Across the country
Market Position and Competition
Industry Standing: The Upwardly Mobile Mid-Tier
Imperial General is not among the top 10 non-life insurers by claims payout—Activa (GHS 223 million), Star (GHS 217 million), and Enterprise (GHS 201 million) dominate that table. However, the company‘s growth trajectory suggests it is moving up the ranks.
Key Differentiators:
| Dimension | Imperial General | Market Leaders |
|---|---|---|
| Claims Volume | Smaller, but growing | Very large |
| Product Innovation | Collision Insurance (a first in Ghana) | Typically follow |
| Growth Rate | Fastest in sector (3 years running) | Established, slower |
| Risk Profile | General non-life specialist | Diversified portfolios |
| Brand Heritage | 13 years (founded 2012) | 50-100+ years |
The “Fastest Growing” Context
The “Fastest Growing” award is significant because it measures percentage growth in premium income, not absolute size. A small company can achieve higher percentage growth than a large one. However, winning it three years in a row suggests that Imperial General has successfully built a scalable model for sustained growth—not just a one-year spike.
Competitive Advantages
1. First-Mover in Collision Insurance
By launching Collision Insurance with hospitalisation benefits, Imperial General created a new market segment. Competitors will eventually copy the product, but Imperial has the advantage of brand association with this innovation.
2. Strong Underwriting Leadership
MD Harry Ofori-Attah‘s experience underwriting Enterprise‘s first aviation risk and his Swiss Re Academy training in engineering and marine cargo give Imperial General specialised underwriting capability that many mid-tier insurers lack .
3. Agility
As a private, wholly-owned Ghanaian company, Imperial General can make product decisions faster than larger, more bureaucratic competitors.
4. Growing Branch Network
Six branches spanning Accra, Tema, Kumasi, and Takoradi provide regional reach. The company continues to open agency offices to expand distribution.
5. Recognition as a Top 100 Company
Ranked 44th on the Ghana Club 100 and 3rd in the insurance sector, Imperial General has credibility with corporate clients .
6. Risk Diversification
The company insures a “highly diversified risk portfolio,” reducing exposure to any single sector .
Competitive Disadvantages
1. Lower Claims Volume Than Top Tier
For large corporate clients, claims-paying scale is a proxy for reliability. Imperial General cannot yet match the claims volumes of Activa, Star, or Enterprise.
2. Limited Life License
Imperial General is a non-life specialist. It cannot cross-sell life insurance (personal accident is not life assurance). This limits its ability to offer bundled solutions.
3. Youth Compared to Established Insurers
At 13 years old (founded 2012), Imperial General is still building its claims history. Large corporate clients often prefer insurers with 20-30+ years of track record.
4. No Public GCR Rating
Imperial General has not published a GCR rating. For multinational corporations, a rating is often a prerequisite for consideration.
5. Leadership Transition Risk
The change from Robert Wugah (the architect of the high-growth phase) to Harry Ofori-Attah occurred in August 2024. While Ofori-Attah brings strong credentials, leadership transitions carry execution risk.
6. Concentration in Accra
While the company has branches in Kumasi and Takoradi, its strongest presence remains in the Greater Accra region. Compared to truly national insurers like Enterprise, its footprint is smaller.
Technology and Innovation
Underwriting Technology
Imperial General leverages advanced technology to provide a “superior customer experience.” The company‘s website highlights investments in technology to reduce customer anxiety and exceed expectations .
Collision Insurance: A Product Innovation Case Study
The development of Collision Insurance demonstrates Imperial General‘s customer-centric product development process:
| Step | Action |
|---|---|
| Market Gap | Identified that Third Party cover leaves drivers exposed to repair costs |
| Customer Research | Recognised that customers needed “extra protection” between Third Party and Comprehensive |
| Product Design | Created Collision Insurance covering own vehicle damage after accident |
| Innovation | Added life insurance and hospitalisation benefits (first in Ghana for a motor policy) |
| Launch | 2025 – won Product Innovation Award |
Claims Processing
While specific claims settlement times are not publicly detailed, the company‘s reputation for “amazing insurance service experience” suggests efficient claims processing.
Future Technology Ambitions
The company is “committed to continuous innovation, aiming to become a world-class brand and set disruptive standards that delight customers and stakeholders” .
Potential technology investments (inferred):
-
Online policy purchase
-
Digital claims reporting
-
Mobile app development
Challenges and Risks
Imperial General Assurance‘s growth is impressive, but sustainability requires navigating several headwinds.
Risk 1: Copycat Competition for Collision Insurance
Imperial General has a first-mover advantage with Collision Insurance. However, larger competitors (Activa, Star, Enterprise) have the balance sheet to quickly replicate the product and the distribution network to outmarket Imperial. The company must continue innovating to stay ahead.
Risk 2: Maintaining the “Fastest Growing” Title
The company has won the award for three consecutive years. Winning a fourth consecutive title becomes increasingly difficult as the base grows. The company may need to moderate its growth expectations and focus on profitability (a different metric).
Risk 3: Leadership Transition Delivery
Harry Ofori-Attah took over as MD in August 2024 . While he has strong credentials (Enterprise Insurance, Enterprise Life), he must now deliver financial results. The transition from a celebrated outgoing MD (Wugah) is always challenging.
Risk 4: Economic Headwinds
-
Inflation: Claims costs (repairs, replacements) rise with inflation; premiums are fixed.
-
Cedi Depreciation: Reinsurance costs in foreign currency increase, compressing margins.
-
Interest Rates: Investment income from fixed-income securities fluctuates.
Risk 5: Competition from Market Leaders
Enterprise, Activa, and Star Assurance have far larger claims budgets and agent networks. If any of them decide to compete aggressively in Imperial General‘s SME and retail segments, the company could face margin pressure.
Risk 6: Cap on Single Risk Retention
As a mid-tier insurer, Imperial General‘s capacity for very large risks (e.g., insuring a large industrial facility) is limited by its balance sheet. It relies on reinsurance for large exposures. If reinsurance markets harden, the company may be unable to quote competitively.
Risk 7: Employee Retention
Imperial General employs approximately 80 people . Its growth depends on retaining talent (underwriters, claims adjusters, sales agents). The market for experienced insurance professionals is competitive.
Economic and Industry Impact
Insurance Penetration in Ghana
Ghana‘s insurance penetration remains stubbornly low—below 2% of GDP, far lower than the African average of 3% . Imperial General‘s affordable Collision Insurance product is explicitly designed to bring more drivers into the formal insurance net.
Financial Inclusion
By introducing a product that offers “extra protection” at a lower price point than Comprehensive insurance, Imperial General makes it easier for drivers to upgrade from Third Party cover. This increases the overall pool of insured vehicles and reduces the number of uninsured drivers on the road.
Employment
Imperial General directly employs approximately 80 people and supports a broader ecosystem of agents and brokers across its branch network.
Foreign Direct Investment (FDI) Signal
The company‘s recognition as a Ghana Club 100 company and its membership in the African Insurance Organisation signal that Ghanaian-owned insurers can compete at a continental level.
Product Innovation as Market Discipline
Imperial General‘s Collision Insurance has forced the entire industry to reconsider the adequacy of Third Party cover. Competitors will need to respond with their own innovations or risk losing market share. This competitive pressure ultimately benefits consumers.
Future Outlook
As of May 2026, Imperial General Assurance has established itself as Ghana‘s fastest-growing non-life insurer. The challenge is no longer growth; it is sustaining growth while maintaining underwriting profitability.
The Immediate Agenda (2026-2027)
-
Deepen Collision Insurance Market Share: Capitalise on the first-mover advantage before competitors launch copycat products.
-
Expand Regional Branch Network: Open additional branches in the Northern Region (Tamale) and other underserved areas.
-
Launch Digital Claims Reporting: Develop a mobile app or web portal for customers to report claims and track progress.
-
Seek GCR Rating: Publishing a rating would open doors to large corporate clients and multinationals.
-
Maintain Ghana Club 100 Status: Continue to qualify for the top 100 companies ranking.
-
Sustain the “Fastest Growing” Title (or transition to profitability focus): The company may need to decide whether to continue pursuing growth or to prioritise profitability.
The Bull Case (Optimistic)
-
Collision Insurance Disrupts the Motor Market: The product captures significant market share from both Third Party (downgraders) and Comprehensive (price-sensitive upgraders). Imperial General becomes known as the “Collision Insurance company.”
-
Ofori-Attah‘s Experience Pays Off: The new MD‘s Enterprise Insurance experience (including the first aviation risk) and his Swiss Re training attract new large corporate clients to Imperial General.
-
Branch Expansion Drives Premium Growth: New branches in Tamale and other regions double the company‘s geographic footprint, driving sustained double-digit growth.
-
GCR Rating Attracts Corporate Clients: A ‘B+‘ or ‘A-‘ rating opens the door to multinational and large Ghanaian enterprise clients, diversifying the book away from mass-market motor.
-
Four-Peat at Ghana Insurance Awards: Imperial General wins a fourth consecutive Fastest Growing Insurance Company award, cementing its reputation.
The Bear Case (Pessimistic)
-
Competitors Clone Collision Insurance: Enterprise or Activa launch competing products with lower pricing, eroding Imperial‘s first-mover advantage.
-
Growth Rate Moderates: Winning the “fastest growing” title for three years sets a high bar. Inevitably, growth moderates; the company loses the award to a smaller, newer entrant. Investor and staff morale dip.
-
Economic Downturn Stresses Portfolio: High inflation and cedi depreciation increase claims costs. Imperial General, having grown rapidly, may find its underwriting reserves insufficient.
-
Leadership Transition Stumbles: Ofori-Attah struggles to fill the shoes of Robert Wugah; strategic drift follows.
-
Employee Turnover: Competitors poach key staff who were instrumental in Imperial‘s growth.
The Verdict
Imperial General Assurance has achieved in 13 years what many insurers fail to achieve in 50. Three consecutive “Fastest Growing Insurance Company” titles, a Top 100 ranking in Ghana (44th overall), and the disruptive Collision Insurance product have established it as a formidable mid-tier contender .
The 2024 leadership transition to Harry Ofori-Attah is a test of institutional resilience. The company has moved from a high-growth phase (under Wugah) to a consolidation and innovation phase (under Ofori-Attah). Ofori-Attah‘s deep technical underwriting experience—he underwrote Enterprise‘s first aviation risk and trained at Swiss Re—suggests that the focus will shift toward underwriting quality and risk selection, not just premium growth .
For the Ghanaian motorist who finds Comprehensive insurance too expensive but knows Third Party leaves them exposed, Imperial General offers a compelling solution. For the corporate client looking for a responsive, innovative insurer, Imperial General brings agility that the market leaders lack.
The company‘s greatest risk is not failure—it is complacency. The “Fastest Growing” title must not become an end in itself. Growth without profitability is vanity; growth with poor underwriting is bankruptcy. If Imperial General can maintain underwriting discipline while scaling Collision Insurance and expanding its branch network, it will continue to be a force in Ghana‘s non-life market.
Imperial General Assurance is not trying to be the largest insurer in Ghana. It is trying to be the most innovative. And by that measure, it has already succeeded.
FAQ SECTION
1. Is Imperial General Assurance a Ghanaian-owned company?
Yes. Imperial General Assurance is a wholly-owned Ghanaian company, licensed by the National Insurance Commission (NIC) as a general business insurer. It was founded in 2012 .
2. Who is the Managing Director of Imperial General Assurance?
The Managing Director is Harry E. B. Ofori-Attah, appointed effective August 1, 2024. He previously served as Deputy Managing Director and Acting Managing Director of the company .
3. Who was the previous Managing Director?
The previous Managing Director was Robert Wugah, a Chartered Insurer who led Imperial General to unprecedented growth and profitability, earning the company three consecutive “Fastest Growing Insurance Company” awards .
4. What makes Imperial General Assurance’s Collision Insurance unique?
Collision Insurance is a “bridge between Third Party and Comprehensive insurance” that gives the insured protection to repair their damaged car parts after an accident. Imperial General is the first general insurance company in Ghana to introduce life insurance and hospitalisation benefits on a motor insurance policy .
5. How many awards has Imperial General Assurance won?
Imperial General has won the Fastest Growing Insurance Company of the Year award at the Ghana Insurance Awards for three consecutive years (2023, 2024, and 2025). It also won the Product Innovation Award (General Insurance) in 2025 for its Collision Insurance product. In 2022, it won Most Promising Insurance Company of the Year .
6. Is Imperial General Assurance listed among Ghana‘s top companies?
Yes. The company ranks 44th on the Ghana Club 100 (list of top 100 companies in Ghana by GIPC) and placed 3rd in the insurance sector at the 20th anniversary of the awards. It made the list on its maiden application .
7. What is Harry Ofori-Attah‘s background?
Harry Ofori-Attah brings 20 years of experience. He was a Senior Manager at Enterprise Insurance and Enterprise Life, was pivotal in underwriting Enterprise‘s first aviation risk, and has training from the Swiss Re Academy in Engineering and Marine Cargo underwriting. He holds the Chartered Insurance Professional (CIP) designation from Canada .
8. Where is Imperial General Assurance headquartered?
The company‘s head office is located at No 10 1st Norla Street, Labone, Accra, Ghana .
9. How many branches does Imperial General Assurance have?
The company operates branches in Tema, Spintex, Dawhenya, Weija, Kumasi, and Takoradi, plus agency offices across the country .
10. What types of insurance does Imperial General Assurance offer?
The company offers non-life (general) insurance products including Motor Insurance, Accident Insurance, Fire Insurance, Bond Insurance, Engineering Insurance, and Marine Cargo Insurance .
11. Is Imperial General Assurance a member of any industry associations?
Yes. The company is a member of the African Insurance Organisation (AIO) and the Ghana Club 100 .
12. How does Imperial General Assurance‘s Collision Insurance compare to Third Party?
Third Party Insurance covers damage you cause to other people‘s property or injury to other people—it does NOT cover your own vehicle. Collision Insurance provides protection to repair your own damaged car parts after an accident, plus additional hospitalisation and life benefits, at a price point between Third Party and Comprehensive .
QUICK FACTS BOX
| Item | Details |
|---|---|
| Founded | 2012 |
| Headquarters | No 10 1st Norla Street, Labone, Accra |
| Industry | Non-Life / General Insurance |
| Services | Motor, Accident, Fire, Bond, Engineering, Marine Cargo Insurance |
| Ownership | Wholly Ghanaian-owned, privately held |
| Founding MD | Robert Wugah (former) |
| Current MD | Harry E. B. Ofori-Attah (appointed August 1, 2024) |
| Employees | 51–200 (approx. 80 reported) |
| Branches | Tema, Spintex, Dawhenya, Weija, Kumasi, Takoradi |
| Market Position | Fastest-growing non-life insurer (3 consecutive years) |
| Key Award | Fastest Growing Insurance Company of the Year (2023, 2024, 2025) |
| Key Innovation | Collision Insurance (bridge between Third Party and Comprehensive) |
| Ghana Club 100 Rank | 44th (maiden entry; 3rd in insurance sector) |
| Industry Memberships | African Insurance Organisation (AIO) |
| Regulator | National Insurance Commission (NIC) |
| Website | imperialgeneral.com |
Last Updated on May 6, 2026 by Samuel Kwame Boadu
Disclaimer: Some content on Accra Street Journal may be aggregated, summarized, or edited from third-party sources for informational purposes. Images and media are used under fair use or royalty-free licenses. Accra Street Journal is a subsidiary of SamBoad Publishing Hub under SamBoad Business Group Ltd, registered in Ghana since 2014.
For concerns or inquiries, please visit our Privacy Policy or Contact Page.

Samuel Kwame Boadu is a Ghanaian media entrepreneur and storyteller with a passion for amplifying urban voices and uncovering everyday truths. He is the Editor-in-Chief and Founder of Accra Street Journal, a dynamic digital platform dedicated to capturing the pulse of Ghana’s capital—its people, culture, challenges, business, sports and innovations.



