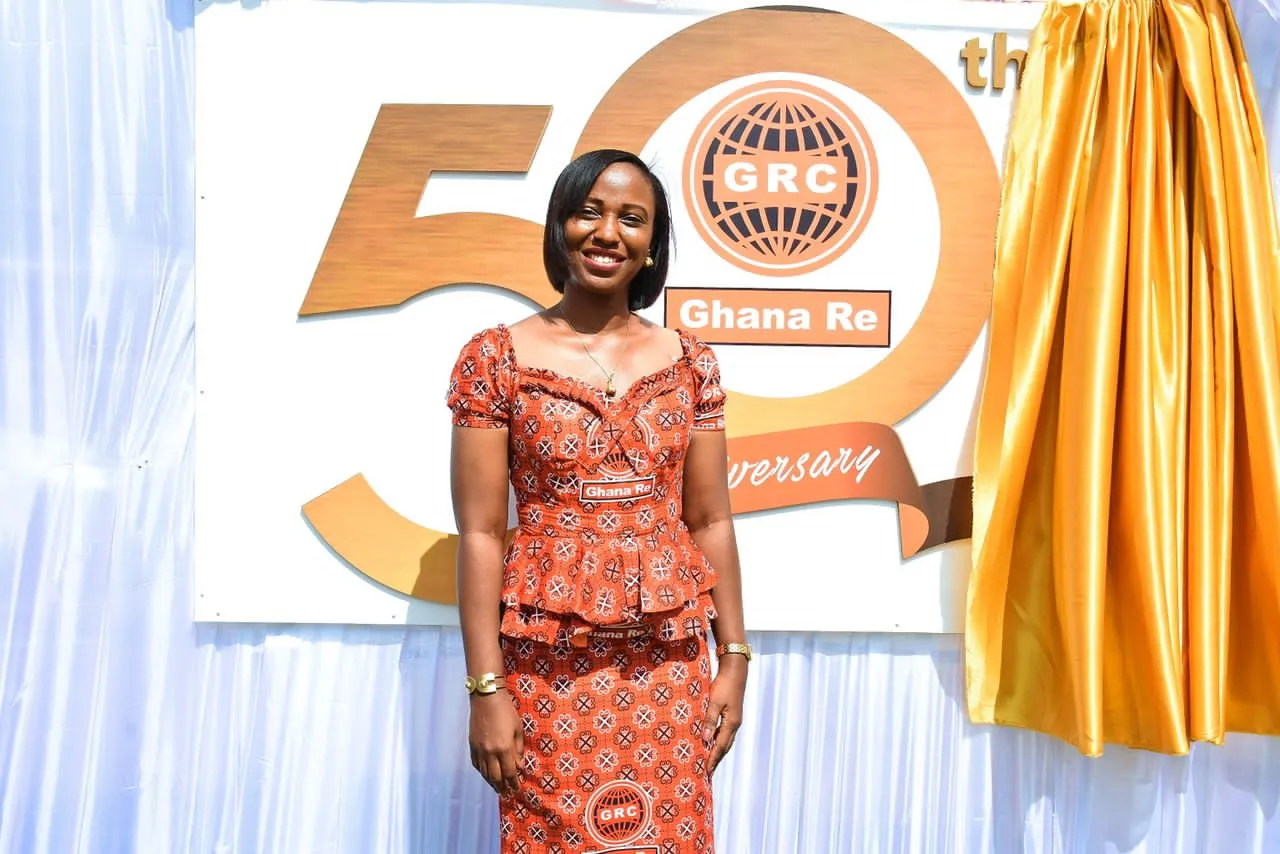
With a 2024 profit collapse (down 63%), a new Managing Director from Donewell, a board chaired by a respected governance expert, a strategic office in Morocco, and a imminent listing on the Ghana Stock Exchange, this state-owned reinsurer is attempting the most consequential pivot in its 50+ year history—from a state-owned enterprise to a publicly traded Pan-African powerhouse.
Executive Introduction
In Ghana‘s financial services landscape, there are companies that dominate headlines through aggressive marketing, and there are institutions that operate silently in the background—underwriting the risks that make the entire insurance industry possible. Ghana Reinsurance PLC (Ghana Re) is the latter. It is the largest local reinsurer in Ghana, the backbone of the country‘s non-life insurance sector, and one of the few state-owned enterprises that has consistently paid dividends to the government since the establishment of the State Interests and Governance Authority (SIGA) .

Yet, 2025 and 2026 have brought Ghana Re into an unfamiliar spotlight. The company’s full-year 2024 results revealed a staggering 63% decline in profit after tax, from GH¢224.90 million in 2023 to GH¢84.22 million . The drop was attributed to losses on Eurobonds, higher claims and commissions, impairment charges, and increased management expenses .
📢 GET A DETAILED ARTICLES + JOBS
Join ASJ's WhatsApp Channel and never miss a post or opportunity.

In response, the government has taken decisive action. A new seven-member Board of Directors was inaugurated in June 2025, chaired by Mr. Samuel Kwadwo Sarpong, a respected corporate governance professional . At the helm of management is Mr. Seth Kobla Aklasi—the former CEO of Donewell Insurance and President of the Ghana Insurers Association (GIA)—who was appointed Acting Managing Director in February 2025 and confirmed as substantive MD following the board‘s inauguration .
The most transformative development, however, is the government‘s announcement that Ghana Re will be listed on the Ghana Stock Exchange (GSE), making it the first reinsurance company to be listed on the local bourse . The move, authorised by Finance Minister Dr. Cassiel Ato Forson, is intended to mobilise additional capital, boost investor confidence, and support the company‘s expansion ambitions across Africa .
For investors, insurance professionals, and corporate clients, Ghana Re represents a case study in state-owned enterprise transformation. It has the balance sheet strength assessed as “strong” by AM Best, a dominant position in the domestic reinsurance market, and a growing footprint across Africa (with a new office in Morocco and a subsidiary in Kenya) . But it also carries a marginal financial strength rating (C++) and weak enterprise risk management capabilities by global standards .
This profile examines Ghana Re‘s 1970s founding, its financial performance and dividend history, the 2024 profit collapse, the new leadership under Seth Aklasi, the AM Best rating (C++ / b+), the strategic expansion into North and East Africa, the imminent GSE listing, and the critical question: Can a state-owned reinsurer with a marginal credit rating successfully transition to a publicly traded Pan-African player while navigating volatile profitability and significant sovereign risk exposure?
Company Overview
Historical Foundation: Ghana‘s National Reinsurer
Ghana Reinsurance PLC (Ghana Re) is the first and largest reinsurance company in Ghana . It was established in the 1970s as a state-owned enterprise with a mandate to provide reinsurance capacity to the Ghanaian insurance market, reducing the outflow of foreign exchange to international reinsurers and building local underwriting expertise.
For over five decades, Ghana Re has served as the backbone of the country‘s non-life insurance sector, offering reinsurance protection to over 300 clients across Africa . It is a corporate member of the African Insurance Organisation (AIO) and has established itself as a key player in the West African reinsurance market.
The company changed its name from Ghana Reinsurance Company Limited to Ghana Reinsurance PLC in September 2022, a rebranding that signalled its evolution and ambition .
Ownership Structure: State-Owned With Listing Plans
| Shareholder | Stake | Status |
|---|---|---|
| Government of Ghana (through SIGA) | 100% | Current |
| Public / Private Investors | TBD | Post-listing |
The company is currently wholly-owned by the Government of Ghana, represented by the State Interests and Governance Authority (SIGA) . It is one of the few state-owned enterprises that has consistently paid dividends to the government since SIGA‘s establishment .
However, this is about to change. In October 2025, SIGA Director-General Prof. Michael Kpessa-Whyte announced that Ghana Re is set to become the first reinsurance company to be listed on the Ghana Stock Exchange (GSE) . The Minister of Finance has authorised a comprehensive study of the company‘s financial profile to determine its readiness for listing, with the assessment currently ongoing .
Leadership: The New Board and Management Team
Board of Directors (Inaugurated June 3, 2025)
The seven-member board was inaugurated by Finance Minister Dr. Cassiel Ato Forson :
| Name | Position | Background |
|---|---|---|
| Samuel Kwadwo Sarpong | Chairman | Respected management consultant and corporate governance professional |
| Seth Kobla Aklasi | Managing Director | Former CEO of Donewell Insurance; President of Ghana Insurers Association (GIA) |
| Hon. Nurein Shaibu Migyimah | Member | Entrepreneur, legislator (MP for Assin Central), philanthropist |
| Masawudu Mahama | Member | Governance and HR professional; insurance sector experience |
| Prof. Joseph Yensu | Member | Professor in Finance and Economics |
| Francis Kobena Addison | Member | Chartered Insurer; Managing Director of Quality Insurance Company (QIC) |
| Dr. Richard Kwasi Appietu | Member | Chartered Accountant; banking and finance professional |
The Chairman: Samuel Kwadwo Sarpong
Sarpong is a respected management consultant and corporate governance professional . His appointment as Chairman signals the government‘s intention to strengthen governance oversight at Ghana Re, particularly as the company prepares for listing.
The Managing Director: Seth Kobla Aklasi
Seth Aklasi is one of the most accomplished insurance executives in Ghana. He was appointed Acting Managing Director of Ghana Re in February 2025 and was confirmed as substantive Managing Director following the inauguration of the Board in June 2025 .
Career Trajectory:
| Role | Organisation | Period |
|---|---|---|
| Managing Director (Substantive) | Ghana Reinsurance PLC | June 2025 – Present |
| Acting Managing Director | Ghana Reinsurance PLC | February 2025 – June 2025 |
| Chief Executive Officer | Donewell Insurance Limited | 2015 – February 2025 |
| Managing Director | Priority Insurance | Brief tenure |
| Chief Operations Officer | International Energy Insurance (IEI) | 2008 – 2015 |
| Various roles | Enterprise Insurance Company Limited (EICL) | Earlier career |
Key Achievements at Donewell:
-
Led the company‘s transformation, driving innovation, operational efficiency, and sustainable growth
-
Achieved nine consecutive years of profitability (2015–2024)
-
2024 recorded the highest profitability in Donewell‘s history
Industry Leadership:
| Role | Organisation |
|---|---|
| President (second term) | Ghana Insurers Association (GIA) |
| Chairman | Accident Committee of the GIA |
| Member | Executive Committee of the African Insurance Organisation (AIO) |
| Vice Chairman (second term) | ECOWAS Brown Card Scheme, Ghana National Bureau |
| Member | Client Rescue Fund Committee, National Insurance Commission (NIC) |
| Academic Board Member | West African Insurance Institute |
Professional Credentials:
-
Associate of the Chartered Insurance Institute (ACII), UK
-
Fellow of the Chartered Insurance Institute of Ghana (FCIIG)
-
MSc in Insurance and Risk Management – Bayes Business School, University of London
-
Bachelor‘s degree in Social Sciences – University of Cape Coast
Aklasi has also attended a number of insurance-related courses both at home and abroad and was a panellist at the Africa Re Insurance Awards .
Board Member Profile: Francis Kobena Addison
Francis Addison, a board member of Ghana Re, is also the Managing Director of Quality Insurance Company (QIC) PLC . He holds the ACII designation and has extensive experience in the Ghanaian insurance market. His presence on the board provides additional technical underwriting expertise.
Operations and Footprint
Headquarters:
Ghana Reinsurance PLC is headquartered in Accra, Ghana.
Regional Presence:
| Location | Type | Significance |
|---|---|---|
| Ghana | Headquarters | Primary operations; dominant local market position |
| Morocco | Contact Office (launched October 2024) | Strategic expansion into North Africa |
| Cameroon | Contact Office | Francophone West Africa presence |
| Kenya | Subsidiary | East African foothold |
Client Base:
Ghana Re serves over 300 clients across Africa . Approximately two-thirds of its reinsurance revenue is now generated from outside Ghana, demonstrating successful geographical diversification .
Key Operational Metrics:
| Metric | Value |
|---|---|
| Founded | 1970s |
| Ownership | State-owned (Government of Ghana / SIGA) |
| Listing Status | Pre-listing (GSE listing imminent) |
| Clients | 300+ across Africa |
| International Revenue Share | ~67% (from outside Ghana) |
| Regional Offices | Morocco, Cameroon, Kenya |
| AM Best Rating | C++ (Marginal) / b+ (Marginal) – Stable Outlook |
| Board Inauguration | June 3, 2025 |
| MD Appointment (Substantive) | June 2025 |
The 2024 Financial Results: A 63% Profit Collapse and What It Means
The full-year 2024 financial results, presented at the 22nd Annual General Meeting (AGM) in October 2025, revealed a significant deterioration in profitability .
Profitability Metrics
| Metric | 2024 | 2023 | Change |
|---|---|---|---|
| Profit After Tax | GH¢84.22 million | GH¢224.90 million | -63% |
| Insurance Revenue | GH¢1,049 million | GH¢684 million | +53% |
| Dividend Paid to Government | GH¢13 million | GH¢24 million | -46% |
Drivers of the Profit Collapse
1. Revenue Growth (Positive Signal)
Insurance revenue grew by 53% , from GH¢684 million in 2023 to GH¢1,049 million in 2024 . This indicates that Ghana Re is writing more business and expanding its premium base—a positive sign for long-term growth.
2. But Expenses Outpaced Revenue
The profit collapse was driven by several factors, as explained by Board Chairman Samuel Sarpong :
-
Losses on Eurobonds: Ghana‘s sovereign debt restructuring affected the value of Ghana Re‘s investment portfolio.
-
Higher claims and commissions: The cost of reinsurance claims and commissions paid to brokers increased.
-
Impairment charges: Write-downs on assets, likely related to the sovereign debt restructuring.
-
Modification expenses: Costs associated with restructuring debt instruments.
-
Increased management expenses: Administrative costs rose.
The “Retained Earnings” Strategy
Dividend paid to the government declined from GH¢24 million in 2023 to GH¢13 million in 2024. Prof. Kpessa-Whyte (SIGA Director-General) attributed the decline to the company‘s efforts to retain some profit for activities and its intention to inject some capital into the business .
Aklasi explained that the decline could be attributed specifically to growth in insurance expenses, management expenses, and claims, which impacted the bottom line .
AM Best‘s Assessment
AM Best‘s January 2026 rating report provided additional context on Ghana Re‘s performance :
| Metric | Assessment |
|---|---|
| Return on Equity (2021–2024) | At least 9% each year |
| Non-Life Combined Ratio (3-yr avg) | 95.9% |
| Profitability Volatility | High year over year |
| Unprofitable Years (2022–2024) | Two of three years were unprofitable in non-life segment |
| 2025 Expectations (9 months) | Moderate overall loss due to foreign exchange movements |
Key takeaways from AM Best:
-
Balance sheet strength is assessed as strong
-
Operating performance is assessed as adequate
-
Business profile is limited
-
Enterprise risk management is weak
The AM Best Rating: C++ (Marginal) with Stable Outlook
On January 29, 2026, AM Best affirmed the credit ratings of Ghana Reinsurance PLC .
The Ratings
| Rating Type | Rating | Outlook |
|---|---|---|
| Financial Strength Rating (FSR) | C++ (Marginal) | Stable |
| Long-Term Issuer Credit Rating (ICR) | b+ (Marginal) | Stable |
What C++ Means
A C++ (Marginal) rating indicates that an insurance company has a marginal financial strength relative to the standards of the industry. While the company can meet its ongoing insurance obligations, it is more susceptible to adverse economic or underwriting conditions than higher-rated companies.
For context, AM Best‘s rating scale for Financial Strength Ratings ranges from A++ (Superior) to D (Poor). A C++ rating is five notches below the top tier .
Balance Sheet Strength: Strong
Despite the marginal overall rating, AM Best assesses Ghana Re‘s balance sheet strength as strong . This is underpinned by:
-
Risk-adjusted capitalisation expected to remain at least at the very strong level, as measured by Best‘s Capital Adequacy Ratio (BCAR)
-
However, risk-adjusted capitalisation deteriorated at year-end 2024
-
Expected to have rebounded by year-end 2025, in part due to improved credit quality of investments in Ghana
Significant Sovereign Risk Exposure
AM Best noted that Ghana Re remains exposed to elevated investment risk due to:
-
Significant holding of Ghana‘s sovereign debt
-
Exposure to the domestic banking sector through cash and deposits
Operating Performance: Adequate
Ghana Re‘s operating performance is assessed as adequate , based on:
-
ROE of at least 9% in each of the five years between 2021 and 2024
-
2025 overall profitability expected to be negatively impacted by foreign exchange movements
-
Ghana Re reported a moderate overall loss for the first nine months of 2025
-
Profitability has exhibited a high degree of volatility year over year
-
Non-life segment 3-year weighted average combined ratio: 95.9%
-
However, two of these years (2022-2024), including 2024, were unprofitable
Business Profile: Limited
While Ghana Re maintains a dominant position in Ghana as the largest local reinsurer, its global business profile is assessed as limited because:
-
It lacks an established position in any of its foreign markets
-
It is exposed to high levels of political, economic, and financial system risks in the countries in which it operates
Enterprise Risk Management: Weak
The company‘s risk management framework is evolving, and its risk management capabilities are weak when compared with its risk profile .
Implications of the Rating
For Ghana Re‘s clients (insurance companies that buy reinsurance from Ghana Re), the C++ rating may affect:
-
Credit risk perception: Ceding companies may demand collateral or shorter payment terms.
-
Competitive positioning: International reinsurers with A-rated balance sheets may be perceived as more secure.
However, as the largest local reinsurer in Ghana, Ghana Re has a captive market among Ghanaian insurers who are required by regulation or commercial practice to place a portion of their business locally.
Regional Expansion: The Morocco Office and Kenya Subsidiary
Ghana Re has actively pursued geographical diversification in recent years, with approximately two-thirds of its reinsurance revenue now generated from outside Ghana .
Morocco Contact Office (Launched October 2024)
In October 2024, Ghana Re officially launched a new office in Morocco as part of its strategic expansion efforts . The launch event was attended by key industry stakeholders, partners, and executives.
Strategic Significance:
-
Positions Ghana Re to serve the North African reinsurance market
-
Morocco is a gateway to Francophone North Africa and a hub for African reinsurance
-
Strengthens Ghana Re‘s ability to offer localised expertise in the region
-
Enhances partnerships with Moroccan insurers and reinsurers
Cameroon Contact Office
Ghana Re also maintains a contact office in Cameroon, serving the Francophone West and Central African markets.
Kenya Subsidiary
Ghana Re has a subsidiary in Kenya, providing a foothold in the East African market.
Strategic Rationale
-
Diversification: Reducing reliance on the Ghanaian market (currently ~33% of revenue)
-
Growth: Accessing faster-growing markets in East and North Africa
-
Reinsurance Expertise: Exporting Ghanaian reinsurance expertise to other African markets
-
AfCFTA Positioning: Positioning for increased cross-border insurance flows under the African Continental Free Trade Area
The GSE Listing: A Historic First for Reinsurance
The most transformative development for Ghana Re is the government‘s plan to list the company on the Ghana Stock Exchange (GSE) .
Announcement
In October 2025, SIGA Director-General Prof. Michael Kpessa-Whyte announced that Ghana Re is set to become the first reinsurance company to be listed on the GSE .
The Minister of Finance has authorised a comprehensive study of the company‘s financial profile to determine its readiness for listing. Upon completion, a Cabinet memorandum will be submitted for approval, after which the technical processes required for listing will begin .
Rationale for Listing
| Objective | Explanation |
|---|---|
| Mobilise additional capital | Raise funds for expansion into untapped markets across Africa |
| Boost investor confidence | Signal financial strength and governance maturity |
| Diversify shareholder base | Reduce state ownership; attract private and institutional investors |
| Enhance visibility | Increase profile among global partners and reinsurers |
| Provide liquidity | Enable trading of shares; create exit for early investors |
Government‘s Position
Prof. Kpessa-Whyte stated that President John Mahama is interested in ensuring companies were listed and aligned with certain rules associated with corporate governance . He added that SIGA, together with the board and management of Ghana Re, was enthusiastic about the prospect, confident that the move would boost investor confidence and position the company for sustainable growth .
Management‘s Position
MD Seth Aklasi welcomed the plan, describing it as a timely step to strengthen the firm‘s capital base . He explained that the stock market has performed strongly this year, creating a favourable environment for Ghana Re to attract new investors and raise funds for expansion .
Aklasi stated that growth in the reinsurance business depends largely on capital strength, and listing on the GSE would provide the financial flexibility needed to deepen operations and increase visibility among global partners .
Potential Impact of Listing
Positives:
-
Access to public equity markets for future capital raises
-
Enhanced governance and disclosure requirements
-
Increased transparency, which may improve credit ratings over time
-
Liquidity for government as a shareholder (partial exit)
Risks:
-
Public markets may punish volatility in profitability (which has been high)
-
Disclosure of financial performance may reveal weaknesses to competitors
-
Pressure to pay dividends may conflict with capital retention for growth
Business Model: The Reinsurance Specialist
Ghana Re operates as a reinsurance company—it provides insurance to insurance companies. Instead of insuring individual cars or houses, Ghana Re insures the portfolios of insurance companies, helping them manage risk and reduce their exposure to large losses.
Core Business: Non-Life Reinsurance
Ghana Re provides reinsurance protection to over 300 clients across Africa . The company‘s non-life segment reported a three-year weighted average combined ratio of 95.9% (2022-2024), indicating that its core reinsurance business is marginally profitable on an underwriting basis .
Revenue Streams
| Revenue Stream | Explanation |
|---|---|
| Reinsurance Premiums | Primary source; from ceding insurance companies |
| Investment Income | Returns on the “float“ (premiums held between collection and claims payment) |
| Foreign Exchange Gains/Losses | Significant impact due to multi-currency operations |
Geographical Revenue Split
Approximately two-thirds of Ghana Re‘s reinsurance revenue is now generated from outside Ghana . This diversification reduces reliance on the Ghanaian market but exposes the company to political, economic, and financial system risks in other African countries .
Risk Management: A Work in Progress
AM Best assesses Ghana Re‘s enterprise risk management as weak, noting that the company‘s risk management framework is evolving and its risk management capabilities are weak when compared with its risk profile . This is an area that the new board and management team are likely prioritising.
Investment Portfolio: Sovereign Debt Concentration
Ghana Re remains exposed to elevated investment risk due to:
-
Significant holding of Ghana‘s sovereign debt
-
Exposure to the domestic banking sector through cash and deposits
The improved credit quality of investments in Ghana following the sovereign debt restructuring has helped risk-adjusted capitalisation rebound, but concentration remains a concern .
Industry Leadership: The GIA Presidency and International Engagement
MD Seth Aklasi‘s leadership extends beyond Ghana Re. He is currently serving his second term as President of the Ghana Insurers Association (GIA) , the umbrella body for all insurance companies in Ghana .
Annual International Seminar
Ghana Re hosts an Annual International Seminar that brings together insurance professionals from across Africa and the Middle East. The 20th edition took place in February 2026 at the Aqua Safari Resort, under the theme “Advanced Property Insurance Underwriting and Claims Management” .
The seminar brought together over 100 insurance professionals from 12 African countries: Ghana, Gabon, Ethiopia, Sudan, Togo, Zambia, Kenya, Rwanda, Malawi, Liberia, Namibia, and Cameroon .
Participants included the National Insurance Corporation of Liberia (NICOL), whose Acting Managing Director, Abdullah S. Swaray, led a delegation to deepen strategic partnership with Ghana Re .
Strategic Significance
-
Positions Ghana Re as a thought leader in African reinsurance
-
Builds relationships with insurance regulators and companies across the continent
-
Creates opportunities for business development and partnership
-
Enhances Ghana Re‘s reputation as a regional player
19th Edition (2025)
The 19th edition of the seminar witnessed a massive turnout of over 60 participants with representation from countries such as Liberia, Sudan, Togo, Nigeria, Egypt, Zimbabwe, Ethiopia, Kenya, Cote D‘Ivoire, Cameroon, Jordan, UAE, and Ghana .
Corporate Social Responsibility (2025)
In December 2025, Ghana Re held its Annual Corporate Social Responsibility event. The specific details of the CSR initiative are not detailed in search results, but the company maintains an annual CSR programme as part of its corporate citizenship .
Challenges and Risks
No analysis of Ghana Reinsurance PLC is complete without acknowledging the significant headwinds it faces.
Risk 1: Marginal Credit Rating (C++)
The C++ rating from AM Best signals to international reinsurance partners and ceding companies that Ghana Re has marginal financial strength. This may:
-
Require Ghana Re to post collateral for certain treaties
-
Limit its ability to compete for high-value international reinsurance business
-
Increase the cost of retrocession (reinsurance for reinsurers)
Risk 2: Weak Enterprise Risk Management
AM Best explicitly assesses Ghana Re‘s enterprise risk management as weak . The company‘s risk management capabilities are weak when compared with its risk profile . This is a governance and operational risk that the new board and management must address.
Risk 3: Sovereign Debt Concentration
Ghana Re holds significant holdings of Ghana‘s sovereign debt . A future sovereign debt restructuring or fiscal deterioration would directly impair the company‘s investment portfolio and capital position.
Risk 4: Profitability Volatility
Ghana Re‘s profitability has exhibited a high degree of volatility year over year . The 63% profit collapse in 2024, following strong years, demonstrates that earnings are unpredictable. For a publicly listed company, earnings volatility would likely be punished by the market.
Risk 5: Foreign Exchange Exposure
Ghana Re operates in multiple currencies (GHS, USD, EUR, XOF, etc.). AM Best noted that overall profitability for 2025 is expected to be negatively impacted by the effect of foreign exchange movements . The company reported a moderate overall loss for the first nine months of 2025 due to FX movements.
Risk 6: The Listing Execution Risk
Listing on the GSE is a complex process. The company must:
-
Meet enhanced disclosure and governance requirements
-
Attract sufficient investor interest
-
Price the offering appropriately
-
Manage the transition from 100% state ownership to a diversified shareholder base
Any misstep could damage the company‘s reputation and market confidence.
Risk 7: Competition from International Reinsurers
Ghana Re competes with global reinsurers such as Swiss Re, Munich Re, Hannover Re, and Africa Re. These companies have superior credit ratings (A+ to AA+), deeper capital bases, and longer track records. For large, complex risks, Ghana Re may be at a competitive disadvantage.
Risk 8: Economic Headwinds in Operating Markets
Ghana Re is exposed to political, economic, and financial system risks in the countries in which it operates . Currency devaluations, inflation, and regulatory changes in any of its markets could affect profitability.
Risk 9: Leadership Transition Risk
Aklasi was appointed MD in February 2025 and confirmed in June 2025 . While he has a strong track record at Donewell, leadership transitions carry execution risk. The company is also undergoing a board transition (inaugurated June 2025).
Risk 10: The 2024 Profit Collapse Overhang
The 63% profit decline in 2024 remains a concern. While the Board attributed it to one-off factors (Eurobond losses, impairment charges), investors may view it as a signal of underlying volatility. Rebuilding investor confidence will require consistent performance in 2025 and 2026.
Economic and Industry Impact
Backbone of Ghana‘s Non-Life Insurance Sector
As the largest local reinsurer in Ghana, Ghana Re provides essential capacity to the country‘s non-life insurance market. Without Ghana Re, Ghanaian insurers would need to cede a larger share of their premiums to international reinsurers, resulting in capital outflow and reduced local underwriting capacity.
Financial Inclusion Through Insurance
By supporting the local insurance market, Ghana Re indirectly contributes to financial inclusion. Insurers backed by Ghana Re can offer policies to SMEs, farmers, and individuals who might otherwise be uninsured.
Foreign Exchange Retention
By retaining reinsurance premiums within Ghana (rather than ceding them entirely to international reinsurers), Ghana Re helps retain foreign exchange and supports the local financial system.
Employment and Skills Development
Ghana Re directly employs a team of underwriters, actuaries, and claims professionals. Through its Annual International Seminar, the company contributes to skills development across the African insurance industry.
Dividend Contribution to Government
Even with the reduced dividend in 2024 (GH¢13 million), Ghana Re continues to contribute to government revenue—a rarity among state-owned enterprises . As the company grows and profitability stabilises, dividend contributions could increase.
Regional Integration (AfCFTA)
Ghana Re‘s expansion into Morocco, Cameroon, and Kenya positions it to benefit from increased cross-border insurance flows under the African Continental Free Trade Area (AfCFTA). As African economies integrate, demand for Pan-African reinsurance solutions will grow.
Future Outlook
As of May 2026, Ghana Reinsurance PLC is at a pivotal moment in its 50-year history. The company is simultaneously navigating a profit collapse, a leadership transition, a board overhaul, a regional expansion, and an imminent listing on the Ghana Stock Exchange.
The Immediate Agenda (2026-2027)
-
Execute the GSE Listing: Complete the financial assessment, Cabinet memorandum, and technical processes required for listing .
-
Stabilise Profitability: Reverse the 63% profit decline; deliver improved underwriting results in 2025 and 2026.
-
Strengthen Enterprise Risk Management: Address AM Best‘s concerns about weak risk management capabilities .
-
Deepen Regional Expansion: Leverage the Morocco office to capture North African reinsurance business.
-
Manage Sovereign Risk: Diversify the investment portfolio away from heavy concentration in Ghanaian sovereign debt.
-
Maintain Dividend to Government: Continue to pay dividends while retaining capital for growth.
The Bull Case (Optimistic)
-
The Aklasi Turnaround: Seth Aklasi replicates his Donewell success (nine consecutive years of profitability) at Ghana Re. Underwriting discipline improves, expenses are controlled, and profitability stabilises.
-
Listing Catalyses Growth: The GSE listing raises significant capital, enabling Ghana Re to expand into new African markets, invest in technology, and improve its credit rating.
-
Regional Expansion Bears Fruit: The Morocco and Kenya offices generate substantial new business. Ghana Re becomes a recognised Pan-African reinsurer, reducing reliance on the Ghanaian market to 40%.
-
AM Best Upgrades Rating: Improved risk management and profitability lead to a rating upgrade to B+ (Adequate) within 3-5 years, enhancing competitiveness.
-
Dividends Recover: As profitability stabilises, dividends to government (and eventually to public shareholders) grow steadily.
The Bear Case (Pessimistic)
-
Listing Fails to Attract Investors: Investor confidence remains low due to the 2024 profit collapse and C++ rating. The listing is undersubscribed, and the government retains majority ownership.
-
Profitability Remains Volatile: The 2024 collapse is not a one-off; Ghana Re continues to report volatile earnings, disappointing public market investors.
-
Risk Management Weakness Persists: AM Best‘s concerns about weak enterprise risk management are not adequately addressed. The rating remains C++.
-
Sovereign Debt Crisis Repeats: Ghana faces another fiscal crisis; Ghana Re‘s sovereign debt holdings are impaired again, leading to another profit collapse.
-
International Competition Intensifies: Africa Re and international reinsurers aggressively target Ghana Re‘s domestic market share, using their superior ratings to win business.
-
Leadership Transition Stumbles: Aklasi struggles to adapt from the CEO of a mid-tier insurer (Donewell) to the MD of a national reinsurer. Key talent departs.
The Verdict
Ghana Reinsurance PLC is Africa‘s quiet giant at a crossroads. It has the balance sheet strength of a strong company, the dominant position of a national champion, and the regional ambitions of a Pan-African player . It serves over 300 clients across Africa, has successfully expanded into Morocco, Cameroon, and Kenya, and generates approximately two-thirds of its revenue from outside Ghana .
But it also carries a marginal credit rating (C++), weak enterprise risk management, significant sovereign risk concentration, and a history of volatile profitability—culminating in a 63% profit collapse in 2024 .
The appointment of Seth Aklasi as Managing Director is the most significant positive development. His track record at Donewell—nine consecutive years of profitability—demonstrates that he can deliver underwriting discipline and operational excellence . His leadership of the Ghana Insurers Association (as President) and his ACII qualification provide the technical credibility and industry influence that Ghana Re needs .
The new board, chaired by Samuel Kwadwo Sarpong and including seasoned professionals like Francis Addison (MD of QIC), provides strong governance oversight .
The planned listing on the Ghana Stock Exchange is a transformative opportunity. It will provide capital for expansion, enhance governance and transparency, and signal confidence in Ghana Re‘s future . But it also exposes the company to public market scrutiny. Investors will demand consistent profitability, transparent disclosure, and a clear path to rating upgrades.
For insurance companies across Africa, Ghana Re remains a critical partner. It is the largest local reinsurer in Ghana, and for many Ghanaian insurers, it is the only domestic option for certain classes of business.
For investors considering the GSE listing, Ghana Re offers exposure to a Pan-African reinsurer with strong balance sheet fundamentals, but with significant risks: volatile profitability, marginal credit rating, sovereign concentration, and weak risk management.
Ghana Reinsurance PLC is not trying to be the largest reinsurer in Africa—Africa Re holds that crown. It is trying to be the most resilient Pan-African reinsurer. Under Aklasi‘s leadership, with a new board, a regional footprint, and a listing on the horizon, it has the pieces in place. But the next three years will determine whether the quiet giant can finally match its ambition with execution.
FAQ SECTION
1. Is Ghana Reinsurance PLC a government-owned company?
Yes. Ghana Reinsurance PLC is currently wholly-owned by the Government of Ghana, represented by the State Interests and Governance Authority (SIGA). However, the government has announced plans to list a portion of the company on the Ghana Stock Exchange (GSE), which would make it the first reinsurance company to be listed on the local bourse .
2. Who is the Managing Director of Ghana Reinsurance PLC?
The Managing Director is Mr. Seth Kobla Aklasi. He was appointed Acting Managing Director in February 2025 and confirmed as substantive MD following the inauguration of the Board of Directors in June 2025. He is the former CEO of Donewell Insurance (where he achieved nine consecutive years of profitability) and is currently serving his second term as President of the Ghana Insurers Association (GIA) .
3. Who is the Chairman of the Board of Ghana Re?
The Board is chaired by Mr. Samuel Kwadwo Sarpong, a respected management consultant and corporate governance professional. The seven-member board was inaugurated by Finance Minister Dr. Cassiel Ato Forson on June 3, 2025 .
4. How did Ghana Re perform financially in 2024?
Ghana Re reported a 63% decline in profit after tax, from GH¢224.90 million in 2023 to GH¢84.22 million in 2024. The decline was attributed to losses on Eurobonds, higher claims and commissions, impairment charges, modification expenses, and increased management expenses. Insurance revenue grew 53% to GH¢1,049 million .
5. What is AM Best‘s rating for Ghana Re?
On January 29, 2026, AM Best affirmed Ghana Re‘s Financial Strength Rating of C++ (Marginal) and Long-Term Issuer Credit Rating of b+ (Marginal), with a Stable Outlook. AM Best assesses Ghana Re‘s balance sheet strength as strong, operating performance as adequate, business profile as limited, and enterprise risk management as weak .
6. Is Ghana Re being listed on the Ghana Stock Exchange?
Yes. In October 2025, SIGA Director-General Prof. Michael Kpessa-Whyte announced that Ghana Re is set to become the first reinsurance company to be listed on the Ghana Stock Exchange (GSE) . The Minister of Finance has authorised a study of the company‘s financial profile, and a Cabinet memorandum will be submitted for approval before technical processes begin .
7. Where does Ghana Re operate outside Ghana?
Ghana Re has expanded its regional footprint with a contact office in Morocco (launched October 2024), a contact office in Cameroon, and a subsidiary in Kenya. Approximately
Last Updated on May 13, 2026 by Samuel Kwame Boadu
Disclaimer: Some content on Accra Street Journal may be aggregated, summarized, or edited from third-party sources for informational purposes. Images and media are used under fair use or royalty-free licenses. Accra Street Journal is a subsidiary of SamBoad Publishing Hub under SamBoad Business Group Ltd, registered in Ghana since 2014.
For concerns or inquiries, please visit our Privacy Policy or Contact Page.

Samuel Kwame Boadu is a Ghanaian media entrepreneur and storyteller with a passion for amplifying urban voices and uncovering everyday truths. He is the Editor-in-Chief and Founder of Accra Street Journal, a dynamic digital platform dedicated to capturing the pulse of Ghana’s capital—its people, culture, challenges, business, sports and innovations.