Introduction: The Wealth That Disappears
There is a scene that plays out in courtrooms across Accra every single day.
A parent dies. The children gather—some from this marriage, some from that one, some acknowledged, some not. The property is a house in a good neighbourhood, a plot of land bought twenty years ago, a small business that was the parent’s life work.

No one has a will. No one knows what the parent wanted. No one agrees on who should get what.
📢 GET A DETAILED ARTICLES + JOBS
Join ASJ's WhatsApp Channel and never miss a post or opportunity.

Years pass. Lawyers are hired. Savings are drained. Siblings who once loved each other now refuse to speak. The property—the wealth—is eaten away by legal fees, administrative costs, and the slow erosion of time.
By the time the court finally decides, there is often nothing left to inherit.

This is not a tragedy that happens to other people. It is the norm.
According to a 2023 report by the Institute for Liberty and Policy Innovation (ILAPI), an estimated 85.5% of Ghanaian adults die without a will . The CEO of the Ghana Association of Banks, Mr. John Awuah, citing IMANI Center for Policy and Education & ILAPI (2023), confirmed that only about 10% of adults have prepared a written will . In South Africa, fewer than 15% die with a valid will. Across Africa, the pattern is the same: we are building wealth, but we are not preserving it .
The continent is projected to host over 150,000 millionaires by 2027 . Yet formal estate planning remains exceptionally low. Billions in assets and enterprises fail to transition smoothly from one generation to the next. Wealth is created, enjoyed, and then—lost.
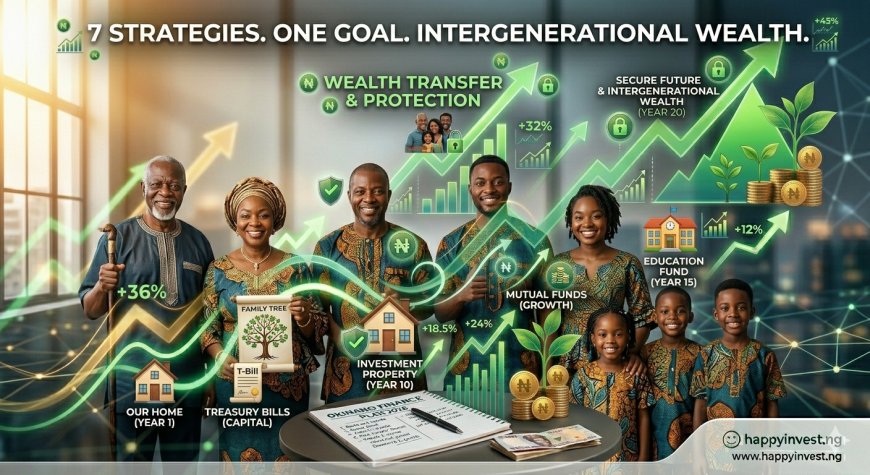
This feature is for the Ghanaian who is tired of breaking the cycle. We will examine what generational wealth actually means, the cultural and structural barriers that prevent its transfer, the assets that build lasting value, and the legal tools—wills, trusts, succession planning—that ensure your wealth outlasts you.
Because building wealth is only half the battle. The other half is keeping it in the family. And that starts with a conversation most of us are too afraid to have.
What Is Generational Wealth? (And What It Is Not)
Let us start with a clear definition, because the term is often misunderstood.
Generational Wealth Is Assets That Outlast You
Generational wealth is not simply “having a lot of money.” It is assets that are preserved, grown, and passed from one generation to the next—creating a foundation that each generation can build upon rather than starting from zero.
Examples of generational assets:
-
Land and property that appreciates and can be divided or rented
-
A family business that continues operating after the founder retires or passes
-
Investment portfolios (stocks, Treasury bills, mutual funds) that generate returns for heirs
-
Trust funds that provide for children and grandchildren over decades
-
Education and skills that enable the next generation to earn and build
What generational wealth is not:

-
A large salary that stops when you retire
-
A house you live in that will be sold to pay debts
-
Consumer goods (cars, electronics, designer clothes) that depreciate to zero
-
Cash under the mattress that loses value to inflation
The Two-Step Process
Building generational wealth requires two distinct steps:
Step One: Accumulation. You must earn, save, and invest. You must acquire assets that appreciate or generate income. This is what most people focus on—and where most stop.
Step Two: Preservation and Transfer. You must protect those assets from being lost to taxes, disputes, mismanagement, or fragmentation. You must create legal structures that ensure the wealth reaches the people you intend, in the way you intend, at the time you intend.
Most Ghanaians are reasonably good at Step One. They save. They buy land. They build homes. They start businesses.
Most Ghanaians are terrible at Step Two. They do not write wills. They do not set up trusts. They do not create succession plans for their businesses. They do not have conversations with their children about inheritance.
And so, when they die, their wealth does not transfer. It disappears.
The editorial observation: The Ghanaian family is the strongest social institution we have. But when it comes to inheritance, the same family that supports each other in life often tears itself apart in death. The reason is not greed—though greed exists. The reason is uncertainty. When there is no will, there is no clear instruction. And when there is no instruction, everyone must fight for what they believe is theirs. The will is not a document for the wealthy. It is a document for the peaceful. It is the difference between your children grieving together and your children fighting in court.
The Hard Numbers: How Ghana Is Failing at Wealth Transfer
Let us look at the data, because the data leaves no room for comfort.
The Will Gap
According to Mr. John Awuah, CEO of the Ghana Association of Banks, only about 10% of Ghanaian adults have prepared a written will . The UMB LegacyCare+ launch cited an even more striking figure: 85.5% of Ghanaian adults die without a will .
This means that the vast majority of Ghanaian families are intestate—dying without a legal document specifying how their assets should be distributed. The Intestate Succession Law, PNDCL 111, provides a default framework, but it is a blunt instrument. It does not account for blended families, for children from multiple relationships, for family members who have been estranged, for special bequests to friends or charities .
The result is that “a significant proportion of deceased persons’ assets—homes, farms, and deposits—remain either locked in probate or lost in succession disputes for years” .

The Family Business Crisis
Family-owned enterprises form the backbone of Ghana’s economy, driving job creation, innovation, and community development . Yet globally, 95% of family businesses do not survive beyond the third generation .
The causes are predictable: gaps in succession planning, weak governance systems, unmanaged growth, and unresolved family conflicts . The IFC, a member of the World Bank Group, has held workshops in Ghana to address this exact problem, training family businesses to strengthen governance and manage successful generational transitions .
Mr. Kyle Kelhofer, IFC Senior Country Manager for Ghana and Liberia, noted that “navigating generational transitions requires preparing the next generation to lead, supporting incumbents to gradually let go, and ensuring that succession happens smoothly and intentionally” .
The Financial Literacy Gap
Financial literacy in Ghana has traditionally focused on earning, saving, and investing. Little attention has been paid to wealth preservation and transference .
Mr. Awuah noted that “financial literacy is not just about earning more, but about managing and preserving what we already have” . He called for estate and gift planning to be integrated into Ghana’s education system and cultural practices, noting that “without effective estate and gift planning, our strides in financial inclusion risk being undone” .
The Lost Billions
The scale of the problem is staggering. According to the OECD and the Tax Justice Network, Africa loses an estimated US$60 billion annually through illicit financial flows and untracked capital leakages . A portion of this is wealth that could have been transferred to heirs but was instead lost to poor planning, disputes, and administrative failure.
As the Bora Capital Advisors note, “soft life without assets is ultimately unsustainable” . The same could be said of wealth without a transfer plan.
The editorial observation: The numbers are not abstract. Behind each percentage is a family that lost a home, a business that closed, a child who did not get the education their parent intended. We are not failing at wealth creation in Ghana. We are failing at wealth preservation. And that failure compounds across generations. The child who inherits nothing starts from zero. The child who inherits a house or a business starts five steps ahead. That gap—between those who inherit and those who do not—is the inequality we rarely talk about.
The Assets That Build Generational Wealth (And the Ones That Don’t)
Not every asset is suitable for intergenerational transfer. Some assets preserve value across decades. Others evaporate.
Land and Property (The Ghanaian Foundation)
For generations, Ghanaian families have built wealth through land. It is the most trusted asset class in the country, and for good reason. Land appreciates. It can be rented for income. It can be passed down. It is tangible and durable.
The caution: Land is also the most common source of family disputes. Without a will, a piece of land can be divided among multiple heirs, each receiving a plot too small to be useful. Without proper documentation, land titles can be contested for years.
The strategy: Buy land, document it properly, and specify in your will how it should be divided—or whether it should be held in common by a family trust.
Real Estate Development (The Multiplier)
For those with more capital, real estate development—building rental properties, commercial spaces, or housing units—can generate income across generations. Reverend Dr. Bright Adonai’s book, “Building Generational Wealth through Real Estate Investment,” provides a guide to navigating market trends, tax regimes, and environmental regimes in the Ghanaian real estate sector .
The insight: Real estate development requires capital and expertise, but it can create assets that outlast the developer by decades.
The Family Business (The Engine)
Family-owned enterprises are “critical to shaping legacies that endure across generations” . A business that continues operating after the founder retires can provide employment, income, and identity for multiple generations.
The caution: Most family businesses fail by the third generation. The IFC’s workshops emphasize that successful transition requires “aligning family values with professional business systems; preparing next-generation leaders early and intentionally; establishing structured conflict-resolution mechanisms; and building governance frameworks that strengthen both the family and the enterprise” .
The strategy: Start succession planning early. Identify which children are interested and capable. Train them. Let them make decisions—and mistakes—while you are still there to guide them.
Financial Assets (The Liquid Foundation)
Treasury bills, mutual funds, dividend-paying stocks, and pension funds are essential components of a generational wealth portfolio. They are liquid, divisible, and easier to transfer than physical assets.
The advantage: Financial assets can be divided among multiple heirs without the fragmentation that plagues land. Five children can each receive an equal share of a stock portfolio. They cannot each receive an equal share of a single house.
Education and Human Capital (The Invisible Asset)
Generational wealth is not only financial. A child who receives a quality education, who learns financial literacy, who is taught to manage money and run a business—that child is an asset that will generate wealth for their own children.
The Ghana Association of Banks has championed financial literacy as “the foundation for wealth preservation” . The Centre for Financial Literacy Education Africa (CFLE Africa) has positioned estate planning as a national platform for awareness .
The editorial observation: The most common mistake in generational wealth planning is focusing only on the assets. But assets without stewardship disappear. The child who inherits a house but does not know how to maintain it will lose it. The child who inherits a business but does not know how to run it will run it into the ground. The asset that matters most is the competence of the heir. Invest in that first.
The Smart Life vs. Soft Life Mindset Shift
Before any of the technical tools work, the mindset must shift.
Bora Capital Advisors articulate the distinction clearly. The “soft life”—comfort, enjoyment, visible success—has become the aspiration for many young Ghanaians . Social media has reshaped the meaning of soft life, shifting the focus from financial freedom to visible consumption.
The problem, as Bora notes, is that “one is sustained by assets, while the other is funded by income” . The common pattern is to increase income and scale up spending alongside it, while becoming less consistent with savings and, in turn, delaying investments. Lifestyle upgrades come first, and assets come later, if at all .
The alternative is the “smart life.” It looks like investing before upgrading your car, buying treasury bills before changing your gadgets, building an emergency fund before planning the next trip, or saying “not yet” when everyone else is saying “why not?” .
The smart life is not about giving up everything. It is about balance. A balanced professional might invest 20–30% of income before lifestyle upgrades, diversify between fixed income and equities, hold assets in both cedis and foreign currency exposure, and build medium-term and long-term strategies .
The older generation understood this instinctively. As The Ghana Report notes, “our parents may not have had high-paying jobs or fancy investment strategies, but they had discipline, patience, and financial wisdom” . They lived within their means, saved before they spent, avoided unnecessary debt, and prioritized land and property over luxuries .
The editorial observation: The soft life is not the enemy. Enjoyment is not the enemy. The enemy is the prioritisation of consumption over accumulation. The young professional who saves 20 per cent of their income and spends 80 per cent is building wealth. The young professional who saves 5 per cent and spends 95 per cent is not. The difference is not the income level. It is the discipline to delay gratification—to say “not yet” to the upgrade, the trip, the luxury. That discipline is the foundation of generational wealth. Without it, no asset class will save you.
The Legal Toolkit: Wills, Trusts, and Succession Planning
This is where most Ghanaians fail. The legal infrastructure for wealth transfer exists. We simply do not use it.
The Will (The Non-Negotiable Foundation)
A will is a legal document that specifies how your assets should be distributed after your death. It names beneficiaries. It appoints executors to carry out your wishes. It can include specific bequests—”my house to my eldest daughter, my car to my son, my jewellery to my youngest.”
Without a will, the Intestate Succession Law, PNDCL 111, governs distribution. This law provides a default framework, but it is a blunt instrument. It may not reflect your wishes. It does not account for blended families, for estranged relatives, for children from multiple relationships, for special bequests to friends or charities .
The reality: Only 10 per cent of Ghanaian adults have a will . The rest rely on a law written decades ago to decide the fate of their life’s work.
The action: Write a will. It does not require a lawyer, though legal advice is recommended. The UMB LegacyCare+ product is designed to help customers plan and manage their estates, ensuring that dependents are protected and assets are seamlessly transferred after death . The bank noted that “there are lots of people who would want to do a will, but they don’t know where to start from” .
The barrier: Cultural perceptions. Many people regard writing a will as an omen of death or believe that estate planning is only necessary when wealth reaches a certain level. Mr. Awuah called for this mindset to change, advocating for “behavioural reorientation, making estate planning as routine as opening a bank account or registering a business” .
The Trust (The Strategic Tool)
A trust is a legal arrangement where a trustee holds assets on behalf of beneficiaries. Trusts are more flexible and powerful than wills, though more complex to establish.
Why trusts matter: Trusts can provide for children over time (e.g., monthly distributions from age 18 to 25). They can protect assets from creditors or divorce. They can reduce tax burdens. They can ensure that wealth is managed professionally rather than squandered by inexperienced heirs.
Ghana’s Trusts Act of 2020 represents an important milestone, but its effective implementation “depends on sustained public education to help citizens better understand the use and benefits of trust instruments” . For high-net-worth families with diverse asset portfolios across multiple jurisdictions, a trust is “a crucial tool for asset protection, wealth transfer, tax efficiency, legacy planning, and long-term security” .
The accessibility: Trusts are not only for the ultra-wealthy. Simplified estate products, micro trusts, and low-cost will services can help broaden access to legacy planning among low- and middle-income households .
Succession Planning for Family Businesses
For business owners, a will is not enough. A business requires a succession plan—a documented strategy for who will run the business after you are gone.
The IFC’s Family Governance Workshop emphasized several key principles :
-
Prepare next-generation leaders early and intentionally. Do not assume your children will want to run the business. Ask them. Train them. Let them prove themselves.
-
Align family values with professional business systems. A business that survives across generations must be run professionally, not as a family favour mill.
-
Establish structured conflict-resolution mechanisms. Disagreements are inevitable. What matters is having a process for resolving them before they destroy the business.
-
Plan the transition gradually. Mr. Moez Miaoui, Lead Facilitator, noted that “succession is a two-way street. Successors need to convince you they are ready, and you need to convince them they want to take over” .
The Banking Sector’s Role
Ghana’s banks are increasingly offering estate planning services. The UMB LegacyCare+ product is one example . The Ghana Association of Banks has championed financial literacy and estate planning as core components of wealth management .
As custodians of financial assets, banks “operate at the intersection of financial literacy, legal accountability, and social stability” . Many are now integrating estate management services into their private and retail banking models, offering will drafting partnerships, trust administration, and insurance-backed estate transfer products .
The editorial observation: The tools exist. The banks are offering them. The only missing ingredient is action. Most Ghanaians will spend weeks researching the best phone or the best car. They will spend a decade saving for a house. But they will not spend an afternoon writing a will. That is not a resource problem. It is a priority problem. And the cost of that misprioritisation is paid by the children you leave behind. Do not make them pay it.
The International Lessons: What Ghana Can Learn
Ghana does not have to invent estate planning from scratch. Other countries have faced similar challenges and developed solutions.
The United Kingdom
In the UK, structured estate planning has contributed to “greater efficiency in asset distribution and a steady increase in charitable giving through wills and trusts” . The key has been normalising estate planning as a routine part of financial life.
Singapore
Government-led awareness campaigns have significantly improved citizens’ understanding of estate management, resulting in “a marked rise in will registration rates since 2015” . Singapore demonstrates that public education can change behaviour.
Kenya
Kenya’s Family Bank Trust Product, introduced in 2022, integrates savings, insurance, and inheritance planning. Ghana’s banking sector can draw lessons from such innovations while tailoring similar products to fit its own socio-cultural and regulatory environment .
South Africa
Collaboration between banks, legal chambers, and tax authorities has led to the creation of an Estate Duty Tracker that “enhances compliance and reduces delays in the transfer of assets” .
The implication for Ghana: None of these solutions are beyond our reach. They require political will, banking sector innovation, and—most importantly—a change in cultural attitudes. The conversation must move from “estate planning is for the rich” to “estate planning is for everyone.”
A Generational Wealth Checklist for Ghanaian Families
Use this checklist to assess your current generational wealth readiness and identify gaps.
Mindset and Habits:
-
Are you living below your means? (Savings rate above 20%?)
-
Do you save before you spend, or spend before you save?
-
Have you avoided lifestyle inflation? (Are your expenses growing slower than your income?)
-
Are you investing in assets, not just consuming?
Asset Accumulation:
-
Do you own land or property? Is it documented properly?
-
Do you have financial assets (Treasury bills, mutual funds, stocks, pension)?
-
Do you have an emergency fund (3-6 months of expenses)?
-
If you own a business, does it have a succession plan?
Legal Transfer:
-
Do you have a written, signed, and witnessed will?
-
Have you appointed executors who know your wishes and are capable of executing them?
-
Have you considered whether a trust would better serve your family’s needs?
-
Have you discussed your estate plan with your family? (Do they know what to expect?)
Next Generation:
-
Have you started teaching your children about money, saving, and investing?
-
Are you investing in your children’s education as a form of human capital?
-
If you have a family business, have you identified and trained potential successors?
-
Have you had honest conversations with your children about inheritance? (Not specifics, but expectations?)
Professional Support:
-
Have you consulted a lawyer about your will or trust?
-
Have you discussed estate planning with your bank (e.g., UMB LegacyCare+)?
-
Are your financial records organised and accessible to your executors?
-
Have you considered the tax implications of your estate plan?
FAQ Section: Readers’ Top Questions Answered
1. What is generational wealth and how is it different from regular wealth?
Generational wealth is assets that are preserved and passed from one generation to the next—creating a foundation that each generation can build upon. Regular wealth (a high salary, a comfortable lifestyle) disappears when the earner stops working. Generational wealth (land, property, businesses, investment portfolios, trusts) continues providing value after you are gone.
2. Why do most Ghanaians not have a will?
Cultural perceptions are the primary barrier. Many people regard writing a will as an omen of death or believe that estate planning is only necessary when wealth reaches a certain level . Additionally, lack of awareness, perceived complexity, and the cost of legal services deter people. However, only about 10 per cent of Ghanaian adults have a written will , meaning 90 per cent rely on the Intestate Succession Law—a default framework that may not reflect their wishes.
3. What happens if I die without a will in Ghana?
The Intestate Succession Law, PNDCL 111, governs distribution. While it provides a framework, it does not account for blended families, children from multiple relationships, estranged relatives, or special bequests. The result is often family disputes, prolonged legal battles, and assets that are “locked in probate or lost in succession disputes for years” .
4. What is a trust and do I need one in Ghana?
A trust is a legal arrangement where a trustee holds assets on behalf of beneficiaries. Trusts are more flexible than wills: they can provide for children over time (e.g., monthly distributions), protect assets from creditors or divorce, reduce tax burdens, and ensure professional management. Ghana’s Trusts Act of 2020 provides the legal framework. For high-net-worth families with diverse assets, a trust is “a crucial tool for asset protection, wealth transfer, tax efficiency, legacy planning, and long-term security” . For middle-income families, simplified trust products are emerging.
5. How do I start a generational wealth plan if I have a modest income?
Start with the mindset shift: the “smart life” over the “soft life” . Save consistently (even small amounts), invest in accessible instruments (Treasury bills, mutual funds), prioritize land and property when possible, and—crucially—write a will. The barrier is not income. The barrier is discipline and planning. As one commentator noted, “the barrier to entry for building wealth isn’t a massive bank balance; it’s the mindset to start small and stay the course” .
6. What assets are best for building generational wealth in Ghana?
Land and property remain the most trusted asset class, as they appreciate and can be passed down . Financial assets (Treasury bills, mutual funds, pension funds, stocks) provide liquidity and divisibility. A family business, properly governed and with a succession plan, can generate income across generations. Education and human capital—investing in your children’s knowledge and skills—is an invisible but essential asset.
7. How do I handle inheritance with multiple children to avoid disputes?
The most important step is a clear, written will that specifies who gets what. Without a will, disputes are almost guaranteed. Beyond the will, consider equalizing inheritances across children (e.g., the child who receives the house receives less cash). For property that cannot be easily divided, consider a family trust that holds the asset for the benefit of all children, with clear rules for its use and eventual distribution.
8. How does the banking sector help with generational wealth planning?
Banks like UMB have launched products such as LegacyCare+ to help customers plan and manage their estates, ensuring that dependents are protected and assets are seamlessly transferred . The Ghana Association of Banks has championed financial literacy and estate planning as core components of wealth management . Many banks now offer will drafting partnerships, trust administration, and insurance-backed estate transfer products.
9. How do I prepare my children to manage inherited wealth?
Start early. Teach them about money, saving, and investing. Involve them in family financial discussions (age-appropriately). If you have a family business, let them work in it—not as heirs, but as employees. Allow them to make decisions—and mistakes—while you are still there to guide them. The IFC’s workshops emphasize preparing “next-generation leaders early and intentionally” .
10. Is it too late to start generational wealth planning if I am over 50?
It is later than ideal, but it is not too late. The most urgent action is to write a will—this ensures that whatever you have accumulated goes to the people you intend. If you have a business, create a succession plan. If you have property, document it properly. You may not have decades of compounding ahead, but you can ensure that the wealth you have built is not lost to disputes and legal fees. Do not delay further. Every day without a will is a day your family is at risk.
Conclusion: The Legacy You Choose to Leave
Let me return to the 85 per cent.
Eighty-five per cent of Ghanaian adults die without a will. Their wealth—the houses, the land, the businesses, the savings—enters a legal maze. Their families enter a battlefield. The assets that could have educated grandchildren, started businesses, provided security—those assets are eaten by lawyers, frozen in probate, divided so many times that nothing remains.
This is not a law of nature. It is a choice. Not a single, dramatic choice, but thousands of small choices to postpone, to avoid, to tell yourself “I will do it next year.”
The person who writes a will is not admitting they will die soon. They are admitting they love their family enough to protect them from uncertainty. They are choosing to be the 15 per cent who plan rather than the 85 per cent who leave chaos.
The person who builds generational wealth is not trying to control their children from the grave. They are giving their children a foundation—a house that is paid for, a business that can support them, an education that opens doors. They are breaking the cycle of starting from zero.
In Proverbs 13:22, the scripture says, “A good man leaves an inheritance for his children’s children” . That is not a command to be wealthy. It is a call to be thoughtful. To plan not just for your own life, but for the lives that come after.
The soft life is comfortable. But the smart life is sustainable . The soft life spends. The smart life builds. The soft life consumes. The smart life preserves.
Which one will you choose?
Write the will. Buy the land. Start the trust. Train the children. Have the difficult conversations.
Build the wealth—not for yourself, but for the generations who will never know your name but will live in the house you built, study from the fund you created, and start from the foundation you laid.
That is generational wealth. That is the only wealth that outlasts time. That is the wealth worth building.
Start today.
Source: Accra Street Journal
Last Updated on May 30, 2026 by Samuel Kwame Boadu
Disclaimer: Some content on Accra Street Journal may be aggregated, summarized, or edited from third-party sources for informational purposes. Images and media are used under fair use or royalty-free licenses. Accra Street Journal is a subsidiary of SamBoad Publishing Hub under SamBoad Business Group Ltd, registered in Ghana since 2014.
For concerns or inquiries, please visit our Privacy Policy or Contact Page.

Samuel Kwame Boadu is a Ghanaian media entrepreneur and storyteller with a passion for amplifying urban voices and uncovering everyday truths. He is the Editor-in-Chief and Founder of Accra Street Journal, a dynamic digital platform dedicated to capturing the pulse of Ghana’s capital—its people, culture, challenges, business, sports and innovations.