








4 min read
Summary: Despite Ghana’s Finance Minister announcing that the country has paid off GH¢9.1bn ($1.1bn) in energy sector arrears, risks still linger according to local reports. The government has paid off debts to IPPs, fuel suppliers and other electricity industry players, however, the sector continues to pose a significant fiscal risk due to legacy issues and financial shortfalls.
ACCRA — Ghana’s announcement that it has cleared GH¢9.1 billion in energy sector arrears as of mid-2025 would, in any other economic cycle, be cause for applause. Yet, beyond the press releases and fiscal optimism laid out by Finance Minister Cassiel Ato Forson in the Mid-Year Budget Review, one truth remains clear: the energy sector continues to function as a persistent fiscal time bomb, masked by temporary injections of public cash.
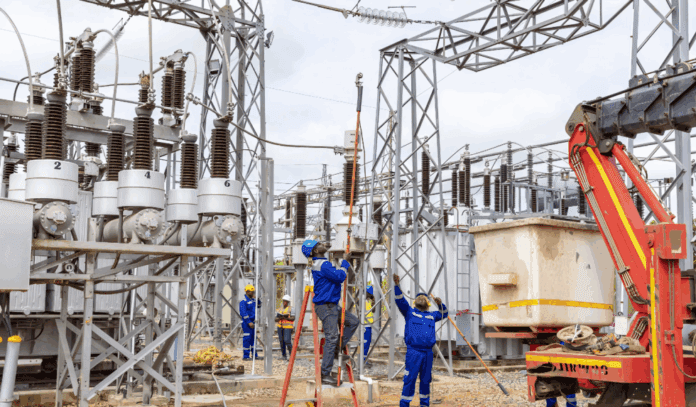
According to C-NERGY Global Holdings and sighted by Accra Street Journal, a private investment and advisory firm, the government’s sweeping settlement of debts owed to independent power producers (IPPs), bulk fuel suppliers, and other key players in the electricity value chain was critical to stabilizing generation and distribution. But this comes after years of financial shortfalls and legacy obligations that have, time and again, threatened to derail Ghana’s macroeconomic recovery.
Key Takeaways
- ACCRA — Ghana’s announcement that it has cleared GH¢9.1 billion in energy sector arrears as of mid-2025 would, in any other economic cycle, be cause for applause.
- In 2020, under President Akufo-Addo’s administration, energy debts ballooned above GH¢12 billion, prompting restructuring talks and temporary relief through the Energy Sector Recovery Programme (ESRP).
- Without a credible cost-recovery framework, enhanced regulatory independence, and improved governance at state-owned utilities, energy sector liabilities will likely re-accumulate by 2027.
This recent clearance includes payments not only within the energy sector but also extends to domestic contractors, the Social Security and National Insurance Trust (SSNIT), the District Assemblies Common Fund, and even Eurobond holders. The fiscal maneuvering required to meet these obligations without destabilizing inflation or the Ghanaian cedi is indeed notable under the current IMF-supported economic program. However, policy watchers are rightfully cautious.
A History of Energy Debt and Hollow Reforms
This is not Ghana’s first fiscal rodeo with the energy sector. From the aftermath of the 2014–2016 power crisis (dumsor) to the post-COVID liquidity challenges, successive governments have resorted to clearing arrears as a short-term fix. In 2020, under President Akufo-Addo’s administration, energy debts ballooned above GH¢12 billion, prompting restructuring talks and temporary relief through the Energy Sector Recovery Programme (ESRP). Yet, years later, systemic inefficiencies continue to plague the system.
Tariffs remain below cost-reflective levels, political interference discourages timely adjustments, and the Electricity Company of Ghana (ECG) is still hemorrhaging revenue due to commercial and technical losses estimated at over 24% of distributed power. Add to that the perennial issue of state institutions defaulting on electricity payments, and what emerges is a sector structurally dependent on Treasury bailouts.
Macroeconomic Gains or Political Window Dressing?
To the government’s credit, the GH¢9.1 billion disbursement avoided market panic. Inflation stayed within single digits in June 2025, the cedi held steady at GHS 13.20 to the dollar, and bond yields continued to fall on the domestic debt market. Investors—particularly those eying Ghana’s potential return to the Eurobond market in 2026—welcomed the fiscal discipline.
But critics suggest the payments may be more tactical than transformational. With elections looming in 2026, some observers argue that this could be a bid to stabilize economic indicators long enough to regain political ground. The IMF will be watching carefully: one-off payments do not equate to sustainable reforms, and Ghana has yet to fully deliver on structural benchmarks tied to energy sector governance, especially in enforcing power purchase agreement (PPA) renegotiations and digitizing revenue collection at ECG.
The Unfinished Agenda: What Must Change
The Finance Ministry continues to act as the silent insurer of a failing power system. Without a credible cost-recovery framework, enhanced regulatory independence, and improved governance at state-owned utilities, energy sector liabilities will likely re-accumulate by 2027. Ghana’s debt-to-GDP ratio, already projected at 68.7% by end-2025, cannot afford another wave of hidden liabilities.
Moreover, while private sector confidence has been temporarily restored, rating agencies remain cautious. A recent S&P commentary flagged the “re-emerging off-balance-sheet risks” as a downside to Ghana’s fiscal consolidation narrative.

The government may have bought itself time, but not immunity. The challenge is not paying debt—it is avoiding it in the first place.
Last Updated on July 28, 2025 by Samuel Kwame Boadu

Disclaimer: Some content on Accra Street Journal may be aggregated, summarized, or edited from third-party sources for informational purposes. Images and media are used under fair use or royalty-free licenses. Accra Street Journal is a subsidiary of SamBoad Publishing Hub under SamBoad Business Group Ltd, registered in Ghana since 2014.
For concerns or inquiries, please visit our Privacy Policy or Contact Page.

Samuel Kwame Boadu is a Ghanaian media entrepreneur and storyteller with a passion for amplifying urban voices and uncovering everyday truths. He is the Editor-in-Chief and Founder of Accra Street Journal, a dynamic digital platform dedicated to capturing the pulse of Ghana’s capital—its people, culture, challenges, business, sports and innovations.
Use the following reference when citing or referencing this article.
Your feedback helps us improve our journalism.
Report an Error
Help us maintain accuracy. Let our editorial team know if you spot an issue in this article.
Report a problem with this article