










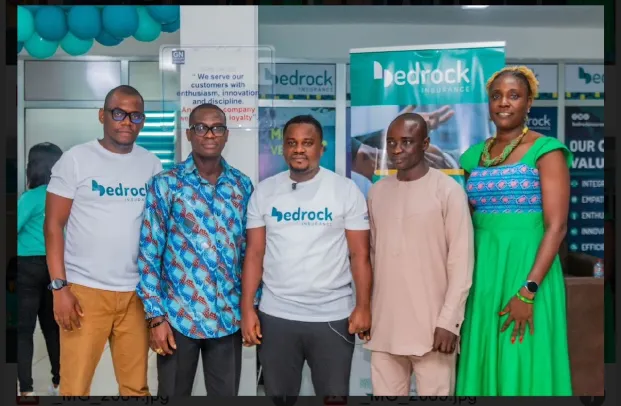

Founded in 2018 with a promise to pay genuine claims on the same day, this wholly-owned Ghanaian non-life insurer has eschewed the frenzy of AI-powered chatbots for a fiercely loyal army of 201-500 employees and a network of top-performing agents stretching from Aflao to Techiman. Now under the leadership of Ernest Frimpong, it is proving that in a trust-deficit industry, speed and relationships still beat flashy gimmicks.

Executive Introduction
In the crowded and often noisy landscape of Ghanaian general insurance, where established giants tout century-old legacies and middle-tier players compete on the sophistication of their mobile apps, Bedrock Insurance Ltd represents a return to first principles: speed, simplicity, and the primacy of people.
Launched officially in May 2019, Bedrock is one of the younger entrants in the non-life market. Yet, in just seven years of active operation, it has carved out a defensible niche. It has done so by making a radical promise: same-day payment for genuine claims. In a sector plagued by public perception issues regarding delayed settlements, that single guarantee is a powerful differentiator.
📢 GET A DETAILED ARTICLES + JOBS
Join ASJ's WhatsApp Channel and never miss a post or opportunity.
Bedrock is not chasing the same customers as the market leaders. While Enterprise and SIC battle for lucrative public sector tenders, and Activa and Star ramp up their digital ad spends, Bedrock is quietly building a fortress in the microcosm of agents and brokers. In July 2025, the company held its annual Agency Awards, showering its top performers with refrigerators, smart televisions, and air-conditioners—a tangible testament to the fact that Bedrock views its distribution network not as a cost line, but as its primary asset.
For the corporate risk manager, insurance analyst, and retail customer, Bedrock Insurance represents a case study in bootstrapped resilience. It lacks the deep pockets of a multinational parent or the decades of reserves of the old guards. Instead, it competes on operational efficiency, a flat hierarchy that allows for rapid claims processing, and a fiercely loyal workforce of 201-500 people.
This profile examines the 2018 founding under CEO Albert Eyeson-Ghansah, the 2024 leadership transition to Ernest Frimpong (a former regulator and current Board Member of the Ghana Insurers Association), the strategic importance of the agency network, its comprehensive non-life product suite, and the critical question: Can a young, wholly-owned Ghanaian insurer scale its “same-day claims” promise profitably without the reinsurance muscle of a Sanlam or an Allianz?
Company Overview
The Genesis: Born from a Vision of Simplicity (2017-2019)
Bedrock Insurance Company Limited was incorporated in Ghana under the Companies Code, 1963 (Act 179), as a privately wholly-owned Ghanaian company. The company obtained its operating license from the National Insurance Commission (NIC) in December 2017, a significant milestone that came after the tumultuous banking sector cleanup but before the final wave of minimum capital increases for insurers.
The company officially commenced operations in February 2018. However, the “official launch” to the public did not occur until May 30, 2019, a strategic decision likely made to ensure the backend infrastructure—specifically the “robust software” and Line of Business (LOB) system—was solid before taking on mass-market retail business.
The Founding Promise:
At the launch, founding CEO Albert Eyeson-Ghansah laid out the blueprint that would define the company’s brand identity:
-
Simplicity: “We aim to help people freely pursue their dreams… by making insurance simple.”
-
Speed: “Ensuring claims are made within same day.”
-
Technology: “We’ve spent time to prepare ourselves – implementing a robust software which goes live in tandem with our launch.”
With the blessing of then-Commissioner of Insurance, Justice Yaw Ofori, who urged the company to avoid the industry-wide plague of “under-pricing,” Bedrock entered the fray with a clear, value-driven proposition rather than a race to the bottom on price.
The Leadership Evolution: From Eyeson-Ghansah to Frimpong
Albert Eyeson-Ghansah (Founding CEO):
Eyeson-Ghansah was the architect of Bedrock‘s initial business model. He focused heavily on corporate governance, the technological backbone, and creating a “values-based company” built on Integrity, Empathy, Innovation, Efficiency, and Enthusiasm. He led the company through its formative years and the immediate post-COVID economic turbulence.
Ernest Frimpong (Current CEO/MD):
As of May 2026 (and confirmed by recent events such as the July 2025 Agency Awards), the Managing Director is Mr. Ernest Frimpong. Frimpong is not an external hire but a deep expert in the Ghanaian insurance ecosystem.
The Regulator Turned Operator:
Frimpong‘s background is arguably his greatest asset. He previously worked at the National Insurance Commission (NIC) for nearly 11 years (from September 2004 to August 2015). During his tenure at the NIC, he served as Board Secretary and Special Assistant to the Commissioner of Insurance. This gives him an intimate understanding of the regulatory red lines, the financial reporting requirements, and the strategic direction of the industry from the government‘s perspective.
Prosperity at Loyalty & Bedrock:
Before taking the helm at Bedrock, Frimpong was the Managing Director of Loyalty Insurance Company Limited. He also spent significant time at Priority Insurance and holds a Master‘s Degree in International Affairs from the University of Ghana, in addition to his ACII (Chartered Insurer) qualifications.
Industry Influence:
Frimpong is currently a Board Member of the Ghana Insurers Association (GIA) and chairs the GIA‘s Public Relations and External Liaison Committee. He is also a Board Member of the ECOWAS Brown Card Insurance Scheme (Ghana National Bureau).
His dual role is strategically potent: he chairs the main communication committee for the entire industry, giving him a megaphone to shape public perception, while also running a company that relies heavily on public trust.
Operations and Footprint
Headquarters: Bedrock Insurance is headquartered in Accra, with the LinkedIn corporate page listing the location on Tafawa Balewa Street.
Workforce:
Data from LinkedIn indicates the company employs between 201-500 people (updated as of May 2026). This is notable—Bedrock is not a “boutique” insurer. It has a significant payroll, supporting a substantial sales force and claims administration team.
Regional Presence:
While the headquarters are in Accra, the company’s agency network is its operational backbone. The 2025 Agency Awards explicitly recognized agents from Accra, Tema, Kumasi, Techiman, Takoradi, and Aflao. This geographic spread confirms Bedrock‘s ambition to be a national (rather than merely Accra-centric) insurer, covering the Ashanti Region, the Bono East Region, and the Volta Region.
Company Metrics:
| Metric | Value |
|---|---|
| Incorporation | 2017 (Licensed Dec 2017) |
| Commenced Ops | February 2018 |
| Official Launch | May 30, 2019 |
| Headquarters | Tafawa Balewa Street, Accra |
| Industry | Non-Life / General Insurance |
| Ownership | Wholly Ghanaian-owned (Private) |
| Founding CEO | Albert Eyeson-Ghansah |
| Current CEO | Ernest Frimpong (Chartered Insurer) |
| Employees | 201–500 |
| Key Regions | Accra, Tema, Kumasi, Techiman, Takoradi, Aflao |
Business Model: High-Touch Distribution, High-Speed Claims
Bedrock‘s business model is built on a tripod of extensive agency distribution, claims processing speed, and strict underwriting discipline (avoiding the ‘ruinous competition‘ of under-pricing flagged by the Commissioner of Insurance).
Distribution: The Agent as Hero
Unlike Donewell, which pushes a WhatsApp bot, or Star, which touts AI, Bedrock‘s growth strategy is decidedly low-tech, high-touch.
The company segments its clientele into three distinct channels:
-
Retail & Personal Line Clients: Individuals buying motor or home insurance. This is the volume game.
-
Corporate Client: Medium to large organizations (including SMEs) purchasing commercial lines such as Fire, Motor Fleet, and Liability policies via direct sales.
-
Broker Driven Clients: Large corporate entities and multinationals who purchase through external insurance brokers.
The Agency Awards (2025):
The most illustrative data point for Bedrock‘s business model is the 2025 Agency Awards. The rewards were substantial:
-
Regional Agents: Rice cookers.
-
CEO‘s Loyalty & Long Service Award: Air fryers.
-
2nd Runner Up (Gloria Serwaa): Double-door fridge.
-
1st Runner Up (Philip Taylor): 45” Smart TV.
-
Overall Best Agent (Richard Adu Sarfo): An air conditioner.
CEO Ernest Frimpong stated at the event: “Our agents are the backbone of our business. Their resilience, loyalty, and relentless drive continue to fuel our growth”.
This is a high-engagement, high-commission model. Bedrock invests significant capital into agent retention because it views the relationship between a policyholder and their agent as the primary differentiator against the faceless digital insurance apps entering the market.
The “Same-Day Payment” Promise
Bedrock‘s marketing slogan is “making insurance effortless with same day payments for genuine claims”.
How this works:
Bedrock leverages a robust Line of Business (LOB) software system that automates underwriting and integrates with claims assessment. By building a lean management team and possibly direct relationships with police and fire services (they offer claims advisory support based on relationships with the Fire Service and Police), they reduce the bureaucratic drag that slows down competitors.
The Strategic Value:
In the insurance capital city of Accra, many policies are similar. If premiums are comparable, the decision often comes down to: “Who pays the fastest?” Bedrock is betting that speed of settlement is the ultimate customer retention tool.
Product Portfolio: A Full Non-Life Suite
Bedrock is not a specialist; it is a generalist in non-life insurance. It offers the full spectrum of general insurance products:
| Category | Specific Products |
|---|---|
| Motor | Third Party, Third Party Fire & Theft, Comprehensive |
| Fire & Allied Perils | Assets All Risks, Home Protection, Commercial Premises, Business Interruption |
| Engineering | Contractors All Risks, Erection All Risks, Machinery Breakdown, Electronic Equipment |
| Liabilities | Product Liability, Public Liability, Employer‘s Liability, Professional Indemnity, Directors & Officers |
| Bonds | Bid Bonds, Performance Bonds, Mobilization, Retention, Customs |
| General Accident | Fidelity Guarantee, Bankers Indemnity, Goods-in-Transit, Cash-in-Transit, Personal/Group Accident |
| Marine | Hull, Cargo |
This diverse suite allows Bedrock to cross-sell effectively. A client buying a simple Third-Party Motor policy is a lead for a Home Protection or Goods-in-Transit policy.
Market Position and Competition
Bedrock Insurance operates in the lower mid-tier of Ghana‘s non-life insurance market. It lacks the raw claims payout volume of Activa (GHS 223M) or the asset base of Enterprise. However, it occupies the “accessible local alternative“ niche.
The “Local Challenger” Status
Bedrock competes directly with insurers like Donewell (affordable mass market) and Vanguard (steady indigenous player). However, Bedrock differentiates itself through its explicit technology promise (same-day payments) and its aggressive agent incentive structure.
Competitive Advantages
1. Insider Regulatory Knowledge
CEO Ernest Frimpong spent a decade at the NIC. He knows exactly how the Commission audits books and what regulatory changes are on the horizon before they are public. This allows Bedrock to be proactive rather than reactive.
2. The Speed-to-Payment Moat
The “same-day payment” promise is a tangible, measurable differentiator. In a KPMG-style customer experience survey, Bedrock would likely score very high on the “Claims Settlement” metric—the single most important driver of customer loyalty in insurance.
3. Loyalty of the Sales Force
The 2025 Agency Awards demonstrate that Bedrock is willing to invest heavily in its distribution network. A motivated agent who feels valued by receiving a 45” Smart TV is more likely to sell Bedrock policies over a competitor‘s.
4. Indigenous Ownership Trust
In Ghana, there is a segment of the population—particularly in SMEs—that prefers to deal with wholly-owned Ghanaian firms rather than multinationals (Allianz, Activa) or state-owned enterprises (SIC). Bedrock fits this profile perfectly.
Competitive Disadvantages
1. Short Financial Track Record
With operations starting effectively in 2018, Bedrock has just over 7 years of claims history. For large infrastructure projects or multi-year liability contracts, risk managers often require to see a 10+ year track record of stability.
2. Lack of a Life License
Bedrock is a non-life specialist. It cannot offer the “bundled” deals that the GLICO Group can (where a client buys Life, Health, and Motor from one agent under one roof). Bedrock loses the cross-sell synergy to group structures like GLICO or Enterprise Group.
3. Pressure on Loss Ratios
Paying claims fast is expensive if your premium pricing is wrong. Bedrock must maintain strict underwriting discipline to avoid the “ruinous competition” trap of under-pricing. If they misprice a large marine or fire risk, a high-speed payout could wipe out a quarter‘s profit.
4. Visibility Gap
Bedrock does not have the mass-market brand recognition of Enterprise or Star Assurance. A random taxi driver in Madina might know “Enterprise” as the default. Bedrock relies heavily on its agents to close the trust gap.
5. Vulnerability to Inflation
Same-day payment in a high-inflation environment means Bedrock must hold significant liquid reserves. If the cedi depreciates rapidly, the real value of those reserves (and the premiums collected) erodes faster than the claims come in.
Technology and the “Same-Day” Engine
Bedrock‘s technological philosophy is utility over frills. While they compete with Star‘s “Pokuaa” AI in form, they do not compete in function. Bedrock‘s tech stack is designed to solve the back-office bottleneck.
The LOB System:
At launch, Bedrock implemented a new Line of Business (LOB) System. This system likely integrates quotes, policy issuance, endorsements, renewals, and claims.
Claims Processing:
The system enables the “same-day” promise by reducing manual data entry. An agent inputs a claim, and the system instantly checks the policy validity. While the claim still requires a surveyor (for Fire/Motor), the administrative approval is accelerated.
Value-Added Services:
Bedrock offers risk improvements and claims advisory support based on relationships with the Ghana Fire Service and Ghana Police Service. This is a practical use of technology—helping clients secure their premises to prevent claims, which is better for the client and the insurer.
Challenges and Risks
No analysis of a young insurance company is complete without addressing the structural headwinds.
Risk 1: The Underwriting Cycle
Bedrock is seven years old. The underwriting cycle in insurance is about 7-10 years (a cycle of soft markets where everyone cuts prices, followed by hard markets where prices rise). Bedrock has yet to navigate a major industry-wide “hard market” crisis where reinsurance capacity dries up.
Risk 2: Dependency on Key Leadership
Ernest Frimpong is currently the linchpin. His dual role as CEO and GIA Committee Chair gives him immense influence. If he were to step away, the company would lose its primary interface with the regulator and its strategic visionary.
Risk 3: Economic Headwinds (Inflation & Cedi)
-
Spare Parts Inflation: For motor claims, the cost of replacement parts is skyrocketing due to the cedi‘s weakness against the dollar. “Same-day” claims require immediate cash outlay.
-
Reinsurance Costs: Bedrock pays for reinsurance in foreign currency. A weak cedi makes this expensive.
Risk 4: The Fintech Disruption
Bedrock relies on agents. If a large player (like Hollard with ChatInsure) successfully deploys a “no-agent” model where customers buy fully digitally with zero commission, Bedrock‘s cost base (those refrigerators and air conditioners) becomes a liability that the digital insurers do not have.
Risk 5: Brand Confusion
The name “Bedrock” does not explicitly say “insurance” (unlike “Donewell Insurance” or “Enterprise”). While memorable, it lacks immediate category definition for the average Ghanaian consumer.
Future Outlook
As of 2026, Bedrock Insurance is in its growth phase. The leadership has stabilized under a former regulator, the agency network is national, and the brand promise is clear.
The Immediate Agenda (2026-2027)
-
Deepening Regional Dominance: Leveraging the success in Techiman and Aflao to push further into the northern and volta corridors.
-
Digital Agent Tools: Introducing a mobile app specifically for agents to issue quotes and bind risks on the spot, reducing the paperwork lag.
-
Expanding the Bond Portfolio: Bonds (Bid, Performance, Retention) are high-premium, low-claims risks. Bedrock will likely target government tenders requiring these bonds.
The Bull Case (Optimistic)
-
The Consolidation Play: As the NIC continues to enforce the Minimum Capital Requirement (GHS 50M for Non-Life), smaller players will be forced to merge. Bedrock, with its clean balance sheet and 201-500 staff, could act as a consolidator, absorbing smaller agencies to expand broker networks.
-
The Recession Boom: In a downturn, consumers become more risk-averse but cash-poor. They switch to reliable but cheaper insurers. Bedrock’s “affordable” positioning could capture volume fleeing premium-priced incumbents.
-
Successful Cross-Sell: Bedrock successfully converts its 50,000 motor policyholders into Home Insurance buyers, creating a sticky, multi-product relationship.
The Bear Case (Pessimistic)
-
The Race to Zero: A price war breaks out in the motor market. Bedrock, having promised “same-day” high-quality service, refuses to cut corners on claims, losing price-sensitive customers to discounters.
-
Leadership Fatigue: The dual role of GIA leadership and running a fast-growing firm burns out the CEO, leading to strategic drift.
-
The Big Data Debacle: A major fire claim (e.g., a bonded warehouse) runs into the tens of millions. The speed of payment required by the brand ethos clashes with the slow speed of investigation by the loss adjusters.
The Verdict
Bedrock Insurance Ltd is arguably the most professionally managed new entrant in Ghana‘s non-life sector. It has avoided the trap of under-pricing that plagues the industry. Instead, it has chosen to compete on operational speed and agent loyalty.
The 2025 Agency Awards, offering air conditioners and fridges to sales agents, is not a gimmick. It is a strategic signal that Bedrock views the human agent as the ultimate competitive shield against the faceless fintechs that are trying to disrupt the industry.
Under the stewardship of Ernest Frimpong, the company has the unique advantage of insider knowledge—he knows exactly how the regulator thinks because he used to be the regulator. This allows Bedrock to navigate the compliance minefield faster than its peers.
However, the lack of a massive data set (7 years of history) means that Bedrock is still in the trust-building phase. Large multinationals may still look to Enterprise for a AAA rating, and price-sensitive consumers may still go to their agent for the cheapest quote.
Bedrock is not trying to be the market leader. It is trying to be the safest, fastest choice for the Ghanaian who values their time and wants to know their claim will be paid before the sun goes down. For that segment of the market, Bedrock is rapidly becoming the default.
FAQ SECTION
1. Is Bedrock Insurance a Ghanaian-owned company?
Yes. Bedrock Insurance Company Limited is a wholly-owned Ghanaian private company.
2. When was Bedrock Insurance established?
The company was incorporated in 2017 and obtained its license from the National Insurance Commission in December 2017. It commenced operations in February 2018 and officially launched in May 2019.
3. Who is the CEO of Bedrock Insurance?
The current Managing Director and CEO is Mr. Ernest Frimpong. He is a Chartered Insurer and a former employee of the National Insurance Commission (NIC).
4. Who was the founder of Bedrock Insurance?
The founding CEO was Mr. Albert Eyeson-Ghansah, who led the company during its 2019 public launch.
5. What is Bedrock Insurance known for?
Bedrock is primarily known for its same-day payment of genuine claims. They market themselves as the “people‘s insurance company,” making insurance effortless.
6. What types of insurance does Bedrock offer?
Bedrock offers a comprehensive range of non-life insurance products including Motor, Fire, Marine, Engineering, Liability, Bonds, and General Accident policies.
7. Where is Bedrock Insurance headquartered?
The company is headquartered on Tafawa Balewa Street in Accra.
8. How many employees does Bedrock have?
Bedrock Insurance employs approximately 201-500 people, according to its LinkedIn corporate profile.
9. Is Bedrock active outside Accra?
Yes. Bedrock has a strong regional agency network with recognised top agents in Tema, Kumasi, Techiman, Takoradi, and Aflao.
10. Who is Ernest Frimpong‘s background?
Ernest Frimpong previously served as the Managing Director of Loyalty Insurance Company Limited. Before that, he spent nearly 11 years at the National Insurance Commission (NIC). He is currently a Board Member of the Ghana Insurers Association (GIA).
11. How does Bedrock reward its agents?
Bedrock holds an annual Agency Awards event. In 2025, top agents won prizes including double-door refrigerators, 45” Smart TVs, air conditioners, and rice cookers.
12. Does Bedrock have a specific insurance app?
While the company utilizes a robust Line of Business (LOB) software system for backend operations, its primary distribution and customer interface remains its network of agents and brokers, rather than a direct-to-consumer mobile app.
QUICK FACTS BOX
| Item | Details |
|---|---|
| Founded | 2017 (Licensed) / 2018 (Operations) / 2019 (Public Launch) |
| Headquarters | Tafawa Balewa Street, Accra, Ghana |
| Industry | Non-Life / General Insurance |
| Services | Motor, Fire, Marine, Engineering, Liability, Bonds, General Accident |
| Ownership | Wholly Ghanaian-owned (Private) |
| Founding CEO | Albert Eyeson-Ghansah |
| Current CEO (MD) | Ernest Frimpong (Chartered Insurer, ex-NIC) |
| Employees | 201–500 |
| Key Differentiator | Same-day payment of genuine claims |
| Distribution | Extensive agency network (Agents, Brokers, Direct) |
| Key Regions | Accra, Tema, Kumasi, Techiman, Takoradi, Aflao |
| Regulator | National Insurance Commission (NIC) |
| Industry Leadership | GIA Board Member (CEO) |
| Website | bedrockinsurancegh.com |
Source: Accra Street Journal
Last Updated on May 6, 2026 by Samuel Kwame Boadu
Disclaimer: Some content on Accra Street Journal may be aggregated, summarized, or edited from third-party sources for informational purposes. Images and media are used under fair use or royalty-free licenses. Accra Street Journal is a subsidiary of SamBoad Publishing Hub under SamBoad Business Group Ltd, registered in Ghana since 2014.
For concerns or inquiries, please visit our Privacy Policy or Contact Page.

Samuel Kwame Boadu is a Ghanaian media entrepreneur and storyteller with a passion for amplifying urban voices and uncovering everyday truths. He is the Editor-in-Chief and Founder of Accra Street Journal, a dynamic digital platform dedicated to capturing the pulse of Ghana’s capital—its people, culture, challenges, business, sports and innovations.



