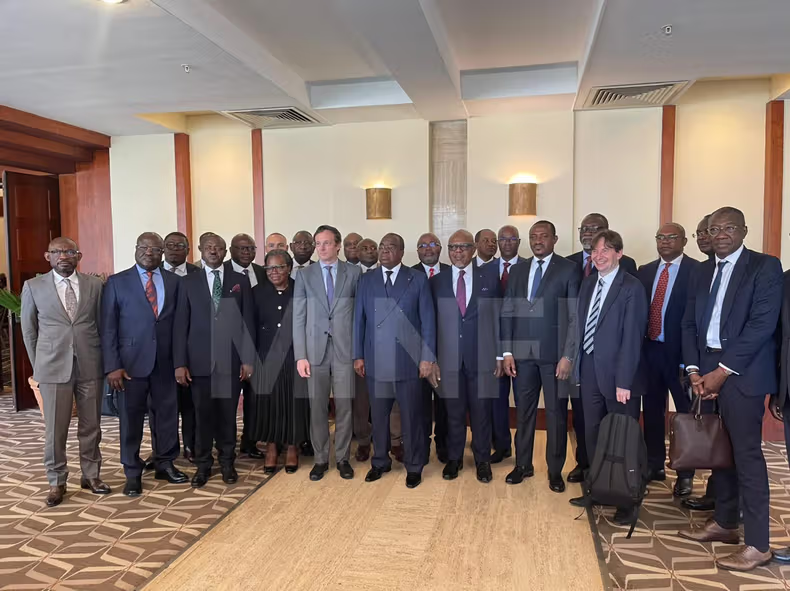
Cameroon has completed the acquisition of Société Générale’s majority stake in its local banking subsidiary, marking one of the largest state-led banking takeovers in Central Africa in recent years and signaling a broader trend of African governments stepping in as European financial institutions retreat from the continent. Under the agreement finalized on May 12, 2026, Cameroon purchased the 58.08% stake previously owned by the French banking giant for CFA129 billion (approximately $230.8 million), increasing the government’s total ownership in the lender to 83.68%. The bank has been renamed General Bank of Cameroon. Insurance group SanlamAllianz retains a 16.32% stake.
The transaction, first signed on July 15, 2025, was formally concluded during an official event chaired by Finance Minister Louis Paul Motaze, alongside Minister Delegate to the Ministry of Economy Paul Tasong and representatives of Société Générale. Officials described the move as aimed at protecting financial stability, maintaining customer confidence, and ensuring uninterrupted banking services. The acquisition strengthens state influence in Cameroon’s financial sector, where the government already holds significant stakes in Union Bank of Cameroon, NFC Bank, and Commercial Bank of Cameroon. Yet authorities have signaled that state control may not be permanent, describing the arrangement as a transitional step while creating room for new strategic investors in the future.

The deal reflects a wider pattern across Africa: European banks including Standard Chartered and BNP Paribas have scaled back operations amid tighter global regulations, rising operational costs, and shifting strategic priorities, while local investors and governments increasingly step in to acquire assets.
📢 GET A DETAILED ARTICLES + JOBS
Join ASJ's WhatsApp Channel and never miss a post or opportunity.

Key Developments: The Transaction, the Transition, and the Renaming
The acquisition of Société Générale Cameroon is the culmination of a process that began in mid-2025. The sale agreement was signed on July 15, 2025, at a cost of CFA129 billion including taxes—approximately $230.8 million at current exchange rates. The transaction closed nearly ten months later, following regulatory approvals, operational transition planning, and customer communication.
Société Générale’s exit from Cameroon is part of a broader retrenchment. The French lender has sold subsidiaries in Congo, Chad, Equatorial Guinea, and Mauritania as part of efforts to streamline operations and focus on core markets. The pattern is consistent: European banks that once competed aggressively across Africa are now retreating, citing tighter European capital requirements, rising compliance costs, and the difficulty of achieving scale in smaller markets.
Cameroon’s response is distinctive. Unlike some countries where local private investors have acquired exiting European banks, Cameroon’s government has taken direct control. The 83.68% ownership stake makes the state the dominant shareholder in the country’s second-largest bank. The government already holds stakes in other lenders, but this acquisition consolidates its position as the most influential player in the sector.
The renaming to General Bank of Cameroon is symbolic. The new identity reflects plans to build “a modern, competitive and inclusive bank” that would support the country’s economic development goals, according to the Finance Ministry. The shift from a French brand to a national one signals a break from colonial-era banking structures and an assertion of financial sovereignty.
The retention of SanlamAllianz’s 16.32% stake provides a private sector anchor. The insurance group, itself a joint venture between South Africa’s Sanlam and Germany’s Allianz, brings financial expertise and international connectivity. The government has indicated that it may seek additional private investors in the future, with the current state-controlled structure described as transitional.
Customer confidence during the transition has been a priority. Officials emphasized that the acquisition was designed to maintain uninterrupted banking services and protect financial stability. In markets where bank failures or disruptions can have cascading effects on businesses and households, the assurance of continuity is critical.
Analysis & Implications: State Control, Financial Stability, and Investment Climate
The Cameroon acquisition raises three interconnected questions: Can the government run a bank effectively? Will the state’s role crowd out private investment? And does the deal signal a broader shift toward financial nationalism in Africa?
On operational effectiveness, the record is mixed. State-owned banks in Africa have historically struggled with inefficiency, political interference, and poor asset quality. However, there are examples of successful state-led banking—such as Botswana’s National Development Bank and Rwanda’s Development Bank—where governance has been strong and lending disciplined. Cameroon’s government already holds stakes in other banks, but none as large as 83.68% of a systemically important institution. The success of General Bank of Cameroon will depend on the quality of its management, board, and internal controls.
On crowding out private investment, the risk is real. Private investors, both domestic and foreign, may be reluctant to compete with a state-owned behemoth that could receive preferential treatment. The government has signaled openness to future private investment, but potential partners will watch carefully to see whether the bank operates on commercial terms or becomes a vehicle for political lending.
On financial nationalism, Cameroon is part of a trend. Across Africa, governments are reasserting control over strategic sectors: Ghana’s mining localization policy, Nigeria’s requirement that oil companies use local contractors, and now Cameroon’s banking takeover. The driver is the same: a desire to capture more value from the economy and reduce dependence on foreign capital. But the risk is the same, too: if state control leads to inefficiency, the result is a weaker economy, not a stronger one.
Société Générale’s exit is not a panic. The French bank has been profitable in Cameroon, but its global strategy has shifted. European banks face stricter capital requirements under Basel III and IV, making it more expensive to hold minority stakes in subsidiaries. Compliance costs—anti-money laundering, know-your-customer, sanctions screening—have risen sharply. For a bank like Société Générale, with a global footprint, the cost-benefit calculus of maintaining a presence in smaller African markets no longer favors staying. The sale proceeds can be redeployed to markets where the bank has scale and competitive advantage.
The Accra Street Journal notes that Cameroon’s move contrasts with Ghana’s approach to banking sector consolidation. During Ghana’s 2017-2019 banking crisis, the government allowed weak banks to fail and encouraged stronger private banks to acquire assets, rather than nationalizing them. The result was a smaller, more resilient private banking sector. Cameroon has chosen a different path, one that prioritizes state control over private recapitalization. Which approach proves more effective will be determined over the coming decade.
What This Means for Cameroon’s Financial Sector, Businesses, and Citizens
For Cameroon’s financial sector, the acquisition consolidates state influence. The government now directly controls the second-largest bank, adding to its stakes in Union Bank of Cameroon, NFC Bank, and Commercial Bank of Cameroon. The state is no longer a regulator and a shareholder; it is a dominant player. This concentration of power could improve coordination on development lending, but it could also reduce competition and innovation.
For businesses, the impact depends on how General Bank of Cameroon operates. If the bank continues to lend commercially, on market terms, the transition may be seamless. If it becomes a vehicle for political lending—directing credit to favored sectors or firms at below-market rates—it could distort the economy. Small and medium enterprises (SMEs), which often struggle to access bank credit, may find themselves either better served (if the bank expands its SME portfolio) or worse served (if credit is allocated politically).
For citizens, the transition may be invisible. Bank branches will remain open, accounts will not be disrupted, and the new name will gradually replace the old one. However, if the bank’s efficiency declines, service quality could suffer. Longer queues, slower transaction processing, and limited digital innovation are risks. Conversely, if the government invests in upgrading technology and expanding branch networks, customers could benefit.
The government’s statement that the arrangement is transitional is important. It signals that Cameroon is not permanently committed to state ownership. The goal is to find a strategic investor—perhaps an African bank (such as Attijariwafa, Ecobank, or UBA) or a global institution (such as Standard Chartered or Citigroup)—to take a significant stake. The government’s 83.68% holding gives it negotiating power: it can sell a portion to a strategic investor while retaining a blocking minority or a golden share.
The retention of SanlamAllianz’s 16.32% stake is a vote of confidence. The insurance group could increase its stake over time, providing a pathway to private sector control. Alternatively, new investors could join alongside SanlamAllianz, creating a diversified ownership structure that combines state oversight with private sector discipline.
Wider Context: European Bank Retreat and African Financial Sovereignty
Société Générale’s exit from Cameroon is part of a broader European bank retreat from Africa. Standard Chartered has sold subsidiaries in several African countries, including Zimbabwe and Tanzania. BNP Paribas has scaled back its presence in sub-Saharan Africa. Barclays sold its African operations to Absa, a South African bank, in a landmark deal. Credit Suisse (now part of UBS) had a minimal African footprint. The trend is clear: European banks are focusing on their core markets in Europe, the Americas, and Asia, leaving Africa to local players and emerging market banks.
African governments and investors are stepping into the gap. Moroccan banks—Attijariwafa, BMCE Bank of Africa, Banque Populaire—have aggressively expanded across West and Central Africa. Nigerian banks—GTBank, UBA, Access Bank—have built pan-African networks. Ecobank, the pan-African bank headquartered in Togo, has a presence in over 30 African countries. The buyers are local, the control is local, and the strategy is local.
This shift toward African financial ownership is a form of financial sovereignty. For decades, African banking was dominated by European institutions that made strategic decisions in Paris, London, or Lisbon. Profits were repatriated; local credit allocation was secondary. Today, African-owned banks are making decisions in Accra, Lagos, Casablanca, and Nairobi. Credit allocation is more closely aligned with local development priorities.
Cameroon’s state-led takeover is an outlier within this trend. Most African acquisitions of European bank assets have been led by private African banks, not governments. The Moroccan and Nigerian banks mentioned above are publicly traded companies with private shareholders. The Cameroonian government’s direct ownership is a departure from the prevailing model. Whether it succeeds will be watched closely by other African governments considering similar moves.
The Central African context is also relevant. The region is served by the Bank of Central African States (BEAC), the common central bank for the CEMAC zone. The currency, the CFA franc, is pegged to the euro and guaranteed by the French Treasury. The banking sector is regulated by the COBAC (Central African Banking Commission), a regional supervisor. Cameroon’s acquisition does not change these structures, but it does raise questions about the relationship between state-owned banks and regional regulators.
Outlook / What Happens Next
General Bank of Cameroon will now operate under state control, but the transition period will determine its long-term trajectory. The immediate priorities are operational continuity, customer retention, and employee morale. Staff who worked for Société Générale Cameroon must adapt to new ownership, new strategy, and potentially new management. The risk of key staff departures is real; the government must ensure that the bank retains its talent.
The medium-term priority is finding a strategic investor. The government has signaled that it is open to selling part of its stake to a private partner. Potential candidates include Ecobank (which has a strong presence in Central Africa), Attijariwafa (which is expanding aggressively), or a South African bank seeking entry into the region. A private partner would bring commercial discipline, technical expertise, and international connectivity.
The long-term question is whether state ownership improves or impairs banking sector performance. The answer will be measured by indicators: loan growth, asset quality, customer satisfaction, digital adoption, and profitability. If General Bank of Cameroon underperforms, the government may be forced to recapitalize it—using taxpayer funds—or sell it at a loss. If it outperforms, the government will have demonstrated that state ownership can work in banking.
For the Accra Street Journal’s readers, the Cameroon deal is a case study in the trade-offs of financial sovereignty. State control gives a government the power to direct credit toward its priorities, but it also exposes taxpayers to banking losses. Private ownership gives efficiency and discipline, but profits flow to shareholders, many of them foreign. Cameroon has chosen a hybrid model: state control for now, with a pathway to private ownership. The execution will determine whether it is a model others copy or one they avoid.
Source: Accra Street Journal
Last Updated on May 14, 2026 by Samuel Kwame Boadu
Disclaimer: Some content on Accra Street Journal may be aggregated, summarized, or edited from third-party sources for informational purposes. Images and media are used under fair use or royalty-free licenses. Accra Street Journal is a subsidiary of SamBoad Publishing Hub under SamBoad Business Group Ltd, registered in Ghana since 2014.
For concerns or inquiries, please visit our Privacy Policy or Contact Page.

Samuel Kwame Boadu is a Ghanaian media entrepreneur and storyteller with a passion for amplifying urban voices and uncovering everyday truths. He is the Editor-in-Chief and Founder of Accra Street Journal, a dynamic digital platform dedicated to capturing the pulse of Ghana’s capital—its people, culture, challenges, business, sports and innovations.