










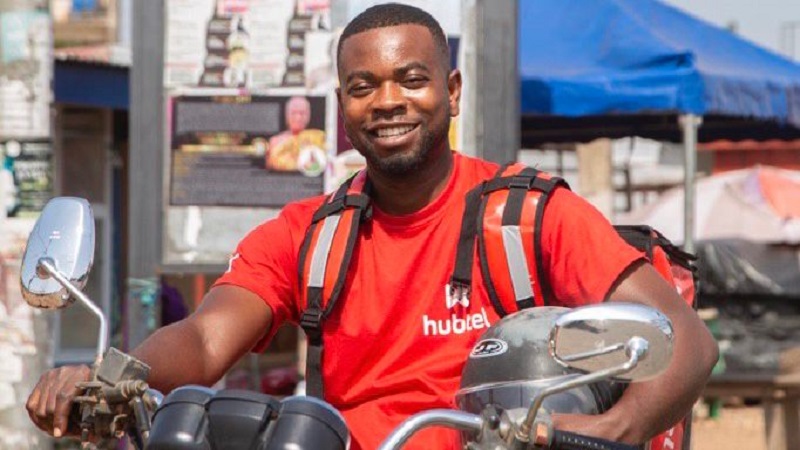

From a KNUST dorm room startup in 2005 to an omnichannel commerce platform processing billions in transactions, operating 12 offices, and employing 700+ staff, the home-grown Ghanaian giant has outlived every wave of Silicon Valley hype to become the quiet engine of the retail economy.

Executive Introduction
Two decades ago, on a university campus in Kumasi, a group of students printed business cards with a company name that barely anyone recognized—SMSGH. They had no office, no investors, and no guarantee that their idea of using text messages to connect businesses to customers would survive the first year. Today, that dorm-room experiment has evolved into Hubtel, a fintech and commerce conglomerate that stands as one of the most complete digital ecosystems ever built on Ghanaian soil.
The scope of Hubtel’s operations defies simple categorization. It is not merely a payment processor, though it is licensed by the Bank of Ghana as an Enhanced Payment Service Provider and handles mobile money, cards, and QR payments across thousands of businesses. It is not merely a bulk SMS gateway, though it pioneered that market in 2005 and remains a dominant force. It is not merely a delivery marketplace, though its app allows consumers in 11 Ghanaian cities to order food, pay bills, and receive essentials. Hubtel is, in the most ambitious sense, a platform—one that seeks to become “Africa‘s most useful company” by enabling every person and business to participate in the digital economy.
📢 GET A DETAILED ARTICLES + JOBS
Join ASJ's WhatsApp Channel and never miss a post or opportunity.
The numbers: 20 years of continuous operation, 12 offices across Ghana, over 700 employees, and a commercial footprint spanning from the capital Accra to mid-tier cities like Sunyani, Techiman, and Tarkwa. The company has survived the rise and fall of multiple technology eras, pivoting from messaging to payments to e-commerce to logistics, all while maintaining a fiercely independent, Ghanaian-owned identity.
For investors, competitors, and business leaders, Hubtel represents a masterclass in organic evolution—a company that did not raise massive foreign capital in its early years but instead grew by solving real problems for real businesses, one API at a time. This ASJ profile examines the leadership of co-founder and CEO Alex Adjei Bram, the controversial ECG PowerApp contract that brought the company into the political spotlight, the newly appointed Management Advisory Council that signals pan-African ambitions, and the fundamental question: can a Ghanaian-built platform truly scale across a fragmented continent?
Company Overview
The Genesis: From SMSGH to a Financial Super App
Hubtel was founded in 2005 under its original name, SMSGH . Its first product was a bulk SMS platform for businesses—a tool that allowed companies to send marketing messages, transactional alerts, and customer notifications directly to mobile phones at a time when such technology was still novel in Ghana.
The choice of SMS as a beachhead was strategic. Mobile penetration was rising, but smartphones and reliable internet data were years away. SMS was the only channel that reached every Ghanaian phone owner, regardless of device. The founders recognized that the infrastructure of mobile communication would be the foundation upon which digital commerce would later be built.
Bulk SMS remains a significant part of Hubtel‘s offering . Today, the platform connects directly to all major Ghanaian networks (MTN, AirtelTigo, Telecel) without relying on roaming links or grey routes, offering delivery quality guaranteed by direct carrier connectivity. Businesses can send promotional campaigns, payment reminders, and personalized alerts through an intuitive dashboard or via programmable APIs.
The company rebranded from SMSGH to Hubtel in 2017 to reflect its expanded focus on payments, e-commerce, and customer engagement tools .
The Founding Trio: Alex Bram, Ernest Apenteng, and Leslie Gyimah
Hubtel was founded by three Kwame Nkrumah University of Science and Technology (KNUST) alumni: Alex Adjei Bram, Ernest Apenteng, and Leslie Gyimah . In May 2025, during the company‘s 20th anniversary thanksgiving dinner, co-founder and CEO Alex Bram did something unconventional: instead of a standard CEO address, he read a deeply personal letter to God, recounting the crushing political loss after graduation and the early days when the founders had “no office, no investors, and a burning belief” .
The founding story is emblematic of Ghana‘s emerging tech ecosystem—homegrown, resilient, and deeply rooted in local relationships rather than foreign venture capital. As the Minister for Communication, Digital Technology and Innovations, Samuel Nartey George, noted at the same event, the founders turned a “near-failed campus event into a success story” during their university days, and that same determination has driven Hubtel‘s trajectory .
The New Management Advisory Council: Pan-African Ambitions
In September 2025, Hubtel announced the appointment of two heavyweight advisors to its Management Advisory Council, signaling a strategic push for expansion beyond Ghana .
Simon Poole brings over 30 years of capital markets experience from Bank of America, Guinness Nigeria, and Celtel International (where he was instrumental in the $3 billion acquisition by Zain). He has sat on the boards of African fintech giants Interswitch (Nigeria) and Fawry (Egypt) and served as an Operating Partner at Helios Investment Partners. His governance and capital markets expertise“could help guide sustainable growth and potential future listings”—a clear hint that Hubtel may be positioning for an initial public offering in the medium term .
Marjorie Saint-Lot currently leads Francophone Africa for Taptap Send, overseeing $300 million in monthly transactions and four market launches. She is a former Uber executive who scaled Côte d’Ivoire operations 60-fold in a single year, and a former senior leader at Orange Côte d‘Ivoire. She serves on the board of Ecobank Côte d‘Ivoire. At Hubtel, she will focus on digital strategy, cross-border expansion, and stakeholder engagement .
The appointments place Hubtel alongside Africa‘s most sophisticated fintechs, signaling that the company is preparing to compete not just in Ghana but across the continent.
Operations and Footprint
As of November 2025, Hubtel operates 12 offices nationwide and employs over 700 people . Its headquarters is located at 302 Olympics Road, Accra .
The company‘s delivery and commerce footprint now spans 11 cities across Ghana: Accra, Tema, Kumasi, Takoradi, Tamale, Cape Coast, Koforidua, Ho, Sunyani, Techiman, and Tarkwa .
Key Operational Metrics:
| Metric | Value |
|---|---|
| Founded | 2005 |
| Headquarters | 302 Olympics Road, Accra |
| Founders | Alex Adjei Bram, Ernest Apenteng, Leslie Gyimah |
| Original Name | SMSGH |
| Rebranding Year | 2017 (to Hubtel) |
| Employees | 700+ |
| Offices | 12 nationwide |
| Cities Served | 11 (Accra, Tema, Kumasi, Takoradi, Tamale, Cape Coast, Koforidua, Ho, Sunyani, Techiman, Tarkwa) |
| Bank of Ghana License | Enhanced Payment Service Provider |
| Management Advisory Council | Simon Poole (capital markets), Marjorie Saint-Lot (Francophone expansion) |
Investor Backing
Hubtel‘s latest funding round is categorized as Unattributed VC, with Chanzo Capital listed among its known investors . The company‘s funding history has been relatively modest compared to pan-African peers like Flutterwave or Chipper Cash, reflecting a deliberate strategy of organic growth. However, the appointment of Poole and Saint-Lot—and the explicit reference to “potential future listings”—suggests that this capital-efficient approach may be evolving .
Business Model: The Tri-Polar Platform
Hubtel‘s business model is best understood as three interconnected engines, each generating revenue and data that fuel the others.
Engine One: Payment Processing (Bank of Ghana Licensed)
Hubtel is licensed by the Bank of Ghana as an Enhanced Payment Service Provider . The company provides digital payment solutions that enable businesses to accept:
-
Mobile money (MTN, AirtelTigo, Telecel)
-
Bank card transactions (Visa, MasterCard)
-
QR code payments
-
Bank transfers
The payment gateway is white-label in nature: businesses can integrate Hubtel‘s APIs directly into their websites, mobile apps, and point-of-sale systems. The service is available to merchants of all sizes, from universities and hospitals to government entities and retailers .
Payment processing generates revenue primarily through transaction fees—a small percentage of every payment processed across the platform. The more merchants Hubtel onboards and the more customers use digital payments, the larger this revenue stream grows.
SMS & Money: The Unique Payment-by-Message Feature
One of Hubtel‘s distinctive offerings is SMS & Money, which allows businesses to request payments directly via text message. A merchant can upload a contact list, compose a message with a payment request, and send it to all their customers simultaneously. Recipients can pay by replying to the SMS, without needing to download an app or visit a website .
This feature is particularly valuable for businesses with customers who are not digitally native but have basic mobile phones. It bridges the gap between the formal economy and the informal customer base.
Engine Two: Bulk Messaging & Customer Engagement
SMS was Hubtel‘s founding product, and it remains a robust revenue stream two decades later . Businesses use Hubtel‘s bulk messaging platform for:
-
Marketing campaigns (promotional offers, brand announcements)
-
Transactional alerts (payment confirmations, delivery updates)
-
Payment reminders (invoice due dates, subscription renewals)
-
Two-factor authentication (security codes)
The platform connects directly to all local networks (MTN, AirtelTigo, Telecel) plus international aggregators, ensuring delivery quality that bypasses the grey routes and roaming links that plague cheaper competitors . Pricing is tiered, with discounts for higher volumes and longer commitment periods. Bundles range from GH¢10 for 380 messages to GH¢10,000 for 540,500 messages .
Use Case: Luckweb
When Luckweb, a lottery operator with global reach, needed a reliable transaction notification and prize payout system, it found that its existing provider suffered from truncated USSD codes, hung payments, and reconciliation discrepancies. After switching to Hubtel, the company integrated:
-
A Receive Money API to collect customer payments for game entries
-
A Send Money API to instantly credit winning customers
-
Bulk messaging for marketing and transactional alerts
The results: seamless collections, timely prize distributions, and a significant improvement in customer trust .
Engine Three: E-Commerce Marketplace & Delivery
The most visible face of Hubtel to the average Ghanaian consumer is its e-commerce marketplace—a mobile app that allows users to:
-
Order food from local restaurants
-
Pay utility bills (electricity, water, cable TV)
-
Buy airtime and data
-
Send money to mobile wallets and bank accounts
-
Shop for groceries and household essentials
-
Order delivery from local merchants
The app is available on both iOS and Android and serves as a daily utility for hundreds of thousands of Ghanaians. Unlike the payment and messaging services, which are B2B-focused, the e-commerce app is the company‘s direct-to-consumer channel—and its most powerful data collection engine.
Delivery Logistics
Hubtel does not merely connect buyers to sellers; it facilitates delivery through partnerships with logistics providers. The company‘s expansion into Sunyani, Techiman, and Tarkwa in late 2025 was specifically timed to bring delivery services to these mid-tier commercial hubs, each with populations exceeding 100,000 residents .
Quick Commerce
Hubtel‘s strategy aligns with the global “quick commerce” trend—ultrafast delivery of everyday essentials. By focusing on groceries, prepared meals, and household staples, the company targets high-frequency, low-margin transactions that generate customer loyalty and valuable behavioral data.
The Integrated Flywheel
The three engines are not separate businesses; they are a flywheel. Payment processing brings merchants onto the platform. SMS engagement keeps those merchants communicating with their customers. The e-commerce marketplace gives consumers a reason to use Hubtel daily. Together, they create a virtuous cycle:
-
More merchants → more payment volume → more transaction fee revenue
-
More consumers → more marketplace orders → more delivery fee revenue
-
More data → better merchant insights → higher engagement → more SMS revenue
Market Position and Competition
Industry Standing: The Indigenous Incumbent
Hubtel occupies a unique position in Ghana‘s fintech hierarchy. It is not the flashiest company (Chipper Cash and Zeepay have raised more foreign capital). It is not the most narrowly specialized. But it is likely the most comprehensive—a company that offers payment processing, SMS engagement, e-commerce, logistics, and consumer payments under a single platform.
The company‘s longevity—20 years —is its greatest asset. In a sector littered with startups that rose fast and fell harder, Hubtel has demonstrated resilience across multiple technology cycles.
Award-Winning Track Record
Hubtel‘s achievements have been recognized by multiple industry bodies:
| Award | Year | Issuing Body |
|---|---|---|
| Emerging E-commerce Initiative | 2019 | GITTA |
| Fintech Company of the Year | 2019 | GITTA |
| Digital Company of the Year | 2020 | FIN Cashless Awards |
| Fintech Company of the Year | 2022 | Ghana Fintech Awards |
| IT/Tech Firm of the Year | 2022 | Ghana Fintech Awards |
| Fintech Platform of the Year | 2022 | Ghana Fintech Awards |
| UI/UX Fintech Company of the Year | 2022 | Ghana Fintech Awards |
| Leading Payments Technologies Service Provider of the Year | 2022 | Ghana Fintech Awards |
In 2022, Hubtel was the most awarded company at the Ghana Fintech Awards, securing five accolades .
Competitive Landscape
Hubtel competes across multiple segments against specialized players:
| Competitor | Segment | Hubtel‘s Advantage |
|---|---|---|
| Zeepay | Cross-border remittances, EMI license | Full-stack platform (not just infrastructure) |
| expressPay | B2B payment gateway | Consumer marketplace + messaging + logistics |
| mNotify | Bulk SMS | Payment-plus-messaging integration (SMS & Money feature) |
| MTN MoMo | Mobile money | Independence from telco (multi-network) |
| Telecel Cash | Mobile money | Independence, merchant tools |
Hubtel‘s primary differentiator is its breadth. While Zeepay focuses on remittance infrastructure and expressPay focuses on white-label gateways, Hubtel offers a complete operating system for commerce—from the initial customer message to the final delivery confirmation.
Competitive Advantages
1. Regulatory License: Enhanced Payment Service Provider
Hubtel is licensed by the Bank of Ghana as an Enhanced Payment Service Provider . This license provides legal authority to process payments across mobile money, cards, and bank transfers—a regulatory foundation that fintechs without such licenses cannot match.
2. Direct Carrier Connectivity for SMS
Unlike SMS aggregators that route messages through third-party carriers, Hubtel connects directly to MTN, AirtelTigo, and Telecel . This improves delivery speed, reduces message loss, and provides better analytics.
3. First-Mover Advantage in Bulk SMS
Having launched in 2005, Hubtel was Ghana‘s first online SMS messaging gateway for commercial use . Two decades later, the company has built relationships with thousands of businesses that rely on its messaging platform. Switching costs for these clients are high.
4. Integrated Merchant-Consumer Marketplace
Most competitors offer payments OR messaging OR e-commerce. Hubtel offers all three on a single platform, creating a flywheel effect that specialized competitors cannot replicate.
5. Geographic Reach Across 11 Cities
Hubtel‘s expansion beyond Accra and Kumasi into mid-tier cities like Sunyani, Techiman, and Tarkwa gives it a first-mover advantage in markets that larger competitors have neglected.
6. Deep Local Ownership and Government Relationships
Hubtel is a wholly Ghanaian-owned company . This matters for government contracts, regulatory relationships, and consumer trust. The company has been publicly commended by the Minister for Communication, Digital Technology and Innovations .
Competitive Disadvantages
1. Pan-African Scale Lags Peers
Unlike Flutterwave (present in 30+ African countries) or Chipper Cash (20+), Hubtel‘s operations are concentrated in Ghana. The company‘s political risk is therefore undiversified, and its addressable market is capped by Ghana‘s population.
2. Less Venture Capital Funding
Hubtel has not raised the hundreds of millions of dollars that its pan-African competitors have secured. While this has preserved ownership and strategic independence, it has also constrained the company‘s ability to launch aggressive expansion campaigns.
3. Brand Fragmentation
Hubtel is simultaneously a payment processor, a messaging service, and a food delivery app. This breadth is a strength for cross-selling but a weakness for brand clarity. Consumers may not immediately understand what Hubtel offers.
4. The ECG Controversy Overhang
The public dispute with the Electricity Company of Ghana (ECG) regarding the PowerApp contract remains a reputational risk that competitors may exploit.
5. Exposure to Ghanaian Economic Cycles
Because Hubtel is concentrated in a single country, its performance is tightly correlated with Ghana‘s macroeconomic health. A downturn in the Ghanaian economy would affect all three engines simultaneously.
Technology and Innovation
The API-First Architecture
Hubtel provides a suite of programmable APIs that allow third-party developers and businesses to integrate payment, messaging, and commerce capabilities directly into their own applications .
Key APIs:
-
Receive Money API: Allows businesses to accept payments via mobile money, cards, or bank transfers
-
Send Money API: Enables instant payouts to mobile wallets or bank accounts
-
Programmable Messaging API: Allows businesses to send bulk SMS, personalized alerts, and payment requests programmatically
-
QR Code API: Generates and manages payment QR codes for merchants
Developers can create Programmable Integration Keys through the Hubtel Developer Portal, then use these credentials to build custom integrations .
The Bulk SMS Platform
Hubtel‘s SMS platform is a sophisticated messaging engine that offers:
-
Personalization: SMS content can be customized for each contact using variable substitution
-
Payment Requests: Messages can include embedded payment links or instructions
-
Send Money via SMS: Contacts can receive funds directly to their mobile money wallet by replying to a message
-
API Connectivity: Programmatic access for high-volume, automated sending
-
Direct carrier routing: MTN, AirtelTigo, and Telecel connectivity ensures delivery quality
The platform publishes detailed pricing bundles, quarterly and semi-annual discounts, and gateway-specific performance metrics (delivery quality index, throughput speed, messages delivered) .
The Marketplace Platform
Hubtel‘s e-commerce marketplace is built on a multi-tenant architecture that allows thousands of merchants to list products, manage orders, and track deliveries through a unified interface. The consumer-facing app serves as the front end, while merchants manage their operations through a dedicated dashboard.
PCI-DSS and Security
Although specific certification documentation is not publicly available in the search results, as an Enhanced Payment Service Provider licensed by the Bank of Ghana, Hubtel is subject to stringent security and data protection requirements for handling payment card information and mobile money transactions.
The ECG PowerApp Controversy: A Case Study in Public Contracting
In 2023, Hubtel became entangled in a public controversy regarding its partnership with the Electricity Company of Ghana (ECG) to develop and manage the ECG PowerApp, a mobile application designed to modernize the utility company‘s payment systems and revenue collection .
The Disputed Invoice
A major point of contention arose when Hubtel submitted an invoice to ECG amounting to GH¢259,819,544.97 (approximately $19 million). ECG‘s management challenged the validity of this claim, arguing that several billed items fell outside the agreed contractual terms .
After negotiations, the final payment was reduced to GH¢20 million—a fraction of the original claim .
The USD Claim Dispute
Further controversy emerged over claims that Hubtel had received **25million∗∗forthedevelopmentofthePowerApp.Thecompanydeniedthis,statingthatthe25 million figure was a cost ceiling approved by ECG‘s board and that actual expenditures amounted to $12 million .
The Revenue-Sharing Disagreement
Hubtel also addressed concerns about its revenue-sharing agreement with ECG. The company clarified that it receives a 0.95% commission from payments processed through its platform, contrary to reports suggesting a 3% fee .
The ACEP Audit Demand
The Africa Center for Energy Policy (ACEP) raised concerns about financial discrepancies and called for an independent audit of all payments made to Hubtel under the contract, citing inconsistencies between figures reported by Hubtel and those found in ECG‘s financial records .
Strategic Implications
The ECG controversy is a double-edged sword. On one hand, it brought Hubtel unwanted public scrutiny and suggested deficiencies in contract negotiation and stakeholder management. On the other hand, the company ultimately demonstrated that it was willing to negotiate, accept a reduced payment, and publicly clarify the facts.
For government agencies considering Hubtel as a technology partner, the ECG case will be a reference point—both for the company‘s technical capabilities and for the contentious contract terms that led to the dispute.
Economic and Industry Impact
Employment and Skills Development
With over 700 employees , Hubtel is a significant employer in Ghana‘s technology sector. The company has also trained generations of software engineers, product managers, and operations specialists through its internal development programs.
SME Digitization
Hubtel‘s most profound economic impact is on small and medium enterprises. Before Hubtel, a corner shop in Sunyani or a restaurant in Techiman had no realistic way to accept mobile money payments, send promotional SMS campaigns, or offer delivery services. Hubtel‘s expansion into mid-tier cities brings these capabilities to businesses that would otherwise remain cash-only and offline.
Government Payment Modernization
Hubtel‘s work with ECG—despite the contractual disputes—demonstrates the role that private fintechs can play in modernizing state-owned enterprises. The PowerApp was intended to reduce revenue leakage, improve customer experience, and digitize a previously manual process.
The Platform Economy
Hubtel represents Ghana‘s most ambitious attempt to build a platform economy. Unlike Uber or Bolt, which are foreign-owned and extract value from local ecosystems, Hubtel is a Ghanaian company building infrastructure that Ghanaian businesses own and use. The company‘s long-term success would demonstrate that African startups can build platform businesses comparable to global leaders.
Competition and Consumer Choice
Hubtel‘s presence in payments, messaging, and e-commerce keeps prices competitive and gives merchants and consumers alternatives to telco-owned mobile money services (MTN MoMo, Telecel Cash). This decentralization of Ghana‘s digital payments landscape is healthy for the ecosystem.
The 20-Year Legacy
As the Minister for Communication noted, Hubtel is not just a tech company; it is “a legacy of innovation built on Ghanaian soil” . The company‘s survival and growth over two decades—through economic crises, regulatory shifts, and competitive threats—provides a template for future Ghanaian startups.
Challenges and Risks
No analysis of Hubtel is complete without acknowledging the headwinds that accompany its ambitious platform strategy.
Risk 1: Geographic Concentration in Ghana
Hubtel‘s operations are concentrated in a single country . While this has allowed deep market penetration, it also means exposure to Ghana‘s macroeconomic cycles, regulatory changes, and political risk. The company‘s ability to thrive is tightly correlated with Ghana‘s GDP growth, inflation rate, and currency stability.
Risk 2: The Flywheel Dependency
Hubtel‘s business model depends on all three engines functioning simultaneously. If payment processing faces regulatory hurdles, if SMS revenue declines due to OTT messaging apps (WhatsApp, Telegram), or if the e-commerce marketplace loses consumer traction, the flywheel could break.
Risk 3: Competition from Pan-African Giants
Flutterwave, Paystack (now part of Stripe), and Chipper Cash have raised hundreds of millions of dollars and have product teams, marketing budgets, and engineering talent that far exceed Hubtel‘s resources. If these competitors decide to prioritize Ghana aggressively, Hubtel could face margin pressure and customer churn.
Risk 4: Telco Disintermediation
MTN Ghana, the country‘s largest mobile money provider, could restrict Hubtel‘s access to its APIs or raise fees for third-party integrations. While regulation prevents outright blocking, telcos have significant power over the ecosystem.
Risk 5: The Logistics Burden
Hubtel‘s e-commerce marketplace relies on delivery logistics—an operationally intensive, low-margin business. Scaling delivery across 11 cities requires managing fleets, drivers, routing algorithms, and customer satisfaction. Any failure in delivery quality reflects poorly on the Hubtel brand.
Risk 6: The ECG Controversy Overhang
The public dispute with ECG remains a cautionary tale for government agencies considering Hubtel as a partner. The controversy could make it more difficult for Hubtel to win future public sector contracts, regardless of the merits of its proposal.
Risk 7: Pan-African Expansion Execution Risk
The appointment of Marjorie Saint-Lot suggests that Hubtel is preparing to expand into Francophone Africa . Cross-border expansion introduces regulatory complexity, language barriers, local competition, and operational costs that Hubtel has not faced in its home market. Execution risk is substantial.
Future Outlook
As of May 2026, Hubtel is executing a three-pillar strategy: deepening its dominance in Ghana, expanding into new markets (likely Francophone Africa), and preparing for a potential listing.
The Immediate Agenda
Hubtel‘s priorities for 2026-2027 are likely to include:
-
Consolidating the 11-city expansion in Sunyani, Techiman, and Tarkwa, building merchant density and consumer awareness
-
Leveraging the Management Advisory Council to refine pan-African strategy and governance structures
-
Exploring a potential listing (the Poole appointment explicitly referenced “future listings”)
-
Launching Francophone Africa operations, led by Saint-Lot‘s expertise
-
Deepening merchant tools for inventory management, analytics, and customer relationship management
The Bull Case (Optimistic)
-
Pan-African expansion succeeds: Hubtel replicates its Ghana model in Côte d‘Ivoire, Senegal, and Cameroon, becoming a truly continental platform.
-
The flywheel accelerates: Growth in payments drives growth in e-commerce, which drives growth in messaging, creating a self-reinforcing cycle that competitors cannot disrupt.
-
IPO unlocks value: A listing on a major exchange (London, Nairobi, or Accra) provides capital for expansion and liquidity for early investors.
-
SME penetration deepens: Hubtel becomes the default operating system for small businesses across Ghana—payments, messaging, delivery, and analytics under one roof.
-
Government contracts stabilize: Despite the ECG controversy, Hubtel wins other public sector contracts, demonstrating its utility for government payment modernization.
The Bear Case (Pessimistic)
-
Pan-African expansion flounders: Cultural differences, regulatory hurdles, and local competition stall Hubtel‘s entry into new markets; the company retreats to Ghana.
-
The flywheel breaks: The e-commerce marketplace loses traction to Jumia or Glovo; messaging revenue declines due to WhatsApp Business adoption; payment processing margins compress.
-
Telcos tighten API access: MTN raises fees or degrades service quality for third-party aggregators; Hubtel‘s payment processing costs rise.
-
IPO market sours: Investor appetite for African fintech IPOs cools; Hubtel delays listing indefinitely; funding constraints limit growth.
-
Talent drain accelerates: Key engineers and product managers are poached by better-funded pan-African competitors.
The Verdict
Hubtel is Ghana‘s most significant home-grown technology company—not because it has raised the most money or achieved the highest valuation, but because it has built the most comprehensive platform. The company understands that commerce is not just about payments; it is about communication, logistics, and customer relationships. All of these elements are woven into Hubtel‘s fabric.
The 20-year journey from SMSGH to Hubtel is a testament to patient, organic, deeply local entrepreneurship . The founders did not raise massive foreign capital in the early years; they built a business that worked, one customer at a time, one feature at a time. The result is a company that is genuinely sustainable—not a venture-funded rocket ship that will burn out if the next round fails to materialize.
The risks are real: geographic concentration, pan-African execution risk, telco dependency, the lingering reputational effects of the ECG controversy. But the trajectory is unmistakable. Hubtel has survived every challenge thrown at it for two decades. The appointment of Simon Poole and Marjorie Saint-Lot suggests that the company is preparing not just to survive, but to dominate.
For businesses, Hubtel offers a complete operating system for commerce. For consumers, it offers a single app for everything from food delivery to bill payments. For the Ghanaian economy, Hubtel offers proof that world-class technology companies can be built, owned, and scaled from Accra.
Hubtel‘s ambition is to become “Africa‘s most useful company” . Two decades in, that ambition is no longer a slogan; it is a work in progress—and it is further along than most observers realize.
Last Updated on May 19, 2026 by Samuel Kwame Boadu
Disclaimer: Some content on Accra Street Journal may be aggregated, summarized, or edited from third-party sources for informational purposes. Images and media are used under fair use or royalty-free licenses. Accra Street Journal is a subsidiary of SamBoad Publishing Hub under SamBoad Business Group Ltd, registered in Ghana since 2014.
For concerns or inquiries, please visit our Privacy Policy or Contact Page.

Samuel Kwame Boadu is a Ghanaian media entrepreneur and storyteller with a passion for amplifying urban voices and uncovering everyday truths. He is the Editor-in-Chief and Founder of Accra Street Journal, a dynamic digital platform dedicated to capturing the pulse of Ghana’s capital—its people, culture, challenges, business, sports and innovations.



