Passengers, cargo, and the search for profit on the world’s least profitable continent
QUICK FACTS BOX
| Category | Details |
|---|---|
| Industry | Commercial aviation / Passenger and cargo air transport |
| Primary Revenue Drivers (Global) | Passenger tickets (60–70%), Cargo, Ancillary services (baggage, seat selection, loyalty programs) |
| African Airline Revenue Share (Est.) | Tickets up to 80%; Cargo avg. 9%; Ancillary well below 15% |
| Total Passenger Revenue (May 2024) | $1.66 billion (up 4% YoY) |
| Total Industry Revenue (2025) | ~$120 billion (est., African carriers share <3%) |
| Net Profit (2026 Forecast) | $200 million (1% margin) |
| Profit per Passenger (2026 Forecast) | 1.30(vs.globalaverage7.90) |
| Global Market Share (Passenger Traffic) | ~2.9% (110 million passengers annually) |
| Global Market Share (Revenue) | ~2% (stable for past decade) |
| Jobs Supported | 8.1 million |
| Contribution to African GDP | 75 billion, including 42 billion linked to tourism. |
| Number of Airlines | ~50 (nearly half operating at a loss) |
| Blocked Funds (March 2026) | $774 million trapped across African countries |
| Key Cost Drivers | Fuel (39% of revenue) , Infrastructure charges (15% above global avg), Maintenance/Insurance/Capital (6–10% higher) |
EXECUTIVE INTRODUCTION
African aviation is a paradox wrapped in high fuel prices and blocked funds. The continent has the world’s fastest-growing passenger traffic — a 20.6% year-on-year increase as of March 2026 . Yet its airlines are the least profitable on earth, earning just 1.30perpassengercomparedtoaglobalaverageof7.90 . They collectively generate about $200 million in annual net profit — less than a single good month for Emirates or Delta .

This is not a story of low demand. It is a story of revenue structures that are underdeveloped, cost structures that are punishing, and a regulatory environment that treats aviation as a source of government revenue rather than an enabler of economic growth .
📢 GET A DETAILED ARTICLES + JOBS
Join ASJ's WhatsApp Channel and never miss a post or opportunity.

This profile examines how African airlines actually generate revenue: the overwhelming reliance on passenger tickets (up to 80% of income, compared to 60–70% for successful global carriers), the underdeveloped cargo and ancillary segments, and the structural reasons why revenue rarely translates into profit . It draws on data from IATA, AFRAA, and industry analysts to map the revenue architecture of a sector that carries 110 million passengers annually, supports 8.1 million jobs, and contributes $75 billion to continental GDP — yet remains marginal in global aviation .
The airline business in Africa is not broken. It is under-engineered. And the engineering required starts with revenue diversification.
THE REVENUE STREAMS OF AN AIRLINE
Every commercial airline generates revenue through three primary channels. The proportions vary by business model (full-service carrier vs. low-cost), geography, and market maturity. In Africa, the proportions are distorted.
Revenue Stream 1: Passenger Tickets (The Core)
Passenger tickets are the foundation of airline revenue. Globally, tickets account for 60–70% of income for successful full-service carriers . For low-cost airlines, ticket revenue can be as low as 40%, with ancillaries making up the difference.
In Africa, the picture is different:
“African airlines, by contrast, remain heavily reliant on ticket sales, which provide up to 80% of their income. Cargo yields an average of just 9% and ancillary services way below 15%.”
This over-reliance on tickets is not a choice. It is a consequence of underdeveloped cargo infrastructure, weak loyalty programmes, and a passenger base that is less accustomed to paying for ancillaries (baggage fees, seat selection, priority boarding) than in more mature markets.
Passenger revenue in numbers:
-
Total passenger revenue (May 2024): 1.66 billion, up from 1.59 billion in April 2023.
-
Annual passenger traffic: 110 million passengers
-
Growth rate (March 2026 YoY): 20.6% — the highest globally
The growth is robust. But the revenue per passenger is not. African airlines earn a net profit of $1.30 per passenger, compared to $3.20 in Asia-Pacific and $28.60 in the Middle East. This gap highlights both high costs (discussed in the cost section) and a limited ability to generate ancillary revenue.
Revenue Stream 2: Cargo (The Underdeveloped Opportunity)
Globally, air cargo can contribute as much as 40% of revenue for some carriers, particularly those with dedicated freighter fleets. In Africa, cargo remains an afterthought.
Current cargo performance:
-
Market share of African airlines per cargo origin: 31.2% (year-to-date)
-
Best-performing region: East Africa at 40.4%
-
Cargo volume growth (YoY): 13.6%
-
Cargo as percentage of airline revenue (Africa): ~9%
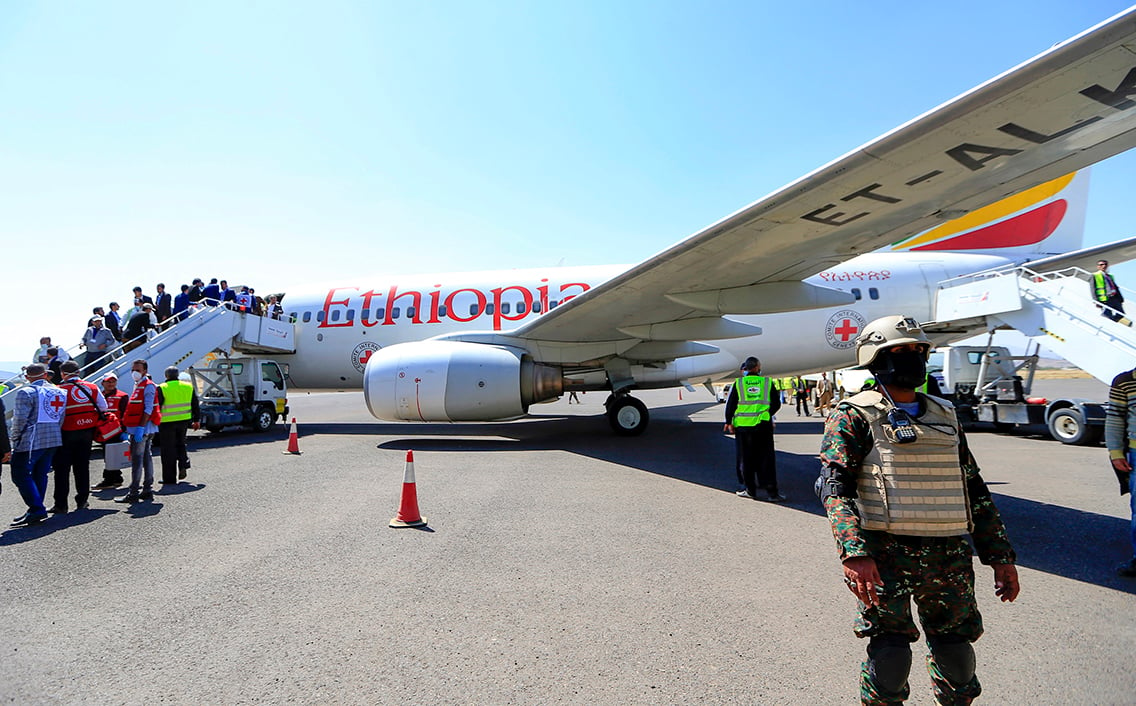
The potential is significant, particularly for perishable goods (flowers, fresh produce, fish) and e-commerce logistics. East Africa’s stronger performance (40.4% market share) reflects the presence of Ethiopian Airlines, which has built a dedicated cargo division with freighters serving regional and international routes. Other regions lag due to inadequate ground handling infrastructure, limited freighter aircraft, and fragmented customs processes.
AFRAA Secretary General Abdérahmane Berthé has noted: “The potential for Air Cargo development on the continent is important and should be supported by adequate infrastructure development and regulatory policy.
Revenue Stream 3: Ancillary Services (The Missing Engine)
Ancillary revenue includes everything beyond tickets and cargo: baggage fees, seat selection, priority boarding, onboard sales, lounge access, and—most significantly—frequent flyer loyalty programmes.
Global benchmarks (2022):
| Airline | Ancillary Revenue (2022) | % of Total Revenue |
|---|---|---|
| Delta | $7.99 billion | ~15-20% |
| United | $7.88 billion | ~15-20% |
| Ryanair | $4.00 billion | ~30-40% (low-cost model) |
| Spirit | $2.61 billion | ~50%+ (ultra-low-cost) |
Source: IdeaWorksCompany Ancillary Revenue Yearbook
The definition matters: IdeaWorksCompany defines ancillary revenue as “revenue beyond the sale of tickets that is generated by direct sales to passengers, or indirectly as a part of the travel experience.” This includes five categories: 1) frequent flyer activities, 2) a la carte features (baggage, seat selection), 3) commission-based products (hotels, car rentals), 4) advertising sold by the airline, and 5) the a la carte components associated with a fare or product bundle .
In Africa, ancillaries are underdeveloped:
“African airlines… remain heavily reliant on ticket sales, which provide up to 80% of their income. Cargo yields an average of just 9% and ancillary services way below 15%.”
The most significant missed opportunity is frequent flyer programmes (FFPs) . Globally, FFPs are among the most profitable parts of an airline’s business. The sale of miles to partners (credit card companies, hotels, retailers) generates high-margin revenue with minimal incremental cost.
SAA Voyager: A case study in FFP transformation
South African Airways (SAA) provides an instructive example of how African carriers can modernise their loyalty programmes. SAA Voyager moved from a mileage-based to a full-fledged revenue-based FFP .
Key changes implemented:
| Feature | Old Model (Mileage-Based) | New Model (Revenue-Based) |
|---|---|---|
| Mile accrual | Distance flown | Spend amount (1 mile per ZAR 1.60) |
| Reward availability | Capacity-controlled (limited seats) | Dynamic pricing, no capacity constraints |
| Economic value of mile | Opaque | Transparent (5% return on spend) |
| Commercial model | Cost centre | Profit centre (commercialised division) |
Suretha Cruse, SAA Executive for Customer Loyalty, explained the rationale: “The move was singularly aimed at becoming more generous and by instilling transparency and fairness in the accumulation of Miles… for the primary brand with our most valuable customers; hence ensuring more efficiency in terms of customer retention.”
The commercialisation of SAA Voyager enabled the airline to “capture opportunities for greater efficiency and optimum service delivery, in addition to ensuring a clear business definition for future commercial sustainability” .
This is a model that other African carriers could adapt. However, loyalty programmes require scale (a large enough passenger base to attract partners) and investment in technology — both of which are challenges for smaller carriers.
Ancillary opportunities specific to Africa:
-
Baggage fees: Many African carriers still include checked baggage in base fares. Unbundling could lower headline fares (attracting more passengers) while generating fee revenue from those who need bags.
-
Seat selection: Premium seats (exit rows, bulkheads, extra legroom) can be monetised.
-
Priority services: Priority check-in, boarding, and baggage handling appeal to business travellers.
-
Onboard sales: Food, beverages, and duty-free merchandise generate revenue on longer flights.
-
Travel insurance and packages: Commission-based products sold at booking.
-
Airport transfer and hotel booking: Commission-based ancillaries for connecting passengers.
The constraint is passenger willingness to pay. In price-sensitive markets, unbundling may alienate customers. But the success of low-cost carriers globally (Ryanair, easyJet, Spirit) demonstrates that ancillaries can work when the base fare is sufficiently low.
THE COST SIDE: WHY REVENUE DOES NOT BECOME PROFIT
Understanding revenue is insufficient without understanding costs. African airlines have the highest unit costs in the world — nearly double the industry average . These costs consume revenue before it can reach the bottom line.
Cost Comparison: Africa vs. Global Average
| Cost Category | Africa vs. Global Average | Key Drivers |
|---|---|---|
| Jet fuel | 17–20% higher | Refining capacity, import logistics, taxes |
| Infrastructure charges (taxes, landing fees) | 15% higher | Government revenue extraction |
| Air navigation charges | 10% higher | Inefficient airspace management |
| Maintenance, insurance, capital | 6–10% higher | Limited local MRO facilities, risk perception |
| Aircraft leasing | 2–3x higher | Credit ratings, perceived risk, limited lessor competition |
| Insurance | 8x higher | Conflict zones, safety perception |
The fuel burden: Fuel accounts for approximately 39% of total revenue for African airlines . When jet fuel prices spike (as they have due to Middle East disruptions), the impact on African carriers is magnified because they start from a higher baseline. A 106.6% year-on-year spike in jet fuel prices has deepened the pressure .
Why fuel is more expensive in Africa:
-
Limited local refining capacity (most fuel imported)
-
Higher taxes and levies compared to other regions
-
Inefficient supply chains (transport to landlocked countries adds cost)
-
Currency depreciation (fuel priced in dollars, revenue in local currency)
Blocked funds: The invisible revenue loss
One of the most bizarre features of African aviation is the phenomenon of “blocked funds” — airline revenues held in local currencies that cannot be repatriated to the airline’s home country .
As of March 2026, Airlines had 774 million stuck in African countries, the largest share of the global total of 900 million. The worst offenders:
| Country | Blocked Funds (USD) |
|---|---|
| Algeria | $258 million |
| Central Africa Zone | Significant |
| Mozambique | Significant |
| Eritrea | Significant |
| Angola | Significant |
In one staggering instance, Nigerian banks withheld as much as 865 million in airline funds, with a single carrier owed 330 million.
The mechanism of blocked funds:
-
Airline sells tickets in local currency (e.g., Nigerian Naira, Algerian Dinar)
-
Airline must pay for fuel, leasing, maintenance in US dollars
-
Local currency cannot be converted and repatriated due to central bank restrictions or dollar shortages
-
Airline’s revenue is trapped as local currency, which may be depreciating
-
Airline must borrow dollars elsewhere to cover expenses, incurring interest costs
Kamil Alawadhi, IATA’s Regional Vice President for Africa and the Middle East, described the impact: “Airlines are forced to pay upfront for fuel, landing fees, and operational costs in dollars. When their revenues are frozen, it leaves them cash-strapped.”
IATA has intervened to recover $1.2 billion of blocked funds, but the total continues to build . This is not a revenue problem. It is a liquidity and profitability problem that is entirely self-inflicted by host governments.
The regulatory fragmentation tax
Only 19% of intra-African routes have direct flights . Passengers travelling between African cities often must connect through Europe or the Middle East — adding time, cost, and emissions while diverting revenue to non-African carriers.
This fragmentation is the result of:
-
Limited liberalisation: Only 19 of 55 African Union member states have fully committed to the Single African Air Transport Market (SAATM)
-
Visa restrictions: Nearly 50% of intra-African routes require visas, suppressing demand
-
Bilateral air service agreements: Many countries restrict fifth-freedom rights (the ability to carry passengers between two foreign countries as part of a route originating in the home country)
-
Protectionism: Governments protect state-owned flag carriers from competition, even when those carriers are inefficient
South African Transport Minister Barbara Creecy acknowledged the problem: “The reality is clear – no African airline can succeed in isolation. An integrated, co-operative and coordinated aviation sector is essential if we are to overcome fragmentation and compete effectively on the global stage.”
THE PASSENGER REVENUE DEEP DIVE
Passenger revenue is the largest line item for African airlines, but the composition of that revenue matters. Not all passengers are equally valuable.
Passenger Segmentation and Yield
| Segment | Characteristics | Yield (Revenue per Passenger-Km) | Share of African Traffic (Est.) |
|---|---|---|---|
| Business | Corporate travellers, government officials, consultants | High (full-fare, flexible tickets) | 10–15% |
| Leisure (International) | Tourists, diaspora visiting family, holiday travellers | Medium (discounted advance purchase) | 25–35% |
| Leisure (Domestic/Regional) | Local travellers, price-sensitive | Low (promotional fares) | 40–50% |
| VFR (Visiting Friends & Relatives) | Diaspora traffic — often high-volume routes (Accra-London, Nairobi-London) | Medium (seasonal peaks) | 10–15% |
The diaspora premium: Routes with large diaspora populations (e.g., Accra to London, Nairobi to London, Lagos to New York) are among the most profitable for African carriers because demand is less price-sensitive and load factors are high. However, these routes face intense competition from Middle Eastern carriers (Emirates, Qatar, Etihad) and European legacy carriers (British Airways, KLM, Air France), which often offer better connections and lower fares.
Seasonality and Revenue Volatility
African airlines experience sharp seasonal swings in passenger revenue:
| Period | Demand | Revenue Impact |
|---|---|---|
| December–January (Christmas, New Year) | Very high (diaspora return) | Peak fares, high load factors |
| July–August (Northern summer holidays) | High (European tourists) | Premium pricing |
| March–April (Easter) | Medium-high | Modest premium |
| May–June (low season) | Low | Discounted fares, thin margins |
| September–November (shoulder) | Medium | Stable |
Airlines that lack financial reserves struggle to survive the low season (May–June). Some reduce frequencies, park aircraft, or suspend routes entirely during this period.
CARGO REVENUE: THE GROWTH OPPORTUNITY
Air cargo is Africa’s most under-monetised aviation segment. The continent produces significant exports that are well-suited to air freight: fresh flowers (Ethiopia, Kenya), fresh produce (vegetables, fruits), fish and seafood, and perishable pharmaceuticals.
Cargo Performance by Region
| Region | Market Share of African Airlines per Cargo Origin | Key Products |
|---|---|---|
| East Africa | 40.4% | Flowers (Ethiopia, Kenya), fresh produce, tea |
| Central & Southern Africa | Below 40% | Mining equipment, perishables |
| West Africa | Below 30% | Cacao (bulk, less suitable for air) |
Source: AFRAA
Why East Africa leads: Ethiopian Airlines has invested heavily in dedicated cargo freighters (Boeing 737-800F, 777F), a cargo terminal at Addis Ababa Bole International Airport, and a network of cargo destinations across Africa, the Middle East, Europe, and Asia. Kenya Airways has also developed cargo capacity, including the recent commissioning of a pyrolysis plant converting plastic waste to diesel for ground operations .
Cargo revenue drivers:
-
Perishables: High-value, time-sensitive goods command premium rates
-
E-commerce: Growing cross-border online shopping (e.g., Jumia, Amazon partnerships)
-
Pharmaceuticals: Vaccine distribution (including COVID-19) and temperature-sensitive medicines
-
Humanitarian cargo: Aid organisations shipping supplies to conflict and disaster zones
The cargo challenge for other carriers: Without dedicated freighters, most African airlines carry cargo only in the belly holds of passenger aircraft. This limits volume and forces them to prioritise baggage over freight when passenger loads are high. Dedicated freighters require capital (US$30–80 million per aircraft) that most carriers cannot access.
AFRAA’s Secretary General has called for “adequate infrastructure development and regulatory policy” to support cargo growth . This includes cold chain facilities at airports, streamlined customs processes, and harmonised phytosanitary standards across African countries.
ANCILLARY REVENUE: THE MISSING BILLIONS
Ancillary revenue is the most significant difference between African airlines and their profitable global peers.
Global Ancillary Revenue Leaders (2022)
| Rank | Airline | Ancillary Revenue (USD) | Primary Drivers |
|---|---|---|---|
| 1 | Delta | $7.99 billion | Frequent flyer (co-branded cards), baggage, seat fees |
| 2 | United | $7.88 billion | Frequent flyer, co-branded cards |
| 3 | American | $7.71 billion | Frequent flyer, co-branded cards |
| 4 | Southwest | $5.94 billion | Frequent flyer (80%+ of ancillary) |
| 5 | Ryanair | $4.00 billion | Baggage, seat selection, priority, onboard sales |
Source: IdeaWorksCompany
Key observation: For full-service carriers, frequent flyer programmes (the sale of miles to partners) are the largest ancillary revenue source, often contributing 80% or more of the total. Ryanair, a low-cost carrier, generates ancillary revenue primarily from a la carte features (baggage, seat selection) rather than loyalty programmes.
The Frequent Flyer Programme Opportunity
Globally, FFPs are among the most profitable divisions of airlines. The model is straightforward:
-
Airline creates a loyalty currency (“miles” or “points”)
-
Airline sells miles to partners: credit card issuers, hotels, car rental companies, retailers
-
Partners use miles as rewards for their customers
-
Airline earns high-margin revenue (miles cost little to issue; they represent future service obligations)
-
Some miles expire unused (“breakage”) — pure profit
Why African FFPs lag:
-
Small passenger bases (limited partner interest)
-
Low credit card penetration (co-branded cards less viable)
-
Limited partner ecosystems (fewer hotels, retailers participating)
-
Technology investment required (modern loyalty platforms are expensive)
The South African exception: SAA Voyager has been commercialised as a standalone profit centre . The programme generates revenue from partner sales and reduces the airline’s dependence on ticket revenue.
For other African carriers, building a profitable FFP will require:
-
Regional partnerships (pooling loyalty programmes across multiple airlines)
-
Mobile-first technology (leveraging Africa’s high mobile penetration)
-
Partnerships with mobile money platforms (converting airtime or mobile money into miles)
A La Carte Ancillaries: Unbundling the Ticket
Low-cost carriers globally have demonstrated that unbundling works: offer a low base fare, then charge for everything else (baggage, seat selection, priority boarding, food, drinks, blankets). Passengers who value low prices choose the base fare; passengers who value convenience pay for ancillaries.
African carriers have been slow to unbundle. Most still include checked baggage in the base fare. This is partly cultural (passengers expect baggage to be included) and partly competitive (carriers fear losing passengers to rivals).
The counterargument: Unbundling allows carriers to lower headline fares, attracting price-sensitive passengers who previously could not afford to fly. The ancillary fees from those who do need bags can exceed the revenue lost from including bags in all fares.
Ryanair’s model is instructive: base fares as low as €10, with ancillary fees for everything else. The result: ancillary revenue exceeding ticket revenue on many flights.
STRUCTURAL SOLUTIONS: FROM REVENUE TO PROFIT
The revenue problem for African airlines is not primarily about increasing passenger numbers — growth is already strong. It is about converting that growth into profit. The solutions require action from both airlines and governments.
Airline-Level Actions
| Action | Expected Impact | Implementation Challenge |
|---|---|---|
| Unbundling tickets (baggage fees, seat selection) | Increase ancillary revenue to 15–20% of total | Passenger resistance, competitive response |
| Commercialising loyalty programmes | High-margin revenue from partner sales | Requires scale, technology investment |
| Investing in cargo (dedicated freighters, cold chain) | Diversify revenue; cargo margins often exceed passenger | Capital intensive (US$30-80m per freighter) |
| Fleet modernisation (fuel-efficient aircraft) | Reduce fuel costs (40% of revenue) | Capital intensive; requires financing |
| Joining global alliances (Star Alliance, SkyTeam, oneworld) | Access to connecting traffic, improved load factors | Rigorous qualification standards |
| Route optimisation (cut unprofitable routes, add high-demand) | Improve passenger yield | Political pressure (national carrier status) |
The subsidy question: Some African airlines receive direct or indirect government subsidies. Ethiopian Airlines is a notable example: it receives government guarantees for aircraft acquisitions, direct subsidies budgeted annually, and favourable access to financing . This has enabled Ethiopian to become Africa’s strongest carrier.
However, subsidies are controversial. Critics argue they distort competition and protect inefficient carriers. Proponents argue that aviation is a strategic industry requiring government support, particularly in capital-constrained markets.
Government-Level Actions
| Action | Expected Impact | Current Status |
|---|---|---|
| Implement SAATM (Single African Air Transport Market) | Increase intra-African connectivity, reduce fragmentation | Only 19 of 55 states fully committed |
| Reduce taxes and infrastructure charges | Lower operating costs by 15%+ | Current charges 15% above global avg |
| Resolve blocked funds | Improve airline liquidity, reduce borrowing costs | $774m trapped as of March 2026 |
| Liberalise visas (intra-African travel) | Increase passenger demand, higher load factors | 50% of routes require visas |
| Implement Free Route Airspace (FRA) | Reduce flight distances 3-5%, save fuel | WACAF implemented; ESAF planned |
| Invest in airport infrastructure | Improve cargo handling, passenger experience, efficiency | Varies widely by country |
The Free Route Airspace success story:
Since October 2025, West and Central Africa (WACAF) has implemented Free Route Airspace (FRA), allowing airlines to file “User Preferred Routes” based on real-time weather and traffic .
Results for participating airlines (Ethiopian, Kenya Airways, EgyptAir, Royal Air Maroc, RwandAir, ASKY):
-
Annual flight time saved: 1,393 hours
-
Fuel saved: 5,000 tonnes
-
CO2 emissions reduced: 16,000 tonnes
-
Direct fuel cost savings: ~$15 million
The success has prompted plans to extend FRA to Eastern and Southern Africa (ESAF) in 2026, with a continent-wide FRA targeted for 2027 . This is precisely the kind of government-led reform that improves airline profitability without requiring airline investment.
The SAATM imperative:
The Single African Air Transport Market (SAATM) is the African Union’s flagship aviation initiative, designed to liberalise intra-African air services by granting fifth-freedom rights and removing capacity restrictions. However, implementation has been slow.
South Africa’s renewed push for SAATM implementation, announced at the 14th Aviation Stakeholders Convention in Johannesburg (May 2026), includes:
-
Enabling movement of 42 million passengers through South African airports by 2029
-
Investing in aviation infrastructure to support regional connectivity
-
Addressing red tape in issuing air services licences and foreign operator permits
The convention’s theme — “Resilient African Aviation: Partnerships – Empowerment – Profitability” — explicitly links collaboration to financial performance .
FUTURE OUTLOOK
Short-to-Medium Term (1–5 years)
-
Profitability remains challenged. IATA forecasts African airlines will generate just $200 million net profit in 2026, a 1% margin . This will improve only if costs are addressed.
-
SAATM implementation will continue slowly. Only 19 states have fully committed; full liberalisation remains a decade away.
-
Free Route Airspace expands. Following WACAF’s success, ESAF implementation in 2026 will reduce fuel costs for carriers operating in Southern and Eastern Africa .
-
Cargo growth accelerates. The 13.6% YoY growth in cargo volume reflects increasing demand for air freight, particularly for perishables and e-commerce .
-
Blocked funds remain a crisis. Without resolution, some foreign carriers may reduce service to affected countries.
Long-Term (5–15 years)
Scenario 1: Liberalisation and Integration (Probability: 40%)
SAATM implementation accelerates. Intra-African connectivity improves, with direct flights replacing connections through Europe and the Middle East. African carriers capture a larger share of intra-continental traffic. Ancillary revenue matures (loyalty programmes, unbundling). Industry profitability improves to $5–10 per passenger.
Scenario 2: Status Quo Extended (Probability: 45%)
Fragmentation persists. Only 2–3 well-managed carriers (Ethiopian, Kenya Airways, perhaps a South African survivor) remain profitable. Most state-owned carriers continue to operate at a loss, sustained by government subsidies. Foreign carriers (Middle Eastern, European) dominate intra-African routes.
Scenario 3: Consolidation (Probability: 15%)
Loss-making carriers exit or merge. The number of African airlines shrinks by 30–50%. Surviving carriers achieve scale, reduce unit costs, and improve profitability. A pan-African airline group emerges, integrating operations across multiple countries.
Strategic Risks to Monitor
| Risk | Probability | Impact | Mitigation |
|---|---|---|---|
| Prolonged high fuel prices | High (Middle East tensions) | Severe (fuel 39% of revenue) | Fleet modernisation; hedging |
| Blocked funds crisis escalation | Medium | Severe (liquidity crisis) | IATA advocacy; currency diversification |
| Geopolitical conflicts affecting airspace | Medium (Sahel, Horn of Africa) | High (route closures, insurance spikes) | Route diversification; risk assessment |
| EU SAF mandate (no African concessions) | High (2025 onward) | Medium (higher costs for Europe flights) | Advocate for concessions; pass costs to passengers |
| Slow SAATM implementation | High (political will lacking) | Medium (fragmentation persists) | Bilateral agreements bypassing SAATM |
ASJ CONCLUSION
African airlines are caught in a trap. Passenger demand is growing faster than anywhere else in the world — 20.6% year-on-year as of March 2026 . But revenue does not translate into profit because costs are punishing and revenue structures are underdeveloped.
The African carrier earns 80% of its revenue from passenger tickets, compared to 60–70% for successful global airlines . It leaves cargo revenue (9%) and ancillary revenue (well below 15%) on the table — the very segments that generate the highest margins globally. It pays 17–20% more for fuel, 15% more in infrastructure charges, and 2–3x more for aircraft leasing . It cannot repatriate $774 million in revenue trapped as blocked funds across the continent .
And yet, the potential is immense. The continent supports 8.1 million jobs and contributes $75 billion to GDP through aviation . Free Route Airspace implementation has already demonstrated that relatively simple reforms can save millions in fuel costs . SAATM, if fully implemented, could transform intra-African connectivity, raising the share of direct routes from 19% to something approaching normal .
The solution is not more passengers. Africa already has those. The solution is revenue diversification (cargo, ancillaries, loyalty programmes), cost reduction (fuel, infrastructure, fragmentation), and government cooperation (blocked funds, SAATM, visa liberalisation).
The airline that cracks this code will not just be Africa’s strongest carrier. It will be the template for the continent’s aviation future. Until then, African airlines will continue to fly full planes — and earn almost nothing from them.
Source: Accra Street Journal
Last Updated on May 25, 2026 by Samuel Kwame Boadu
Disclaimer: Some content on Accra Street Journal may be aggregated, summarized, or edited from third-party sources for informational purposes. Images and media are used under fair use or royalty-free licenses. Accra Street Journal is a subsidiary of SamBoad Publishing Hub under SamBoad Business Group Ltd, registered in Ghana since 2014.
For concerns or inquiries, please visit our Privacy Policy or Contact Page.

Samuel Kwame Boadu is a Ghanaian media entrepreneur and storyteller with a passion for amplifying urban voices and uncovering everyday truths. He is the Editor-in-Chief and Founder of Accra Street Journal, a dynamic digital platform dedicated to capturing the pulse of Ghana’s capital—its people, culture, challenges, business, sports and innovations.