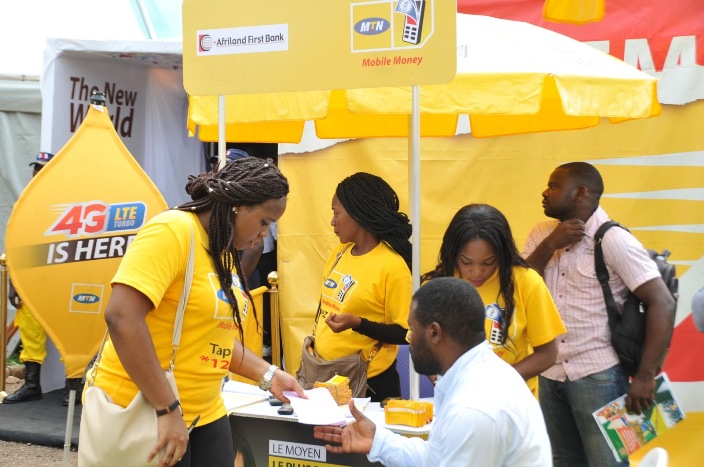
Telecommunications giant MTN Ghana has announced new charges on transfers from Mobile Money (MoMo) wallets to bank accounts, set to take effect from June 1, 2026. In a text message sent to customers, MTN said transfers from MoMo wallets to bank accounts will now attract a fee of 0.75% per transaction, capped at GHS 5. According to the company, this move “will help us continue to serve you better.” The announcement is expected to trigger public debate among mobile money users, many of whom rely on MoMo-to-bank transfers for business transactions, salary movements, and everyday banking activities.
The new charge means customers transferring money from their MoMo wallets into bank accounts will pay a percentage-based fee, although the total deduction on a single transaction will not exceed GHS 5. For a transfer of GHS 100, the fee would be GHS 0.75; for GHS 500, GHS 3.75; for GHS 1,000, GHS 5 (the cap); and for any amount above GHS 667, the GHS 5 cap applies. The fee structure is designed to protect small transactions while generating revenue from larger transfers.

Key Developments: Fee Structure, Customer Communication, and Competitive Positioning
The new fee applies only to transfers from MoMo wallets to bank accounts. Transfers between MoMo wallets (MTN to MTN, MTN to other networks) remain subject to the existing fee structure. Cash-in and cash-out transactions at agents also retain their existing charges. The specificity of the new fee—targeting the MoMo-to-bank corridor—suggests that MTN is seeking to capture value from a high-volume, high-value transaction type that previously may have been free or minimally charged.
📢 GET A DETAILED ARTICLES + JOBS
Join ASJ's WhatsApp Channel and never miss a post or opportunity.

The 0.75% fee with a GHS 5 cap is a hybrid pricing model: percentage-based for smaller transactions, capped for larger ones. This structure is common in digital payments, as it ensures that the fee scales with transaction value up to a point, after which it becomes a fixed charge. For a GHS 1,000 transfer, the fee of GHS 5 represents 0.5% of the transaction value—lower than the nominal 0.75% rate. For a GHS 10,000 transfer, the same GHS 5 fee represents only 0.05%. The cap protects high-value users from disproportionate charges.
MTN’s customer communication was notably brief. The text message did not explain the rationale beyond “help us continue to serve you better,” nor did it provide details on how the fee compares to industry standards or whether other telcos (Telecel, AT) would follow suit. This lack of transparency may fuel customer frustration, as users may perceive the fee as arbitrary or opportunistic.
The timing of the announcement—just days before the June 1 effective date—provides little lead time for customers to adjust their behavior. Businesses that rely on MoMo-to-bank transfers for payroll, supplier payments, or cash management may need to revise their processes or absorb the new costs.
The competitive implications are significant. MTN is the dominant player in Ghana’s mobile money market, with the largest subscriber base and agent network. If MTN raises fees on a popular service, competitors such as Telecel Cash and AT Money may gain an advantage by offering lower fees or promotional rates. However, network effects—the fact that most users and merchants are on MTN—mean that customers may tolerate the fee rather than switch to a smaller, less convenient network.
The Bank of Ghana, as the regulator of mobile money, will likely monitor the situation. The central bank has previously intervened when fee changes were deemed anti-competitive or harmful to financial inclusion. However, MTN’s fee is percentage-based and capped, which is less regressive than a flat fee that would disproportionately burden small transactions. The Bank of Ghana may allow the fee to stand, provided it is clearly disclosed and not misleading.
Analysis & Implications: Revenue Generation, Cost Recovery, and Financial Inclusion
Mobile money operators face significant costs: agent commissions, transaction switching fees, fraud prevention, customer support, and technology infrastructure. For years, operators have subsidized certain transaction types—including MoMo-to-bank transfers—as loss leaders to grow the user base and encourage digital payment adoption. As the market matures, operators are seeking to monetize high-value services.
The MoMo-to-bank transfer corridor is particularly costly. When a user transfers funds from a MoMo wallet to a bank account, the mobile money operator must settle the transfer with the recipient bank, often through a payment gateway or switching platform (such as GhIPPS or a third-party processor). Each leg of the transaction incurs a cost. The 0.75% fee (capped at GHS 5) is likely intended to recover these costs and generate a modest profit margin.
The fee structure is designed to be progressive. For a small transfer of GHS 10 (a common amount for airtime purchase or small remittance), the fee would be GHS 0.075—less than 10 pesewas. For a large transfer of GHS 10,000 (a business payment or salary bulk transfer), the fee is GHS 5—a flat charge regardless of the amount. The cap protects high-value users, while the percentage ensures that small transfers are not overcharged relative to their value.
The impact on financial inclusion is a concern. Mobile money has been a powerful tool for financial inclusion in Ghana, bringing millions of unbanked and underbanked citizens into the formal financial system. MoMo-to-bank transfers allow users without a bank account to send money to banked recipients (e.g., paying school fees, receiving salaries). A new fee on this service could discourage usage, particularly among low-income users who are most sensitive to transaction costs.
However, the fee is low: GHS 5 is approximately $0.44 at current exchange rates. For a user making one transfer per month, the annual cost is GHS 60—not trivial but also not prohibitive. The more significant impact may be psychological: users may perceive the fee as an erosion of the value proposition of mobile money, which has historically been marketed as a low-cost alternative to traditional banking.
MTN’s justification—”to help us continue to serve you better”—is vague. Customers would likely appreciate a more detailed explanation, including the costs MTN incurs to provide the service, how the fee compares to industry standards (e.g., bank-to-MoMo transfers, which may also incur fees), and what improvements customers can expect in return. Without such transparency, the fee may be seen as a pure profit grab.
The Accra Street Journal notes that mobile money operators are under pressure to generate returns on investment. The era of subsidized growth is ending; operators must now demonstrate profitability. MTN Ghana, as a subsidiary of MTN Group, is expected to contribute to the parent company’s bottom line. Fee adjustments are inevitable. The question is whether they are implemented transparently and equitably.
What This Means for Consumers, Businesses, and Fintechs
For consumers who use MoMo-to-bank transfers occasionally, the new fee will be a minor inconvenience. A user who transfers GHS 200 once per month will pay GHS 1.50 per month (GHS 18 per year). For users who make frequent transfers—such as small-scale traders who move funds between their MoMo wallet and bank account daily—the costs will add up. A trader making 20 transfers per month of GHS 100 each would pay GHS 0.75 per transfer (GHS 15 per month, GHS 180 per year). The cumulative impact could be significant.
For businesses that use MoMo-to-bank transfers for payroll, supplier payments, or cash management, the fee represents an additional operational cost. A small business that pays 50 employees via MoMo-to-bank transfers each month, with an average salary of GHS 1,500, would pay GHS 5 per employee (the cap), totaling GHS 250 per month (GHS 3,000 per year). This is a non-trivial expense. Businesses may seek alternatives, such as paying salaries via MoMo-to-MoMo transfers (if employees have MoMo wallets) or using bank-to-bank transfers (which may have different fee structures).
For fintechs and payment service providers that rely on mobile money interoperability, the fee may create arbitrage opportunities. A fintech could offer a service that aggregates MoMo-to-bank transfers, bundling them into larger transactions to reduce the per-transfer cost. Alternatively, fintechs could encourage users to switch to alternative payment methods, such as direct bank transfers or card payments, if those methods are cheaper.
For MTN, the fee is a revenue opportunity but also a competitive risk. If customers perceive the fee as excessive or unjustified, they may reduce their usage of MoMo-to-bank transfers or switch to competitors. Telecel Cash and AT Money could gain market share by offering lower fees or promotional rates. MTN’s dominant market position provides a buffer, but not an impenetrable one.
The Bank of Ghana’s role will be critical. The central bank has expressed support for affordable digital payments as a tool for financial inclusion. If the new fee is seen as undermining that goal, the Bank of Ghana may pressure MTN to reduce or eliminate it. However, the central bank also recognizes that mobile money operators must be commercially viable. The fee, at 0.75% capped at GHS 5, is not obviously predatory. It may be allowed to stand.
Wider Context: Mobile Money Pricing in Ghana and Across Africa
Ghana’s mobile money market is one of the most competitive and innovative in Africa. MTN MoMo, Telecel Cash, and AT Money compete for subscribers, agents, and transaction volume. Fees have generally been low, reflecting competition and regulatory oversight. However, operators are now seeking to increase revenue from transaction fees as growth in user numbers slows and the market matures.
Across Africa, mobile money pricing varies. In Kenya, M-Pesa charges fees for most transaction types, including person-to-person transfers, cash-in/cash-out, and bank transfers. The fees are typically percentage-based, with caps. In Tanzania, fees are generally lower due to intense competition. In Nigeria, mobile money adoption has been slower, but fees are regulated by the central bank.
The trend toward fee rationalization—increasing fees on services that were previously subsidized—is evident across the continent. As mobile money operators move from growth phase to profitability phase, they are adjusting pricing models. The challenge is to do so without alienating customers or undermining financial inclusion.
Ghana’s interoperability framework—which allows users to transfer funds between different mobile money networks and between mobile money and banks—has been a success. The Bank of Ghana’s leadership in promoting interoperability has been praised. However, interoperability also imposes costs on operators, as they must settle transactions with other networks and banks. The new MoMo-to-bank fee may be, in part, a response to those costs.
The Accra Street Journal notes that the fee announcement comes at a time of broader economic pressures. Inflation, while moderating, remains a concern. The cedi has depreciated. Fuel prices are high. Consumers are already facing higher costs for basic goods and services. A new fee on mobile money transfers, even a small one, may be poorly received.
Outlook / What Happens Next
The new fee takes effect on June 1, 2026. Customers will see the charge applied to their MoMo-to-bank transfers from that date. MTN will likely monitor transaction volumes to assess the impact on customer behavior. If volumes drop significantly, MTN may adjust the fee or introduce promotions to encourage usage.
Competitors will watch closely. Telecel Cash and AT Money may maintain their current fee structures (or offer lower fees) as a competitive differentiator. If they gain market share, MTN may be forced to reconsider. If they also raise fees, the industry will have coordinated on a new pricing norm.
The Bank of Ghana will review the fee’s impact on financial inclusion. If the central bank determines that the fee is harming low-income users or reducing financial inclusion, it may intervene. However, the fee is low and capped, so intervention is unlikely in the short term.
For the Accra Street Journal’s readers, the advice is to plan. If you use MoMo-to-bank transfers frequently, consider whether you can reduce usage by keeping more funds in your MoMo wallet or using alternative transfer methods. If you are a business, review your payment processes and consider whether you can absorb the fee or pass it on to customers. The fee is not large, but it is real. In a challenging economic environment, every cedi counts.
Source: Accra Street Journal
Last Updated on May 26, 2026 by Samuel Kwame Boadu
Disclaimer: Some content on Accra Street Journal may be aggregated, summarized, or edited from third-party sources for informational purposes. Images and media are used under fair use or royalty-free licenses. Accra Street Journal is a subsidiary of SamBoad Publishing Hub under SamBoad Business Group Ltd, registered in Ghana since 2014.
For concerns or inquiries, please visit our Privacy Policy or Contact Page.

Samuel Kwame Boadu is a Ghanaian media entrepreneur and storyteller with a passion for amplifying urban voices and uncovering everyday truths. He is the Editor-in-Chief and Founder of Accra Street Journal, a dynamic digital platform dedicated to capturing the pulse of Ghana’s capital—its people, culture, challenges, business, sports and innovations.