ACCRA – Ghana’s mobile money industry continues to swell, but new data from the central bank reveals a widening gulf between market access and actual economic activity.
A record 82 million registered accounts and nearly GH¢450 billion in transactions paint a picture of a sector on fire. But a closer look at the central bank’s latest data reveals a less glamorous reality: a growing army of inactive agents and a widening gap between sign-ups and real-world usage.
On paper, Ghana’s mobile money story has never looked healthier. The Bank of Ghana (BoG) reported Tuesday that registered mobile money accounts have surged to 82 million—a figure that far exceeds the country’s adult population—while the value of transactions processed in February alone approached a staggering GH¢447.37 billion.
- ACCRA – Ghana’s mobile money industry continues to swell, but new data from the central bank reveals a widening gulf between market access and actual economic activity.
- Transaction volumes hit 899 million for the month, underscoring a structural shift in how Ghana moves money.
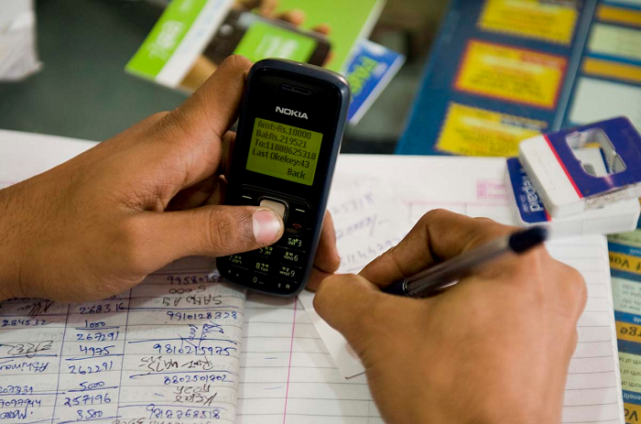
- The BoG data highlights a stark disconnect: while the number of registered agents has climbed to 976,000, only 515,000 are actively processing transactions.
The headline numbers suggest a digital payments juggernaut, powering everything from street hawker transactions to corporate remittances. Transaction volumes hit 899 million for the month, underscoring a structural shift in how Ghana moves money.
Yet, for all the top-line growth, the ground-level infrastructure that built this revolution is showing signs of strain. The BoG data highlights a stark disconnect: while the number of registered agents has climbed to 976,000, only 515,000 are actively processing transactions.
The ‘Inactive Army’
This chasm—where nearly half of the agent network lies dormant—is the sector’s dirty secret. It points to a market that may have reached saturation point, particularly in urban centers where a mobile money kiosk sits on every corner, or to a deeper crisis of profitability for the average vendor.
“The agent is the heartbeat of mobile money. If the heart is skipping beats, the patient has a problem,” said Nana Ama Serwaa, a financial inclusion analyst at the Tema-based policy think tank, The Soho Street Initiative. “We are seeing a two-tiered system where big, well-capitalized agents are thriving, but the small operator who bought one float is being squeezed out by thin margins and high operating costs.”
The divergence isn’t limited to agents. The data shows active user accounts at 27 million—a healthy number, but a fraction of the 82 million registered. This suggests a significant portion of accounts are dormant or used only sporadically.
Analysis & Insights from Accra Street Journal
This isn’t a story of decline, but of maturation—and its painful side effects. The explosion in transaction value (GH¢447.37 billion) versus transaction volume (899 million) is a key indicator. It suggests that while the number of individual transactions is growing steadily, the real financial heft is coming from larger, high-value transfers. This is likely driven by businesses moving away from traditional banking channels for salary payments and supplier settlements, and by wealthier Ghanaians using MOMO for high-end remittances.
This shift benefits the telecoms (Telcos) and their primary aggregators, but it doesn’t necessarily trickle down to the agent who relies on a high volume of small cash-in/cash-out fees to survive. The agent is being disintermediated from the most profitable part of the growth. If the trend continues, we could see a consolidation of the agent network, pushing thousands out of the business they were recruited to build. For financial inclusion to be sustainable, the agent must remain profitable.
Fact Check History
-
Claim: “Mobile Money Accounts Hit 82 Million.
-
Verdict: True. This figure, as reported, represents total registered accounts since the service’s inception. It is not a snapshot of unique, currently active users. The Accra Street Journal confirms this distinction is critical, as one individual can hold multiple accounts across different networks, inflating the headline number.
-
Claim: “Transaction Value Nears GH¢450 Billion.”
-
Verdict: True. The data from the Bank of Ghana for February 2026 puts the total value at GH¢447.37 billion. This is a nominal record high, though it must be viewed in the context of the Ghanaian Cedi’s depreciation over time, which can inflate local currency transaction values.
-
Claim: “Active agents stood at 515,000, highlighting a persistent disparity.”
Source: Accra Street Journal