







An Accra Street Journal Real Estate Intelligence Brief
Executive Introduction
The conventional wisdom about home construction in Ghana is wrong. You do not need a bank loan. You do not need a lump sum of GHS 300,000 sitting in your account before you pour the first bag of cement. What you need is a plot of land, an architect who will design within your means, a contractor who will break your project into manageable stages, and the discipline to save consistently.

Across Ghana, thousands of middle and lower-income earners are completing homes without ever stepping into a bank for a mortgage. They are building in phases—foundation this year, walls next year, roofing the year after. The approach is not slower than waiting to save the full amount. It is faster, because you start immediately.
📢 GET A DETAILED ARTICLES + JOBS
Join ASJ's WhatsApp Channel and never miss a post or opportunity.

Philips Construction, a Ghanaian architectural consultant, has demonstrated that individuals earning between GHS 2,000 and GHS 2,500 monthly can achieve homeownership by breaking the project into stages and working toward one phase at a time . Nana Okuoba Akomea, an inventor from the Okuoba Kingdom, has shown that even those earning GHS 1,000 per month can start—by saving GHS 200–300 monthly toward land, then buying materials incrementally .
This ASJ report examines the phased building approach that is enabling Ghanaians to complete homes without bank loans: the psychology of breaking down costs, the practical phasing strategies, the financing alternatives (including developer payment plans and supplier credit), the critical role of accurate cost estimation (the “completeness gap”), and the concrete steps to get started.

Part 1: The Psychology of Phased Building – Why Seeing the Total Is Discouraging
The single biggest obstacle to homeownership is not the total cost. It is the psychological weight of seeing that total cost all at once.
Philips Construction explains the problem directly: “When people see the total amounts they need to save and can work toward one stage at a time, it helps them continue saving until they can complete their house.” Conversely, when prospective builders see the total cost upfront, “they get discouraged and may never build anything” .
The phasing solution: By breaking the project down into stages, it becomes much easier and less overwhelming for them to manage . A builder does not need GHS 300,000 today. They need GHS 30,000 for the foundation this year. GHS 40,000 for blockwork next year. GHS 50,000 for roofing the year after.
This is not magical thinking—it is the difference between being overwhelmed by a mountain and climbing it one step at a time.
A Proven Model on a Modest Salary
Philips Construction has created a practical target for people earning around GHS 2,000 to GHS 2,500 who would like to have their own place to live. The model is straightforward :
| Step | Action |
|---|---|
| 1 | Acquire half a plot of land (or start saving for it) |
| 2 | Assess your financial position and determine monthly savings capacity |
| 3 | Engage an architect to design within your budget |
| 4 | Consult a contractor to break costs into manageable stages |
| 5 | Develop a long-range saving plan targeting one stage at a time |
The inventor’s perspective: Nana Okuoba Akomea argues that building a house is not as hard as many people think. If someone claims this is difficult, it simply means they do not know enough about the process.” He advises starting by saving GHS 200 or GHS 300 each month, gradually working toward buying a small plot (approximately GHS 15,000) .
Part 2: Why Traditional Mortgages Are Not the Answer
The academic literature confirms what many Ghanaians already know: low-income and even middle-income households are priced out of formal mortgage markets. A study published in Housing Policy Debate found that “high mortgage repayment-to-income ratios and unavailability of adequate and secured collateral are major setbacks for low-income households in accessing housing finance” .
The result: Low-income households rely on the incremental building process—the phased approach described throughout this report. While the academic study notes that this approach “is unsustainable and inefficient because it takes longer periods to complete, and such houses lack basic sanitary amenities,” these criticisms reflect conditions where builders lack proper planning or professional guidance . With an architect, a detailed Bill of Quantities, and proper phasing, these inefficiencies can be minimised.
The key insight: The same study acknowledges that for those priced out of formal mortgages, incremental building is the only available path. This report focuses on making that path more efficient, transparent, and successful.

Part 3: Developer Payment Plans – A No-Interest Alternative
For those who prefer to buy an already-built home or an off-plan unit, developer payment plans offer a no-interest alternative to bank mortgages .
How Developer Payment Plans Work
When you buy off-plan, the developer lets you spread the purchase price over a fixed schedule without involving a bank. The process typically involves :
-
A reservation fee
-
Signing a sale agreement
-
Paying around 30 per cent within the first 20 days
-
The remaining 70 per cent in monthly or quarterly instalments over the construction period
Key advantages: No credit score check. No bank application. The total price is agreed on day one, and crucially, there is zero interest added .
Example from AGORA Apartments: A studio unit starting at $100,000 costs exactly $100,000 across the payment schedule—not a dollar more. The trade-off is time: you have months, not decades, to finish payment .
The Hybrid Strategy: Developer Plan Then Bank Refinance
A third path exists that combines the best of both approaches. Use a developer plan through construction, then refinance the balance into a bank mortgage after completion. You get the price lock-in of off-plan buying with the long repayment spread of a bank product. Few buyers know this option. It is often the smartest one .
Developer Payment Plans vs Bank Mortgages
| Feature | Developer Payment Plan | Bank Mortgage |
|---|---|---|
| Interest | Zero | Significant (typically 20-30% annually) |
| Credit check | Not required | Required |
| Down payment | ~30% upfront | 10-20% typically |
| Repayment period | Months (construction period) | Decades (10-20 years) |
| Total cost | Purchase price only | Purchase price + interest |
| Monthly payment | Higher (shorter period) | Lower (longer period) |
The “Roof Now, Pay Later” Innovation
A specific example of supplier-driven phased financing is the “Roof Now, Pay Later” initiative launched by Dophil Roofing System in conjunction with Societe Generale. The programme provides affordable roofing to salaried workers whose building projects have stalled due to financial constraints .
Key features :
-
Targets public-sector workers and Societe Generale customers
-
Spreads payments over 1 to 3 years
-
Allows workers to complete stalled roofing projects without immediate financial constraints
Dr Daniel McKorley, CEO of McDan Group of Companies, noted at the launch that “the rising cost of building materials has made it difficult for salary workers to complete their houses, so this initiative would help them complete their houses while escaping issues of inflation” .
Part 4: The “Completeness Gap” – Why You Cannot Trust Cheap Quotes
The most important concept for any phased builder to understand is the “completeness gap.” A peer-reviewed academic study from the University of Cape Coast and Kwame Nkrumah University of Science and Technology validated this phenomenon, finding a “systematic discrepancy between informal contractor quotes and actual costs” .
What the Research Found
The study tested three case study homes (75, 120, and 200 square metres) benchmarked against February 2026 market prices in Greater Accra. The results were striking :
| Home Size | True Cost (GHP Estimate) | Informal Quotes | Gap |
|---|---|---|---|
| 75 m² | GHS 519,000 | Significantly lower | 29–98% higher |
| 200 m² | GHS 1,398,000 | Significantly lower | 29–98% higher |
Why the gap exists: Informal estimates use flat per-square-metre pricing that omits essential structural and finishing components, including :

-
Structural steel (Y16 rebar)
-
Plastering (rendering)
-
Floor screeding
-
Full electrical services
-
Full plumbing services
The critical warning: “Per-square-metre rates rarely cover the requirements for a fully completed, code-compliant building” . If a contractor quotes you a flat rate per square metre that seems too good to be true, it almost certainly is.
The GhanaHousePlanner Solution
To address this gap, the research team developed the GhanaHousePlanner (GHP) platform, a parametric, geometry-aware residential construction cost estimation model. The platform features :
-
Seven calculation modules: foundation, blockwork, cement, structural steel, roofing, plumbing, and electrical
-
Region-aware material pricing updated monthly
-
Itemised Bills of Quantities (BoQ)
-
Free for basic use (project management and LLM-based planning are paid features)
How to use it: Visit ghanahouseplanner.com to generate detailed cost breakdowns for your specific house design, updated with current local material prices .
Part 5: Step-by-Step Phased Building Strategy
Phase 0: Land Acquisition and Planning
Philips Construction’s advice: “The first step depends on whether you have land already. If you do, that already makes things easier. If you do not own any land, the first step would be saving for a piece of land” .
How much land? “Half a plot of land would be a good start because that will provide the foundation of your building project, as well as serve as a good target for your savings” .
Land cost estimate: Nana Okuoba Akomea estimates a small plot at approximately GHS 15,000 . This can be saved for incrementally—GHS 200–300 per month.
Phase 1: Architectural Design
After you have acquired land (or while you are saving for it), the next step is to engage an architect. Philips Construction advises: “You should sit down and discuss your plan with your architect. Afterwards, allow them to design your home according to what you can afford financially. In this way, your house will be designed within your financial capabilities and not exceed them” .
Estimated cost: GHS 10,000 – GHS 30,000 (depending on architect and design complexity)
Phase 2: Foundation
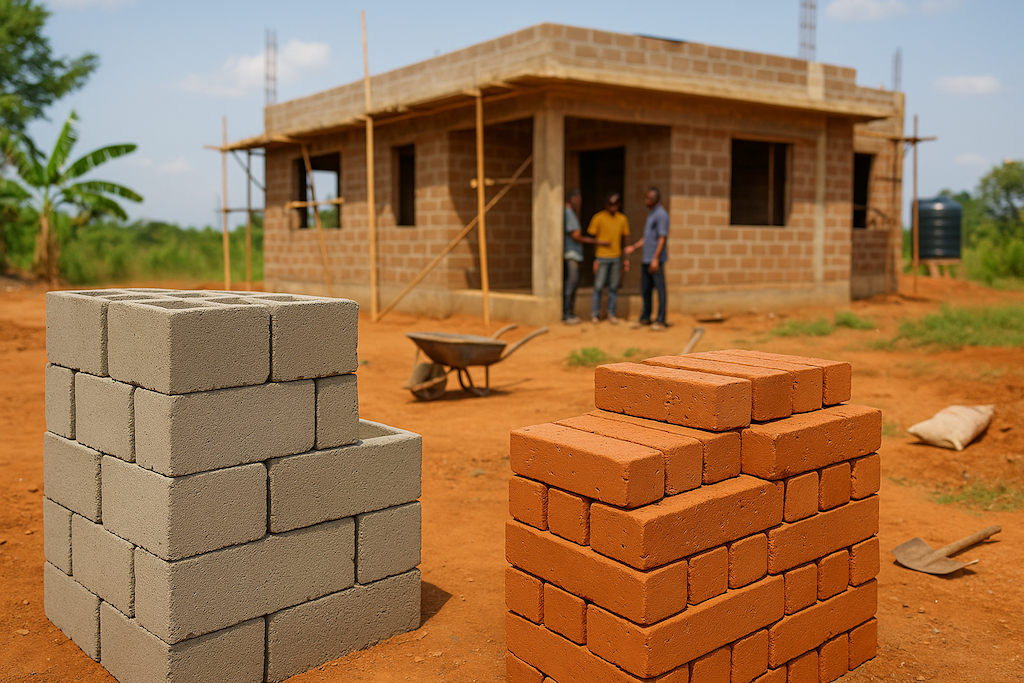
Once the site is prepared, the foundation is laid. The goal is to reach a stage where the building is “locked up”—walls up, roof on—so that you can pause construction without deterioration.
Estimated cost for a 3-bedroom house: GHS 60,000 – GHS 90,000
Phase 3: Blockwork and Superstructure
After the foundation, the walls are constructed. This is the most visible sign of progress.
Estimated cost for a 3-bedroom house: GHS 40,000 – GHS 60,000
Phase 4: Roofing
This is a critical phase—once the roof is on, the building is protected from weather, and you can pause construction safely.
Estimated cost for a 3-bedroom house: GHS 50,000 – GHS 80,000
Financing option for roofing: The Dophil “Roof Now, Pay Later” programme allows public servants to roof their houses with payments spread over 1–3 years .
Phase 5: Doors, Windows, and Security
Estimated cost for a 3-bedroom house: GHS 25,000 – GHS 40,000
Phase 6: Plastering and Flooring
Estimated cost for a 3-bedroom house: GHS 40,000 – GHS 60,000
Phase 7: Plumbing and Electrical
Estimated cost (3-bedroom):
-
Plumbing: GHS 15,000 – GHS 25,000
-
Electrical: GHS 12,000 – GHS 20,000
Phase 8: Painting and Finishing
Estimated cost for a 3-bedroom house: GHS 30,000 – GHS 50,000
Contingency Fund
Always set aside 15–20 per cent for unforeseen issues. Master Builders & Contractors recommends GHS 20,000 – GHS 40,000 as contingency for a 3-bedroom house .
Part 6: Total Estimated Cost Summary
3-Bedroom House (Based on Master Builders & Contractors)
| Phase | Cost Range (GHS) |
|---|---|
| Foundation | 60,000 – 90,000 |
| Blockwork | 40,000 – 60,000 |
| Roofing | 50,000 – 80,000 |
| Doors, windows, security | 25,000 – 40,000 |
| Plastering and flooring | 40,000 – 60,000 |
| Plumbing | 15,000 – 25,000 |
| Electrical | 12,000 – 20,000 |
| Painting and ceiling | 30,000 – 50,000 |
| Contingency | 20,000 – 40,000 |
| Total | 292,000 – 465,000 |
Source: Master Builders & Contractors breakdown
Note: This range excludes land acquisition and architectural fees.
Phased Saving Strategy on GHS 2,000 Monthly Salary
| Phase | Target (GHS) | Monthly Saving (GHS) | Time Required |
|---|---|---|---|
| Land (half plot) | 15,000 | 500 | 30 months |
| Architectural design | 20,000 (mid-range) | 500 | 40 months |
| Foundation | 75,000 (mid-range) | 500 | 150 months |
Realistic expectation: Building in phases takes years, not months. The trade-off is that you start living in your home sooner—once the structure is “locked up,” you can occupy the building while continuing to save for finishing phases.
Part 7: Practical Tips for Phased Builders
1. Start with Land, No Matter How Long It Takes
Nana Okuoba Akomea advises: “Start by saving and preparing yourself, by saving GHS 200 or GHS 300 each month and gradually working toward buying a small plot, which could cost about GHS 15,000” .
2. Design Within Your Budget, Not Your Dreams
Philips Construction’s most important advice: “Allow them to design your home according to what you can afford financially. In this way, your house will be designed within your financial capabilities and not exceed them” .
A modest 2-bedroom house that you complete is better than an ambitious 4-bedroom house that remains an abandoned foundation for a decade.
3. Use an Itemised Bill of Quantities, Not a Flat Per-Square-Metre Quote
The academic study confirms that flat per-square-metre quotes systematically omit essential components . Demand an itemised BoQ that includes structural steel, plastering, floor screed, and full electrical and plumbing services.
Free tool: Use GhanaHousePlanner (ghanahouseplanner.com) to generate accurate, itemised estimates based on current local material prices .
4. Buy Materials Incrementally
Nana Okuoba Akomea advises: “Buying a little material each month, such as two bags of cement, will eventually be enough to make meaningful progress” .
At current cement prices of GHS 80–85 per bag, buying two bags per month costs GHS 160–170. Over two years, that is 48 bags—enough for a significant portion of blockwork.
5. Take Advantage of Supplier Credit Programmes
The Dophil “Roof Now, Pay Later” programme is an example of supplier-driven financing that targets stalled projects . Similar programmes may exist for other building materials—ask your supplier.
6. Save Unexpected Income
Nana Okuoba Akomea advises: “If they received gifts or unexpected cash, he advised them to save part of this, explaining that even small amounts add up over time” .
7. Educate Yourself
Nana Okuoba Akomea emphasises that “knowledge is also important, as an understanding of how buildings work would mean that workers do not take advantage of you.” For example, “if the land is 70 by 100 feet, one should know how many blocks are needed for a wall before construction with the right calculation” .
Part 8: Common Mistakes to Avoid
Mistake 1: Starting Without Land
Many aspiring builders spend years saving a lump sum without acquiring land first. Meanwhile, land prices appreciate. Nana Okuoba Akomea’s approach—saving for land first, then building incrementally—is more effective .
Mistake 2: Accepting Flat Per-Square-Metre Quotes
The academic study confirms that these quotes omit essential components, leading to cost overruns of 29–98 per cent .
Mistake 3: No Contingency Budget
Unexpected costs will arise. Master Builders & Contractors recommends GHS 20,000 – GHS 40,000 contingency for a 3-bedroom house .
Mistake 4: Designing Before You Have Land
Philips Construction advises acquiring land (or saving for it) before engaging an architect. Otherwise, you may design a home for land you cannot afford .
Mistake 5: Not Locking In Supplier Prices
For serious self-builders, the Government Statistician recommends “locking up supplier prices through medium-term contracts to reduce exposure to volatile material costs.”
Conclusion: The Phased Building Revolution
Ghanaians are completing homes without bank loans not because they have discovered a secret source of cheap credit, but because they have rediscovered a traditional approach to building: one phase at a time, one bag of cement at a time, one month’s savings at a time.
The approach is not slower than waiting to save the full amount. It is faster, because you start immediately. Instead of saving for ten years and then building for one, you build over ten years while living on the property. Instead of being overwhelmed by a GHS 300,000 total, you focus on a GHS 30,000 foundation.
Philips Construction’s advice remains the most practical: “Beginning with a half plot of land or designing a house that fits within a predetermined budget are both small steps contributing toward achieving the long-term goal of homeownership” .
Your next step is not to save GHS 300,000. Your next step is to save GHS 200 this month toward land. Then GHS 200 next month. And the month after. By this time next year, you will be closer than you are today. By this time in five years, you could be locking up.
The tools exist: GhanaHousePlanner for accurate estimates , architect-guided design to fit your budget , supplier credit programmes for specific phases , and a growing community of phased builders who have proven that homeownership on a modest salary is not a dream—it is a plan.
The only question is whether you will start.
Quick Reference: Phased Building Checklist
| Phase | Action | Estimated Cost (GHS) | Timeline |
|---|---|---|---|
| 0 | Save for land | 15,000 (target) | 30+ months |
| 1 | Engage architect | 10,000 – 30,000 | 2–4 months |
| 2 | Foundation | 60,000 – 90,000 | 3–6 months |
| 3 | Blockwork | 40,000 – 60,000 | 3–6 months |
| 4 | Roofing | 50,000 – 80,000 | 2–4 months |
| 5 | Doors, windows | 25,000 – 40,000 | 1–2 months |
| 6 | Plastering/flooring | 40,000 – 60,000 | 2–4 months |
| 7 | Plumbing/electrical | 27,000 – 45,000 | 2–3 months |
| 8 | Painting/finishing | 30,000 – 50,000 | 1–2 months |
Financing alternatives:
-
Developer payment plans: Zero interest, no credit check
-
Roof Now, Pay Later: 1–3 year repayment for roofing
-
Incremental material purchases: Buy 2 bags of cement monthly
History and Facts Section
The Phased Building Movement in Ghana – Key Developments
| Year | Development | Significance |
|---|---|---|
| 2022 | Academic study on incremental building | Confirms low-income households priced out of mortgages |
| 2024 | Dophil “Roof Now, Pay Later” launched | First supplier credit programme for stalled projects |
| 2025 | Philips Construction phased model published | Demonstrated homeownership on GHS 2,000–2,500 salary |
| 2025 | Nana Okuoba Akomea GHS 1,000 salary model | Showed building possible on minimum wage |
| 2025 | VAAL developer payment plans documented | Zero-interest alternative to mortgages |
| 2026 | GhanaHousePlanner platform launched | Free itemised cost estimation tool |
| 2026 | “Completeness gap” academic study published | Validated GHP model; confirmed 29–98% underestimates in informal quotes |
Estimated Phased Building Costs (3-Bedroom, Greater Accra, 2026)
| Component | Low Estimate (GHS) | High Estimate (GHS) | Source |
|---|---|---|---|
| Land (half plot) | 15,000 | 30,000+ | |
| Foundation | 60,000 | 90,000 | |
| Blockwork | 40,000 | 60,000 | |
| Roofing | 50,000 | 80,000 | |
| Doors/windows | 25,000 | 40,000 | |
| Plastering/flooring | 40,000 | 60,000 | |
| Plumbing | 15,000 | 25,000 | |
| Electrical | 12,000 | 20,000 | |
| Painting/ceiling | 30,000 | 50,000 | |
| Contingency | 20,000 | 40,000 | |
| Total | 292,000 | 465,000 |
FAQ Section
Q1: Can I really build a house on a GHS 2,000 monthly salary in Ghana?
A: Yes. Philips Construction has demonstrated that with a half plot of land, architect-guided design within your budget, and a contractor who breaks costs into manageable stages, homeownership is achievable on GHS 2,000–2,500 monthly .
Q2: How much money do I need to start building?
A: You do not need the total amount. You need enough for the first phase: GHS 15,000–30,000 for land (saved over time) or GHS 60,000–90,000 for foundation (if you already have land) . Nana Okuoba Akomea advises starting by saving GHS 200–300 monthly toward land .
Q3: What is a developer payment plan?
A: A payment schedule offered by property developers that allows you to pay for an off-plan home in instalments over the construction period. Key advantages: zero interest, no credit check, total price fixed on day one .
Q4: What is the “completeness gap” in construction quotes?
A: A systematic discrepancy between informal contractor quotes and actual costs. Informal quotes often omit structural steel, plastering, floor screed, and full electrical/plumbing services, resulting in underestimates of 29–98 per cent .
Q5: How do I get an accurate construction estimate?
A: Use an itemised Bill of Quantities—not a flat per-square-metre quote. The free GhanaHousePlanner tool (ghanahouseplanner.com) provides region-aware, itemised estimates updated with current local material prices .
Q6: What is the “Roof Now, Pay Later” programme?
A: An initiative by Dophil Roofing System and Societe Generale that provides roofing materials to public servants with payments spread over 1 to 3 years. It targets builders whose projects have stalled due to financial constraints .
Q7: How long does phased building take?
A: Phased building typically takes years, not months. The trade-off is that you start living in your home sooner—once the structure is “locked up” (walls and roof complete), you can occupy while saving for finishing phases.
Q8: Can I combine a developer payment plan with a bank mortgage?
A: Yes. A hybrid strategy exists: buy off-plan using the developer’s payment schedule, then refinance the remaining balance into a bank mortgage after completion. You get the price lock-in of off-plan buying with the long repayment period of a bank product .
Q9: Do I need an architect if I’m building on a budget?
A: Yes. Philips Construction advises that an architect ensures your house is “designed within your financial capabilities and not exceed them”—preventing the common mistake of designing a home you cannot afford to complete .
Q10: Is it better to build in phases or save the full amount first?
A: Build in phases. Saving the full amount first means you pay rent for years while land prices appreciate and construction costs increase. Building in phases allows you to occupy the property sooner and protects you against cost escalation.
Source: Accra Street Journal
Last Updated on June 14, 2026 by Samuel Kwame Boadu
Disclaimer: Some content on Accra Street Journal may be aggregated, summarized, or edited from third-party sources for informational purposes. Images and media are used under fair use or royalty-free licenses. Accra Street Journal is a subsidiary of SamBoad Publishing Hub under SamBoad Business Group Ltd, registered in Ghana since 2014.
For concerns or inquiries, please visit our Privacy Policy or Contact Page.

Samuel Kwame Boadu is a Ghanaian media entrepreneur and storyteller with a passion for amplifying urban voices and uncovering everyday truths. He is the Editor-in-Chief and Founder of Accra Street Journal, a dynamic digital platform dedicated to capturing the pulse of Ghana’s capital—its people, culture, challenges, business, sports and innovations.