







The Bank of Ghana (BoG) has expanded participation in the country’s Credit Reporting System (CRS), a move expected to fundamentally change how banks assess borrowers and determine loan interest rates.
Under the new directive, lenders will increasingly be required to rely on detailed credit data and borrower behaviour rather than broad assumptions when making lending decisions.

For analysts tracking financial sector reforms, the policy signals a shift toward risk-based lending, where the cost of borrowing reflects an individual’s actual financial behaviour.
📢 GET A DETAILED ARTICLES + JOBS
Join ASJ's WhatsApp Channel and never miss a post or opportunity.

Expanded Credit Data Ecosystem
The directive enforces provisions under the Credit Reporting Regulations, 2020 (L.I. 2394), requiring a wider group of institutions to participate in the credit reporting framework.
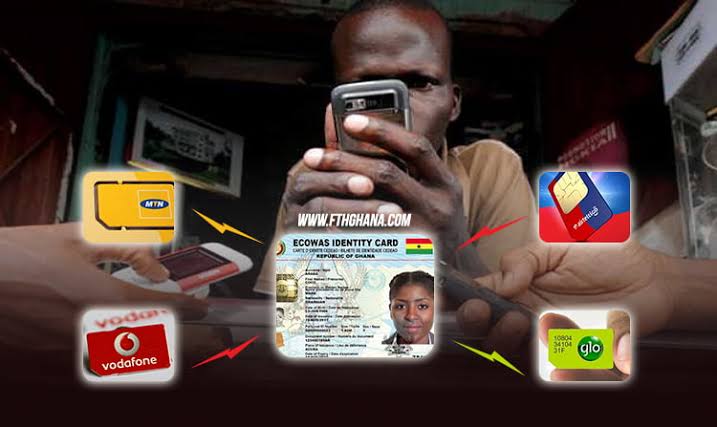
Previously, credit reporting largely depended on traditional banking data. Under the expanded system, multiple sectors must now share credit-related information with licensed credit bureaus.

Institutions required to submit credit data now include:
-
Telecommunications companies
-
Utility providers
-
Retail businesses offering instalment purchases
-
Financial technology companies
-
Student loan schemes
-
Government institutions providing loans to small businesses
By bringing these institutions into the reporting ecosystem, the BoG expects the credit system to produce more comprehensive financial profiles of borrowers.
Ending “Lazy” Credit Assessments
According to financial sector observers, the directive effectively means banks can no longer rely on simplistic lending practices.
In the past, some lenders applied similar interest rates across large categories of borrowers, often due to limited credit data or reluctance to obtain full credit reports.
With richer information now available through credit bureaus, banks are expected to conduct more detailed credit risk assessments.
This means lenders must analyze the specific financial behaviour of each borrower—including repayment history and bill payments—before determining loan pricing.
For the Accra Street Journal, the directive represents a clear push by regulators to improve discipline and transparency in Ghana’s credit market.
How Borrower Behaviour Will Influence Loan Rates
The expanded credit reporting framework will allow lenders to examine a wider range of financial indicators beyond traditional bank loans.
Credit bureaus may now capture financial behaviour such as:

-
Utility bill payments
-
Telecommunications bills
-
Instalment purchase repayments
-
Student loan repayment records
-
Mobile money credit obligations
These data points provide a clearer picture of a borrower’s financial discipline.
Under a risk-based lending model, borrowers with strong repayment histories and consistent bill payments may be classified as lower-risk customers.
Such borrowers could benefit from:
-
Lower interest rates
-
Easier access to credit
-
Faster loan approval processes
Conversely, individuals with weaker credit histories or irregular repayment behaviour may face higher borrowing costs or tighter lending conditions.
Benefits for Responsible Borrowers
The Bank of Ghana says credit information sharing benefits both lenders and borrowers.
For financial institutions, improved data helps reduce credit risk and loan defaults, strengthening the stability of the banking sector.
For borrowers, the system allows individuals with good financial behaviour to build credible credit profiles that can improve access to financing.
This shift is particularly important for entrepreneurs and small businesses seeking capital to expand operations.
Strengthening Ghana’s Financial Infrastructure
The expanded credit reporting system forms part of broader reforms aimed at strengthening the country’s financial architecture.
As Ghana’s financial sector becomes increasingly digital, regulators are seeking to ensure that data-driven lending practices replace older, less transparent credit evaluation methods.
The integration of fintech companies, mobile money providers and utility firms into the credit reporting ecosystem reflects the growing role of digital financial services in shaping consumer financial behaviour.

Implications for Ghana’s Lending Market
Financial analysts say the directive could gradually transform lending practices across Ghana.
By linking loan pricing directly to measurable financial behaviour, the policy encourages responsible borrowing while promoting fairness in credit access.
Banks will be expected to rely more heavily on credit bureau data when assessing loan applications, making it harder for institutions to bypass detailed risk analysis.
For the Accra Street Journal, the reform represents a significant step toward building a more transparent, data-driven and inclusive credit system.
If implemented effectively, the expanded credit reporting framework could help reduce loan defaults, lower borrowing costs for responsible borrowers and strengthen confidence in Ghana’s financial sector.
Source: Accra Street Journal
Last Updated on March 12, 2026 by Samuel Kwame Boadu
Disclaimer: Some content on Accra Street Journal may be aggregated, summarized, or edited from third-party sources for informational purposes. Images and media are used under fair use or royalty-free licenses. Accra Street Journal is a subsidiary of SamBoad Publishing Hub under SamBoad Business Group Ltd, registered in Ghana since 2014.
For concerns or inquiries, please visit our Privacy Policy or Contact Page.

Samuel Kwame Boadu is a Ghanaian media entrepreneur and storyteller with a passion for amplifying urban voices and uncovering everyday truths. He is the Editor-in-Chief and Founder of Accra Street Journal, a dynamic digital platform dedicated to capturing the pulse of Ghana’s capital—its people, culture, challenges, business, sports and innovations.