
11 min read
For most of the post-independence era, the narrative of Ghanaian business was one of resilience rather than reach. The ecosystem was defined by small-scale traders at Makola Market and state-owned enterprises struggling against structural adjustment. But over the past decade, a tectonic shift has occurred in the boardrooms of Accra. The city’s financial district is no longer just a satellite office for multinational extractive industries; it is becoming a launchpad for a distinctly Ghanaian breed of multinational corporation.
From the telecommunications towers connecting the rural expanses of the Democratic Republic of the Congo to the tax advisory firms managing cross-border mergers, Accra-based entities are rewriting the rules of South-South commerce. While Lagos remains the chaotic giant of West African enterprise, Accra is emerging as the region’s institutional anchor—a city where corporate governance standards are high enough to pass the due diligence of Wall Street, yet agile enough to navigate the informal realities of the continent.
Key Takeaways
- Global Services: Andersen Global recently absorbed Lima Partners in Accra, providing seamless tax and legal coverage from San Francisco to West Africa .
- By adopting the Andersen name, the Accra-based firm signals to Fortune 500 companies that their tax structuring and regulatory filings meet a global standard.
- Accra’s tech scene, driven by hubs like MEST Africa, is producing startups like Dataware Ghana and Think!Data Services, which have used Dutch trade funds to crack the UK market .
This ASJ report examines the specific financial and operational mechanics driving this wave of internationalization, analyzing how a critical mass of companies—spanning fintech, infrastructure, professional services, and logistics—are turning Ghana’s stability into a competitive export.
Quick Facts Box
-
Key Corridor: Accra is the host city for the Secretariat of the African Continental Free Trade Area (AfCFTA) , turning the city into a permanent diplomatic and commercial hub.
-
Notable Expats: Helios Towers (Telecoms) operates 14,000+ towers across nine markets including Tanzania, DRC, and Oman .
-
Financial Muscle: RNAQ Holdings has disbursed over 7.5 billion Ghana Cedis (GHC) in loans, establishing it as a dominant non-bank financial force .
-
Global Services: Andersen Global recently absorbed Lima Partners in Accra, providing seamless tax and legal coverage from San Francisco to West Africa .
-
Tech Exports: Dataware Ghana secured a UK client servicing 65,000 retailers, pushing AI solutions back into the European market .
Executive Overview
The internationalization of Accra’s corporate sector is not accidental. It is the product of three converging forces: the institutional gravity of the AfCFTA, a maturing digital infrastructure, and a new class of indigenous capital allocators.
Unlike the resource-extraction giants of other African capitals, Accra’s most promising multinationals are predominantly in services, logistics, and human capital. This distinction matters. It suggests a business model less vulnerable to commodity price shocks and more reliant on intellectual property, operational efficiency, and regulatory navigation.
However, the path to pan-African dominance is fraught with currency headwinds and infrastructure deficits. This analysis will dissect how specific firms—from the tower giant Helios to the diversified Sim Group—are hedging these risks.
Historical Background
From the Gold Coast to the Digital Gate
To understand Accra’s current business diaspora, one must look back at the economic liberalization of the 1980s and the subsequent “stable democracy dividend.” While neighbors experienced coups and civil wars, Ghana held relatively consistent elections. By the early 2000s, Accra had absorbed a critical mass of international NGO and diplomatic staff, creating a service economy that demanded higher standards in banking, IT, and logistics .
The real catalyst arrived in 2019 with the “Year of the Return,” which marketed Ghana as a homecoming destination for the African diaspora. This injected a wave of creative and venture capital, signaling to the world that Accra was open for equity, not just aid. The relocation of the AfCFTA Secretariat to Accra in 2020 cemented this status, transforming the city from a pleasant place to do business into the legal and administrative heart of a potential $3.4 trillion economic bloc .
Deep Analysis Sections
The Infrastructure Exporters: Tangible Assets Across Borders
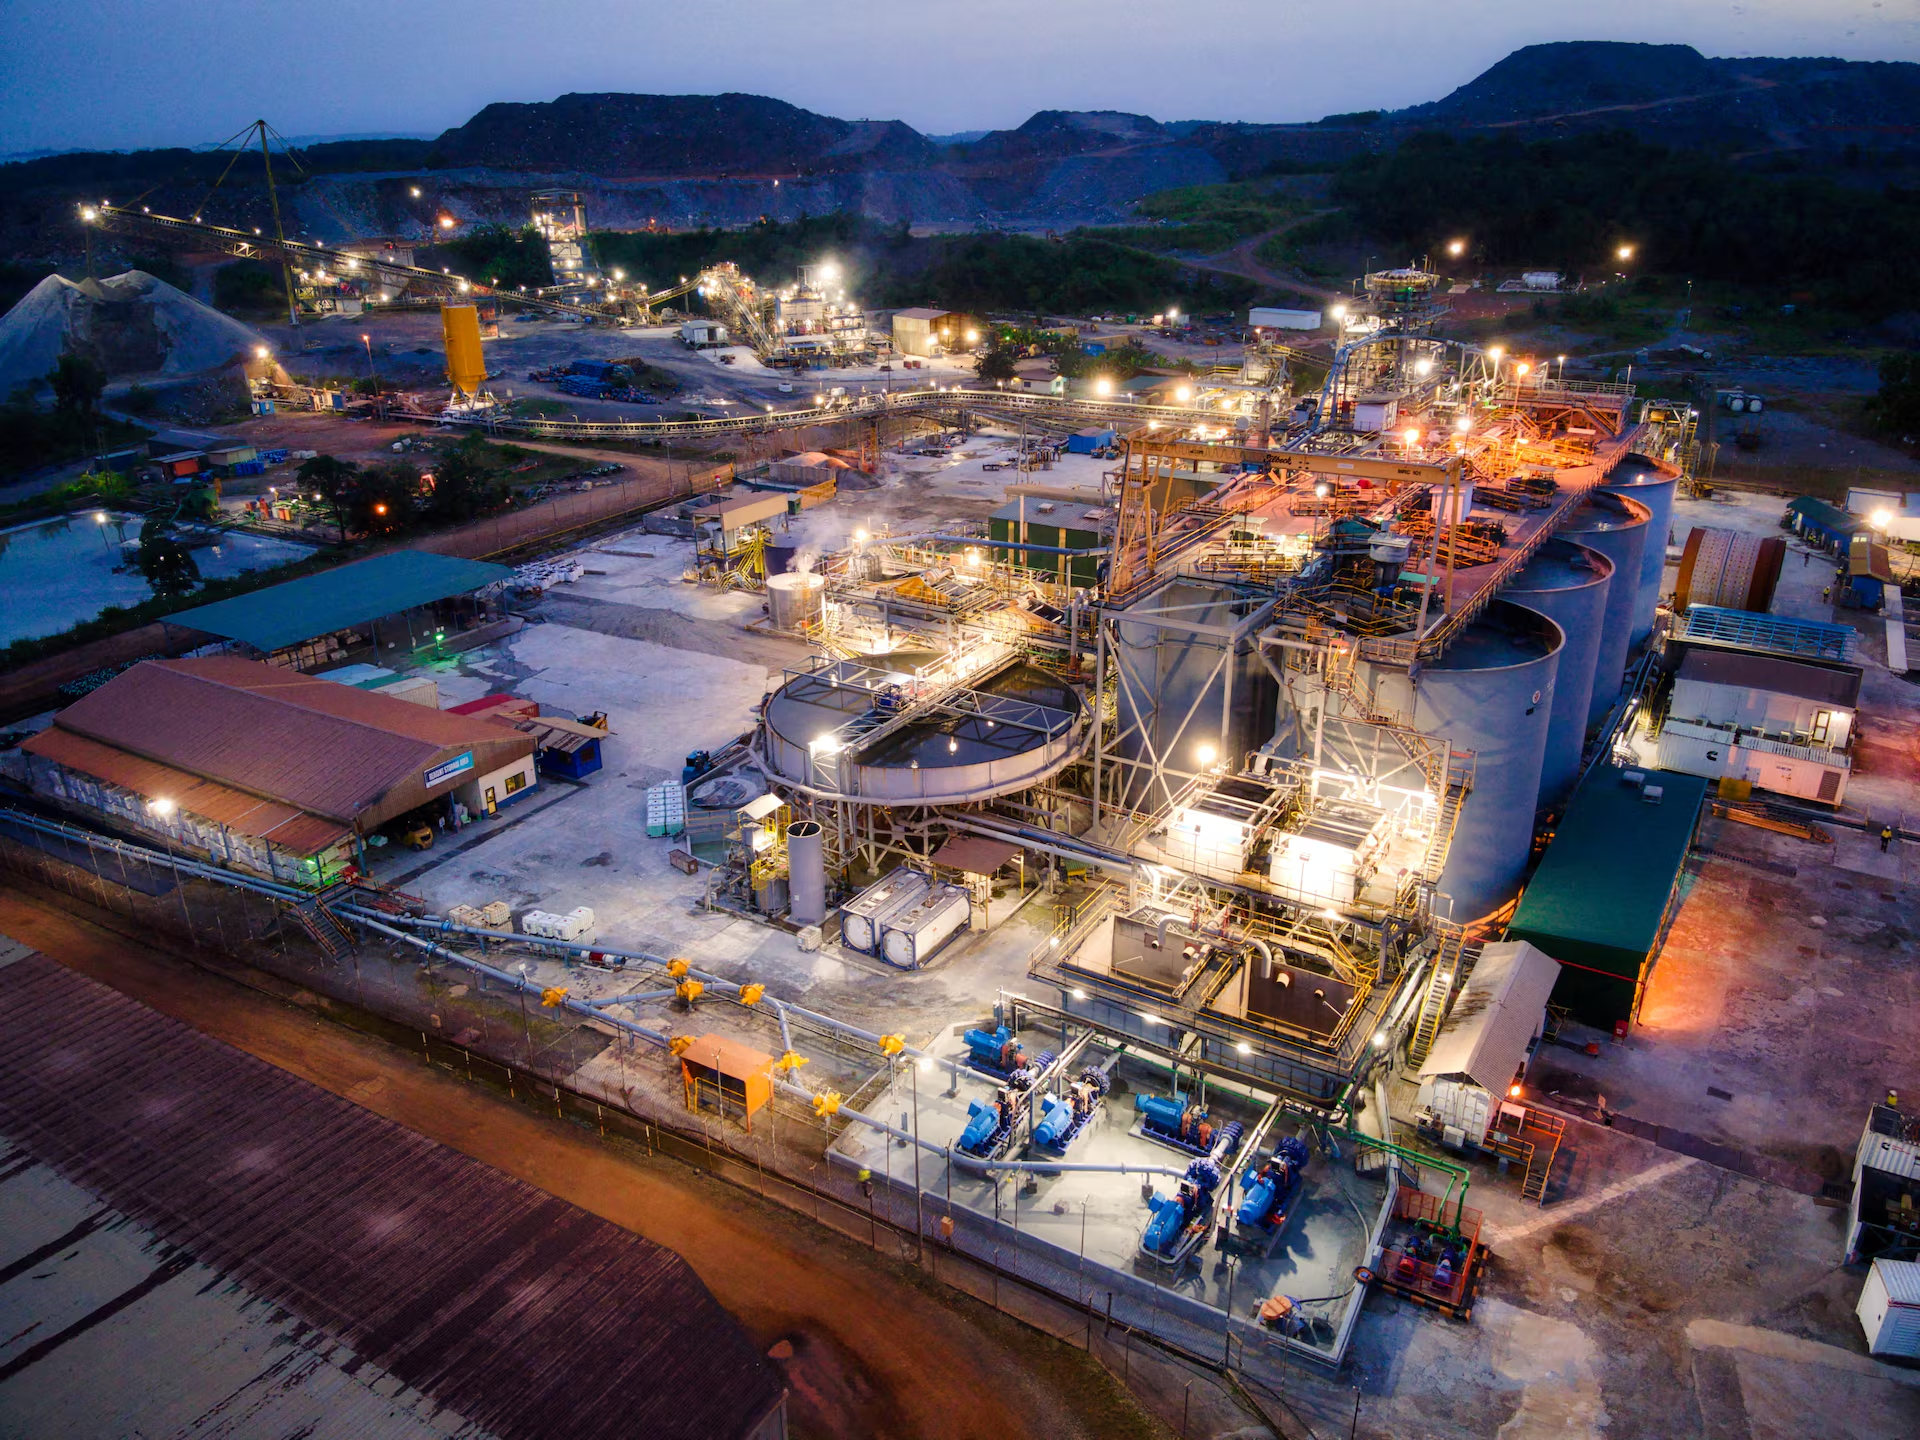
Perhaps the most visible success story is Helios Towers. Born out of the sale of Millicom’s (Tigo) towers in Ghana, the company utilized Accra as its beachhead. Today, Helios is a pan-African behemoth. What is fascinating about their model is the reverse flow of innovation; having perfected the art of keeping towers running on solar power in Ghana’s fluctuating grid, they exported that green tech playbook to South Africa and the Middle East .
The operational reality for Helios is one of asset-heavy patience. Their risk management strategy relies on multi-tenant anchor tenancies (MTN, Vodafone, AirtelTigo). By building a tower, they are effectively creating a monopoly on that specific piece of airspace. Their expansion from one country to nine in 15 years demonstrates a replicable model: use Ghanaian operational staff to manage infrastructure in Francophone and East African markets, navigating regulatory differences through local joint ventures .
Professional Services: The Rise of the “Trusted Advisor”
For international capital to flow into West Africa, it needs validation. This is where the professional services sector in Accra has stepped up. The recent integration of Lima Partners into Andersen Global is a case study in premium expansion .

This is not a typical outsourcing arrangement. By adopting the Andersen name, the Accra-based firm signals to Fortune 500 companies that their tax structuring and regulatory filings meet a global standard. For the wider industry, this creates a “lift all boats” effect. As Ghanaian firms solidify their compliance infrastructure, they lower the perceived political risk for foreign direct investment (FDI) into the region. The business model here is the export of credibility—charging a premium for the guarantee that cross-border work adheres to OECD guidelines.
Fintech and Lending: Replacing Aid with Yield
The financial services landscape in Accra is moving toward what Richard Nii Armah Quaye, founder of RNAQ Holdings, describes as “nation building through balance sheets.” Quaye’s Bills Microcredit has disbursed billions of cedis to SMEs, effectively filling the void left by cautious commercial banks .

The international implication is massive. RNAQ has effectively created an institutional angel investor network (Quick Angels) that is funding the next generation of Ghanaian franchises, such as Chickenman-Pizzaman, which then creates supply chain jobs. This model challenges the Western venture capital model by focusing on debt and equity for brick-and-mortar scale-ups rather than just software. For investors in London or Dubai, these Accra-based firms offer a hedge: a high-yield exposure to consumer goods growth without the volatility of local currency debt markets, as the lending is tied to real asset creation.
Logistics and Intra-African Trade
The Sim Group, led by Kofi Amoako-Attah, represents the old-school conglomerate model re-engineered for the 21st century. By nesting logistics, banking, and IT under one roof, Sim Group is positioning itself as the “FedEx of the Trans-African Highway” .
Their strategic outlook is tied directly to the removal of trade barriers under AfCFTA. For decades, moving a truck from Accra to Nairobi was a nightmare of bribery and border delays. Sim Group’s bet is that digitization of customs records (a key push by the Ghanaian Ministry of Communication) will smooth this path . The risk, however, remains the “last mile” of politics; infrastructure can be built, but border closures during political crises cannot be insured away.
Industry & Market Intelligence
The “Accra brand” carries a specific weight in the African market that differs from Lagos or Johannesburg. It is associated with human capital and stability.
Historically, multinationals entered Africa via South Africa (for regulatory sophistication) or Nigeria (for market size). Accra is now the tertiary entry point: the place where firms run their regional treasury or legal headquarters because of the quality of life and lower corruption perception.
However, the industry faces a severe risk: the depreciation of the Cedi. Companies like Helios and Sim Group earn revenue in Tanzanian Shillings, Congolese Francs, and Omani Rials, but report costs and strategic oversight in Cedis. The volatility requires sophisticated hedging desks, which strains middle-tier firms. The opportunity, conversely, is that a weak local currency makes Ghanaian professional services (lawyers, accountants, software developers) incredibly cheap to hire for the rest of the world .
The Tech Talent Pipeline
Accra’s tech scene, driven by hubs like MEST Africa, is producing startups like Dataware Ghana and Think!Data Services, which have used Dutch trade funds to crack the UK market . This is a “brain gain.” Rather than losing coders to Silicon Valley, Accra is keeping them to build AI solutions for British retailers. This business model—low overhead, high IP value—is the purest form of export Ghana has developed since cocoa.
Strategic Outlook
The AfCFTA Hinge
Accra’s future as a business hub hinges on the success of the AfCFTA. If the secretariat facilitates actual tariff reductions, Accra will become the Singapore of West Africa—a city-state (within a larger nation) of deal-making and legal arbitration. Companies are currently building “shell” presence in Accra to be first in line for these contracts, anticipating a boom in trade finance and logistics law .
Risks to the Horizon
-
The “Choking” Effect: As Accra real estate prices skyrocket due to demand, the operational costs for SMEs may outpace revenue growth, forcing startups to move to secondary cities like Kumasi.
-
Regulatory Friction: The Ghanaian tax authority is becoming more aggressive. While this boosts revenue, there is a risk of killing the golden goose if the informal sector—the bedrock of RNAQ’s loan portfolio—is overtaxed .
-
Succession Planning: Many of these conglomerates are founder-led. The transition from founder-entrepreneurs (like Quaye or Dadey) to institutional management will test the resilience of their pan-African ambitions .
The Long View
In ten years, expect to see a class of “Accra Alumni” executives running major African divisions of global banks. The city is becoming an export factory not just for goods, but for management talent. The legacy of the Helios Towers and KGL Groups of the world will not just be the towers or the financial assets, but the pool of Ghanaian operators who know how to keep a pan-African supply chain moving without breaking a sweat.
ASJ’s Conclusion
The story of Accra’s business class is one of quiet competence. Without the fanfare of Silicon Savannah or the raw heft of the JSE, Ghanaian companies are winning the marathon of African integration. They are building assets, servicing debt, and employing thousands—not through extraction, but through service delivery and logistical efficiency.

For the global investor, the signal is clear: Accra is no longer just a place to de-risk West African entry; it is a source of best practices for how to operate profitably in volatile frontier markets. The international waves these companies are making are still ripples, but the tide is turning in their favor.
FAQ Section
Q1: What makes Accra a favorable base for companies looking to expand across Africa?
A1: Accra offers a unique mix of relative political stability, a well-educated English-speaking workforce, and improving digital infrastructure. The presence of the AfCFTA Secretariat also provides unparalleled networking and policy insight opportunities for businesses looking to scale regionally.
Q2: Which specific Ghanaian company is the largest player in telecom infrastructure globally?
A2: Helios Towers, which originated in Accra, is the dominant player. They manage over 14,000 towers across nine markets, including strategic locations in Southern Africa and the Middle East .
Q3: How are Accra-based fintechs different from those in Lagos or Nairobi?
A3: Accra-based lenders like RNAQ Holdings focus heavily on “brick and mortar” SME lending and angel investing in physical franchises (like fast food), whereas other hubs tend to focus strictly on mobile payments or consumer lending.
Q4: Is the weakness of the Ghanaian Cedi a danger to these multinationals?
A4: Yes, it is a significant risk. While companies earn revenue in other stable currencies (USD, EUR, or local African currencies), they often report in Cedis. Fluctuations can distort profit margins and asset valuations, requiring expensive hedging strategies.
Q5: What role does the government play in supporting these expansions?
A5: The government is focusing on digital transformation and the “24-hour economy” to improve business efficiency. Initiatives by the Ministry of Communication aim to expand broadband and e-governance, which lowers the operational costs for tech and service exporters .
Q6: Are there any Accra-based companies listed on international stock exchanges?
A6: Helios Towers is a prime example, listed on the London Stock Exchange. This allows them to access deep capital markets to fund their tower builds in other African nations.
Q7: How does the AfCFTA specifically help a logistics company in Accra?
A7: AfCFTA aims to reduce the tariffs and non-tariff barriers (like differing customs forms) that slow down trade. For a company like Sim Group, this means faster transit times from Accra to East Africa, allowing them to compete with global logistics giants .
Q8: What is “Quick Angels” and why is it significant?
A8: Launched by RNAQ Holdings, it is Ghana’s first institutionalized angel investment firm. It signifies a maturation of the startup ecosystem, providing equity funding (not just loans) to high-growth sectors like media and healthcare .
Q9: Are there opportunities for foreign investors to partner with these Accra firms?
A9: Yes. Many of these firms are looking for technical partners or development finance institutions (DFIs) to co-invest in infrastructure projects or provide lines of credit for lending portfolios, though they generally prefer to retain majority local ownership.
Q10: What is the future of the “Made in Ghana” service export?
A10: The future is in Business Process Outsourcing (BPO) and AI data labeling. Firms like Dataware are proving that Ghanaian engineers can service European clients remotely, turning Accra into a nearshoring destination for tech talent
Source: Accra Street Journal
Last Updated on May 15, 2026 by Samuel Kwame Boadu
Disclaimer: Some content on Accra Street Journal may be aggregated, summarized, or edited from third-party sources for informational purposes. Images and media are used under fair use or royalty-free licenses. Accra Street Journal is a subsidiary of SamBoad Publishing Hub under SamBoad Business Group Ltd, registered in Ghana since 2014.
For concerns or inquiries, please visit our Privacy Policy or Contact Page.

Samuel Kwame Boadu is a Ghanaian media entrepreneur and storyteller with a passion for amplifying urban voices and uncovering everyday truths. He is the Editor-in-Chief and Founder of Accra Street Journal, a dynamic digital platform dedicated to capturing the pulse of Ghana’s capital—its people, culture, challenges, business, sports and innovations.
Use the following reference when citing or referencing this article.
Your feedback helps us improve our journalism.
Report an Error
Help us maintain accuracy. Let our editorial team know if you spot an issue in this article.
Report a problem with this article