The “Buy Now, Pay Later” (BNPL) phone model is rapidly transforming Ghana’s consumer electronics market, making smartphones accessible to millions who cannot afford the full upfront cost. This article explores the business model, key players, and what it means for the Ghanaian economy.
Introduction: The Problem BNPL Solves
An entry-level smartphone costs up to 95% of a low-income earner’s monthly wages in Sub-Saharan Africa . Approximately 76% of the region’s population does not own a smartphone, making device affordability the single biggest barrier to digital inclusion on the continent .

In Ghana, the situation is similar. With only 13% of the eligible population having access to borrowing, traditional financing is out of reach for many . This is where BNPL phone schemes come in. They allow customers to take home a device with a small deposit and spread the remaining cost over weeks or months.
📢 GET A DETAILED ARTICLES + JOBS
Join ASJ's WhatsApp Channel and never miss a post or opportunity.

The Core Business Model: How It Works
The BNPL phone business model in Ghana operates on a simple but effective principle: provide access to a productive asset (a smartphone) through flexible payment plans, while generating revenue through interest, fees, or bundled services.
Key Players and Their Models
MTN’s Pick and Pay Later: MTN Ghana, in partnership with Access Bank, MobileMoney Ltd, Hollard Insurance, and PaySwitch, offers Samsung smartphones through a credit-scoring system . Customers dial *170#, undergo a credit check, pay an initial deposit via MoMo, and repay the balance over 4 or 6 months . Default results in the phone being locked after 24 hours . The model earns revenue through interest, insurance fees, and increased mobile data usage (customers get 3GB free data monthly for 6 months) .

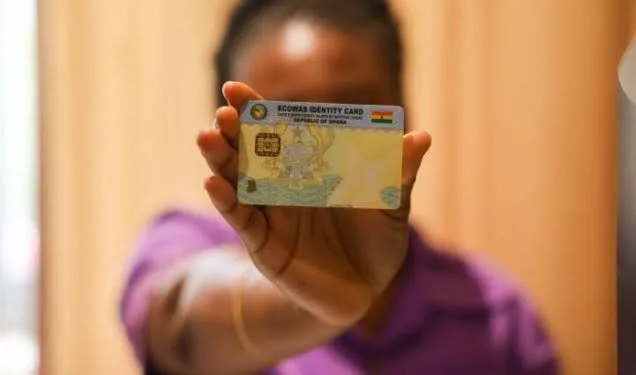
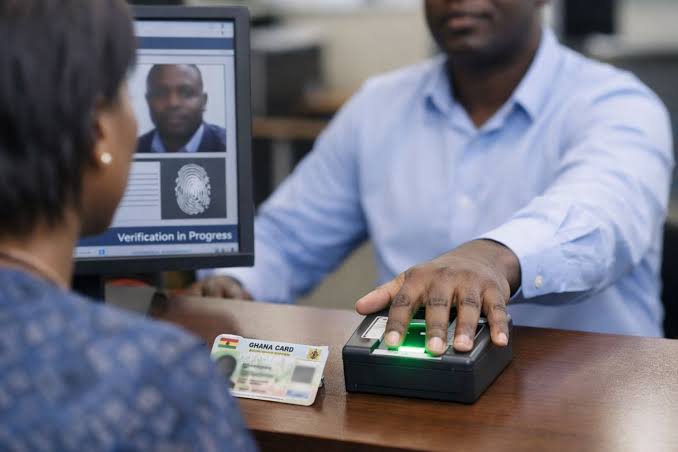
Hala GH: This Ghanaian company allows customers to acquire a Samsung smartphone with a minimum deposit of GH¢300, spreading the balance over four months . The registration process requires only a Ghana Card and a guarantor . Hala GH uses Samsung Knox Guard to lock devices if payments are defaulted . Revenue comes from the device margin and potentially service fees built into the repayment structure.
M-KOPA: This Pan-African fintech operates a pay-as-you-go model where customers pay daily based on the total cost divided by 365 days . M-KOPA has unlocked over GHS 1.2 billion in credit for more than 550,000 customers in Ghana and operates in all 16 regions . Its “More than a Phone” offering bundles health insurance (through Turaco), data, and device protection directly into every device . Revenue comes from the device margin, embedded service fees, and the value of customer data (67% accessed health insurance for the first time through the partnership) . The model generates $400 million in annual recurring revenue across Africa, with default rates around 10% .
MaxBuy: Ghana’s leading retail electronics store offers BNPL options to all income levels, from high-income earners to low-income households . Its partnership with Fido allows eligible customers to get a Tecno or Infinix smartphone and spread the cost across up to 6 equal installments . Revenue comes from the device margin and fees from the financing partner.
Motito: This Accra-based fintech startup offers a “PaySmallSmall” layaway-first model where customers secure today’s price so inflation does not increase the cost . Payments are made daily, weekly, or monthly. By building trust through on-time payments, customers unlock “Early Pickup” and can collect items before completing payment. Motito has raised $143,000 from investors including Visa Accelerator and Ecobank Transnational .
Why the BNPL Model Works
For Consumers
BNPL removes the upfront cost barrier, allowing people to own smartphones they would otherwise never access. 55% of M-KOPA customers use their device for income generation, 54% report earning more since purchasing their smartphone, and 76% say their overall quality of life has improved . For women, the impact is significant. 41% said their M-KOPA smartphone was their first phone, and 43% of female customers said they chose an M-KOPA phone specifically for the bundled health insurance .
For Businesses
BNPL unlocks a massive new customer base. M-KOPA now operates the largest direct sales force in sub-Saharan Africa, with over 30,000 agents going door-to-door . MTN’s Pick and Pay Later has been a major success, with the scheme expanding across the country . For retailers like MaxBuy, BNPL allows them to serve customers across all income levels, increasing sales and customer loyalty .
The Risks: Credit-Dependent Citizens
Despite its benefits, the BNPL model is not without risks. An analysis from News Ghana warns that BNPL risks creating a new class of “credit-dependent citizens” whose monthly budgets are built on fragmented, deferred obligations . Informal surveys estimate that up to 30% of BNPL users in Accra have at least three concurrent instalment plans . This can lead to lower household savings, weaker consumer confidence, and higher mental health burdens .
Default rates are a concern. M-KOPA reports default rates around 10%, slightly lower than regional bank averages but higher than U.S. consumer loan benchmarks . The company argues that “financed phones are a productive asset in people’s lives and a key part of how everyday earners generate their income,” which helps keep default rates stable .
The Regulatory Landscape
The BNPL model operates in a regulatory grey area in Ghana. Some experts have called for:

-
Capping effective interest rates and mandating transparent disclosure of total credit costs
-
Requiring plain-language contracts readable at a secondary school level
-
Integrating repayment data into credit bureaus to build credit histories
The Ghana Card has become central to BNPL schemes, serving as a digital ID for credit verification. Former Vice President Dr. Mahamudu Bawumia has praised this development, noting that it builds the foundation of a credit economy that can help advance Ghana’s economic development .
ASJ Conclusion
The BNPL phone business model in Ghana is a powerful tool for financial and digital inclusion. It has unlocked over GHS 1.2 billion in credit for more than 550,000 customers and is reaching underserved populations . However, it also carries risks of over-indebtedness and credit dependency. The future will depend on how well regulators balance access with protection, and how businesses innovate to deliver value without trapping customers in cycles of debt. For now, the BNPL phone model is here to stay, reshaping how Ghanaians access smartphones and digital services.
Quick Facts
| Provider | Deposit | Repayment Period | Key Feature |
|---|---|---|---|
| MTN Pick and Pay Later | Varies | 4–6 months | Samsung phones, 3GB free data/month |
| Hala GH | GH¢300 minimum | 4 months | Samsung Knox Guard lock if default |
| M-KOPA | Daily payments | 365 days | Health insurance and data bundled |
| MaxBuy + Fido | Varies | Up to 6 months | Tecno and Infinix smartphones |
| Motito | Varies | Daily/weekly/monthly | “PaySmallSmall” layaway-first model |
Frequently Asked Questions
1. What is the Buy Now Pay Later phone model?
It is a device financing model where customers can acquire a smartphone with a small initial deposit and spread the remaining cost over weeks or months through flexible payment plans.
2. Which companies offer BNPL phones in Ghana?
MTN (Pick and Pay Later), M-KOPA, Hala GH, MaxBuy (with Fido), and Motito all offer BNPL phone schemes .
3. How does MTN Pick and Pay Later work?
Customers dial *170#, complete a credit check, pay an initial deposit via MoMo, and repay the balance over 4 or 6 months. Default results in the phone being locked after 24 hours .
4. What is M-KOPA’s business model?
M-KOPA operates a pay-as-you-go model where customers pay daily based on the total cost divided by 365 days. It bundles health insurance, data, and device protection into every device .
5. Is BNPL regulated in Ghana?
BNPL operates in a regulatory grey area. Some experts have called for capping interest rates, mandating plain-language contracts, and integrating repayment data into credit bureaus .
6. What are the risks of BNPL phones?
Risks include over-indebtedness, juggling multiple instalment plans, lower household savings, and mental health burdens. M-KOPA reports default rates around 10%
Source: Accra Street Journal
Last Updated on August 29, 2026 by Samuel Kwame Boadu
Disclaimer: Some content on Accra Street Journal may be aggregated, summarized, or edited from third-party sources for informational purposes. Images and media are used under fair use or royalty-free licenses. Accra Street Journal is a subsidiary of SamBoad Publishing Hub under SamBoad Business Group Ltd, registered in Ghana since 2014.
For concerns or inquiries, please visit our Privacy Policy or Contact Page.

Samuel Kwame Boadu is a Ghanaian media entrepreneur and storyteller with a passion for amplifying urban voices and uncovering everyday truths. He is the Editor-in-Chief and Founder of Accra Street Journal, a dynamic digital platform dedicated to capturing the pulse of Ghana’s capital—its people, culture, challenges, business, sports and innovations.